
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Takashimaya Company (TSE:8233) Shares Sit 109% Above Fair Value Following August Sales Update
Takashimaya Company (TSE:8233) has released its August 2026 sales update, reporting a 3.9% year-on-year change, with Takashimaya and two regional stores posting a 3.8% shift over the same period.
Recent trading suggests some profit taking. The share price has fallen 11.2% over the past month and 12.4% over 90 days, even though Takashimaya Company's year to date share price return is 28.1% and its 5 year total shareholder return is 273.4%. This indicates that long term momentum remains intact.
Scan how Takashimaya Company compares with other retailers showing strong price trends and fundamentals by reviewing the hand picked 17 high quality undervalued stocks.
Bulls point to Takashimaya Company’s strong long term returns and recent sales data, while bears focus on the pullback and current loss making status. Which side does the valuation evidence lean toward next?
Preferred price to sales of 1.5x for Takashimaya Company: Is it justified?
The current price to sales ratio of 1.5x sits above the JP Multiline Retail industry average of 0.6x, even though Takashimaya Company is loss making at the moment. At ¥2,117 per share, the stock also trades ahead of the SWS DCF estimate of future cash flow value of ¥1,011.57, which points to a rich entry price compared with both peers and modelled cash flows.
P/S tracks how much investors are paying for each unit of revenue and tends to matter more when profits are weak or volatile. For a retailer like Takashimaya Company, this ratio effectively shows how the market is weighing its ¥407,321 of annual revenue against the current lack of earnings and the mix of businesses across department stores, commercial property, finance and construction.
The market is pricing the shares on a premium P/S multiple relative to the sector, which suggests expectations around the business are stronger than those implied for the average multiline retailer. SWS also estimates a fair P/S ratio of 1.5x for Takashimaya Company, so the current market multiple already lines up with the level indicated by the valuation model.
Explore the SWS fair ratio for Takashimaya Company.
Result: Price-to-sales of 1.5x (OVERVALUED)
Still, the current loss of ¥4,108 and the premium ¥620.3b valuation mean any stumble in Takashimaya Company’s revenue mix could quickly challenge this pricing.
Find out about the key risks to this Takashimaya Company narrative.
Another view on Takashimaya Company’s value
Our DCF model presents a different perspective. At ¥2,117 per share, Takashimaya Company trades above the SWS DCF estimate of future cash flow value of ¥1,011.57. This indicates an overvalued outcome according to this method. Which signal do you treat as the anchor?
Look into how the SWS DCF model arrives at its fair value.
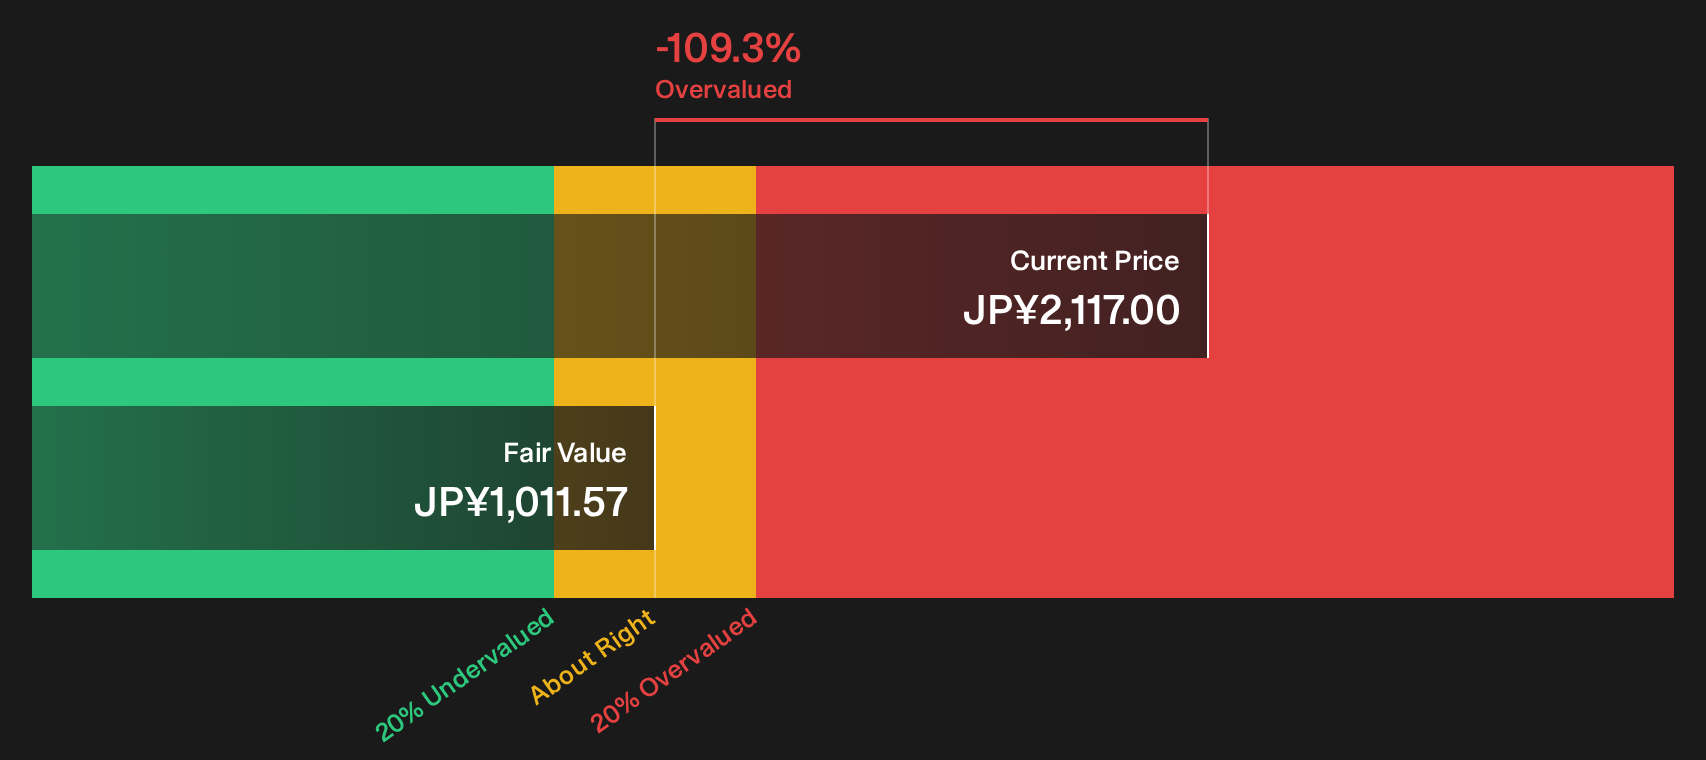
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Takashimaya Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn by the mix of strength and concern around Takashimaya Company today is reasonable. The fastest way to cut through that is to review the same information directly and decide what matters most to you by weighing the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Takashimaya Company?
If Takashimaya Company has you thinking harder about price, risk and income, use that momentum to broaden your watchlist with fresh opportunities.
- Chase potential mispricing by scanning the 17 high quality undervalued stocks that combine strong financial traits with more modest valuations.
- Build a steadier income stream by reviewing the 14 dividend fortresses that focus on higher yielding payers with resilience in mind.
- Protect the downside first by filtering for the 21 resilient stocks with low risk scores so you are not the last to spot sturdier balance sheets and calmer price moves.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com