
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Yves Return Change Maple Leaf Foods Stock Narrative
- Maple Leaf Foods has brought Yves Veggie Cuisine back to Canadian grocery shelves, reintroducing six refrigerated plant-based staples across multiple retail partners.
- The move puts a familiar, ready-to-use plant protein brand back into everyday meal routines. It reinforces Maple Leaf Foods' presence in the plant-based aisle without requiring consumers to change how they cook.
- We will look at how Maple Leaf Foods' investment narrative is affected by reviving Yves Veggie Cuisine as a core plant-based platform.
Scan opportunities around Maple Leaf Foods' plant-based push by comparing it with hand-picked peers in the 9 high quality undiscovered gems.
Maple Leaf Foods Investment Narrative Recap
An investor in Maple Leaf Foods needs to be comfortable with a protein-focused packaged food group that is trying to grow earnings through efficiency projects, premium and sustainable meat offerings, and a selective presence in plant-based. The Yves Veggie Cuisine return supports the product innovation and health focused narrative, but on its own it does not change the broad earnings profile.
The key near term swing factor remains how margins hold up as advertising and product launches increase while pork markets and consumer pricing stay uncertain. The biggest risk still sits in execution and cash generation, given one off items in recent results and debt that is not well covered by operating cash flow.
The Yves relaunch lines up most closely with Maple Leaf Foods long running push into value added and health oriented protein products, including its sustainable meats portfolio and brands such as Greenfield Natural Meat Co. That earlier effort created a proof point that consumers will pay for traceability and sustainability, which matters when the group leans into higher margin categories.
Plant-based deli and grounds products fit neatly into that same playbook. If the company can use existing automation and supply chain work, such as the Bacon Center of Excellence and London Poultry facility, to support efficient production and distribution of plant-based alongside meat, then the operational upside sits in scale and cost per unit, while the risk is extra SG&A if volumes do not follow.
Maple Leaf Foods' narrative projects CA$5.6b revenue and CA$467.3 million earnings by 2028. This projection is based on an assumed 4.2% yearly revenue growth and an earnings increase of about CA$372.7 million from CA$94.6 million today.
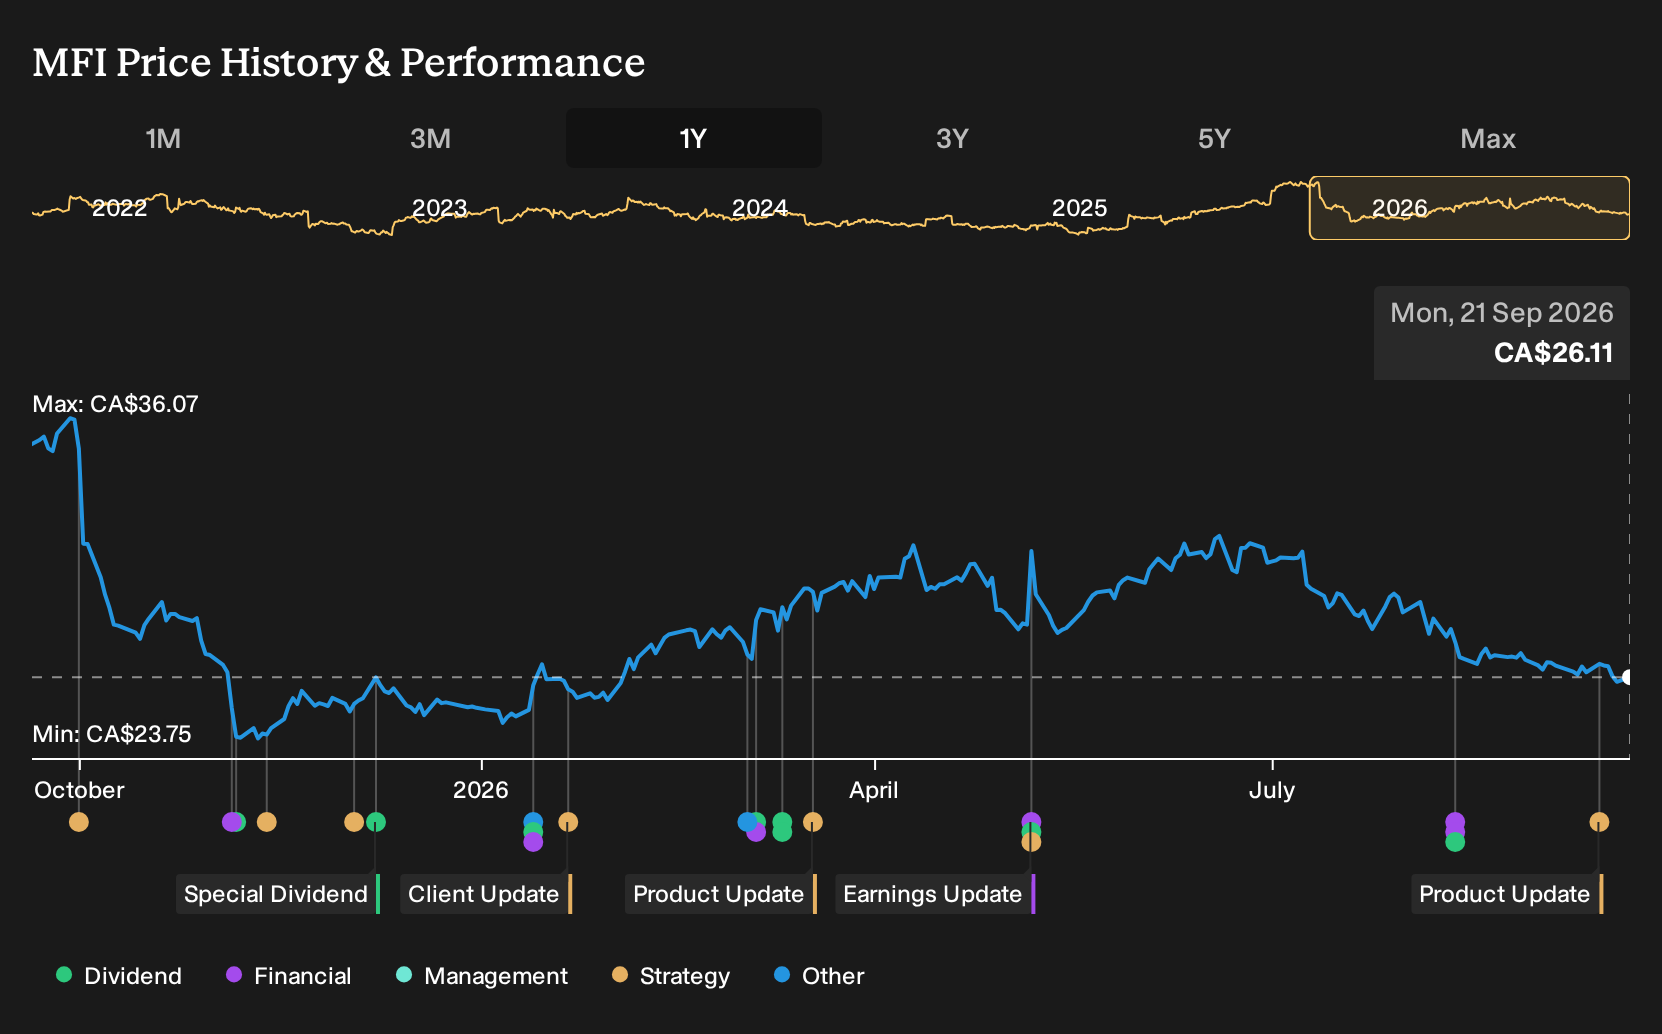
Discover why Maple Leaf Foods' fair value suggests a 37% potential upside to its current price before the market fully reflects that discount.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from CA$35.90 to about CA$83.26 per share. This shows just how far apart retail views on Maple Leaf Foods can be. When you layer in risks around pork markets, one-off benefits and the Canada Packers spin-off, it becomes even more important to test several alternative viewpoints yourself.
Explore another Maple Leaf Foods fair value estimate, including one that suggests as much as 219% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Maple Leaf Foods research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Maple Leaf Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Maple Leaf Foods' overall financial health at a glance.
Looking For More Investment Ideas Beyond Maple Leaf Foods?
If Maple Leaf Foods has sharpened your interest in where quality, value, and resilience intersect, broaden the search by using the Simply Wall St Screener to spot other opportunities that match your risk appetite and income needs.
- For investors who want potential value with quality fundamentals already in place, start with a curated set of 6 high quality undervalued stocks that combine strong business profiles with prices that may not fully reflect that strength yet.
- If capital preservation comes first and volatility sits lower on your priority list, focus on a 8 resilient stocks with low risk scores that emphasises resilient balance sheets and steadier risk scores.
- Income seekers who care about both yield and staying power can turn to a 1 dividend fortresses designed to surface payout profiles that aim to balance attractive income with durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com