
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Coty (COTY) Could Change Following Weak Revenue Outlook
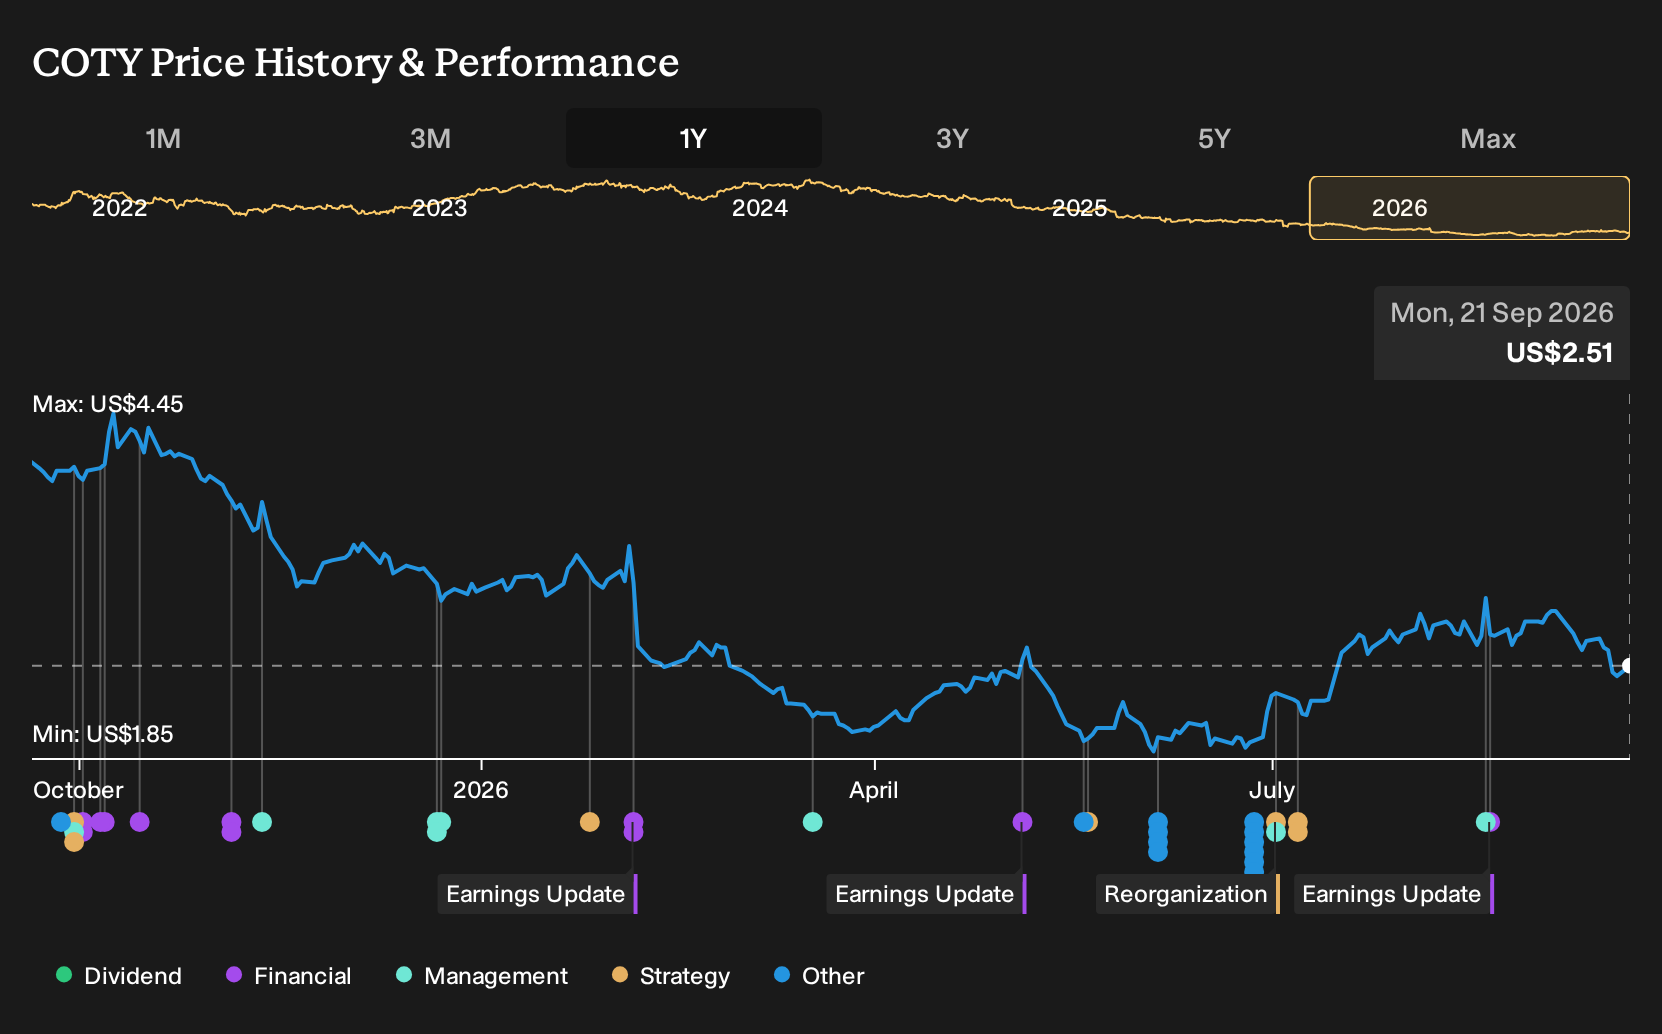
- Coty’s core operations have underperformed expectations, with weak organic revenue and a forecast revenue decline, while recent share issuances have diluted earnings per share.
- The combination of a softer core business and falling earnings per share raises questions about whether Coty must rely on acquisitions for growth.
- We will now assess how Coty’s weaker organic revenue and outlook could reshape the existing investment narrative around the business.
Coty Investment Narrative Recap
For an investor to stay in Coty today, there needs to be confidence that the prestige and mass beauty portfolio can stabilise organic sales despite pressure from retailer destocking, competition and weaker travel retail. The recent update of softer organic revenue and a guided revenue decline puts more weight on execution in these existing channels rather than on financial engineering.
The near term swing factor is whether Coty can defend margins while volumes stay under pressure, especially in the U.S. and Asia related travel retail. On the risk side, earnings per share dilution from new share issuances now sits alongside high debt as a key concern, since both tighten the room for error if the top line stays soft.
Recent commentary around earnings per share falling because of new share issuances is the announcement that ties closest to this news. It matters because any future improvement in profitability has to work harder on a per share basis when the share count is higher, which affects how quickly investors see progress in the numbers.
For a holder, that makes operational catalysts like inventory normalisation and product launches carry more weight than financial ones. If revenue remains under pressure and Coty turns to acquisitions to support growth, integration risk, higher leverage or further dilution could become more important than they looked before this setback in organic performance.
Coty's narrative projects US$5.7b revenue and US$155.0m earnings by 2029. This implies fairly flat yearly revenue trends and an earnings increase of about US$773.0m from a loss of US$618.0m today.
Uncover why Coty's fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Coty, the lowest analysts focus on debt risk rather than product momentum. They were already modeling revenue at about US$5.4b and earnings near US$179.0m by 2029, yet still arrived at a bearish US$1.62 view. That gap shows how sharply opinions can differ, so explore several narratives before deciding your own stance.
Explore 4 other Coty fair value estimates, including one that suggests it could be worth just $2.69.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Coty research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Coty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coty's overall financial health at a glance.
Looking For More Ideas Beyond Coty?
If Coty no longer feels like the right fit on its own, broaden your watchlist by using the Simply Wall St Screener to filter for other businesses that better match your risk tolerance, income needs, or value focus.
- For investors who want quality and value to line up, start by scanning a focused group of 30 high quality undervalued stocks that combine strong fundamentals with appealing pricing.
- If capital preservation matters just as much as upside, consider reviewing a curated 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- When you want sturdier financial footing as a starting point, work through a list of solid balance sheet and fundamentals (23 results) that may offer fewer balance sheet surprises over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com