
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Azimut Holding (BIT:AZM) Tests Its Growth Story On A Modest Undervalued View
Azimut Holding (BIT:AZM) has drawn fresh attention after its latest figures showed €1,574.105 million in revenue and €527.643 million in net income, giving investors updated reference points for assessing the asset manager’s valuation and recent share performance.
Recent trading suggests investors are still pricing in momentum at Azimut Holding, with a 1-day share price return of 1.36% and a year-to-date share price return of 10.78%. The 1-year total shareholder return of 34.88% points to stronger gains once dividends are included.
Compare Azimut Holding’s momentum with other asset managers by scanning a curated list of 174 high quality undervalued stocks that combine solid cash flows with conservative balance sheets.
Azimut Holding trades about 6% below average analyst targets and at a far steeper 27.6% discount to one intrinsic value estimate after a strong run. Is that caution warranted, or is the opportunity being mispriced?
Most Popular Narrative: 6% Undervalued
Azimut Holding closed at €39.58 against a narrative fair value of about €42.04, so the story centers on a modest value gap backed by a detailed view of its business mix, geography, and growth drivers.
Rapid expansion of high-net-worth and affluent clients, evidenced by record net inflows of €8.2 billion, robust organic growth in all geographies, and Azimut's deepening presence in international hubs, underscores the company's strong positioning to capture rising global demand for wealth and retirement solutions, which will directly increase assets under management and recurring revenue streams.
See why 27 investors see Azimut Holding as 6% undervalued.
Result: Fair Value of €42.04 (UNDERVALUED)
Still, the narrative around Azimut Holding could be knocked off course if fee pressure eats into its higher margin products, or if expansion into emerging markets brings heavier costs and currency volatility.
Find out about the key risks to this Azimut Holding narrative.
Another View on Azimut Holding’s Valuation
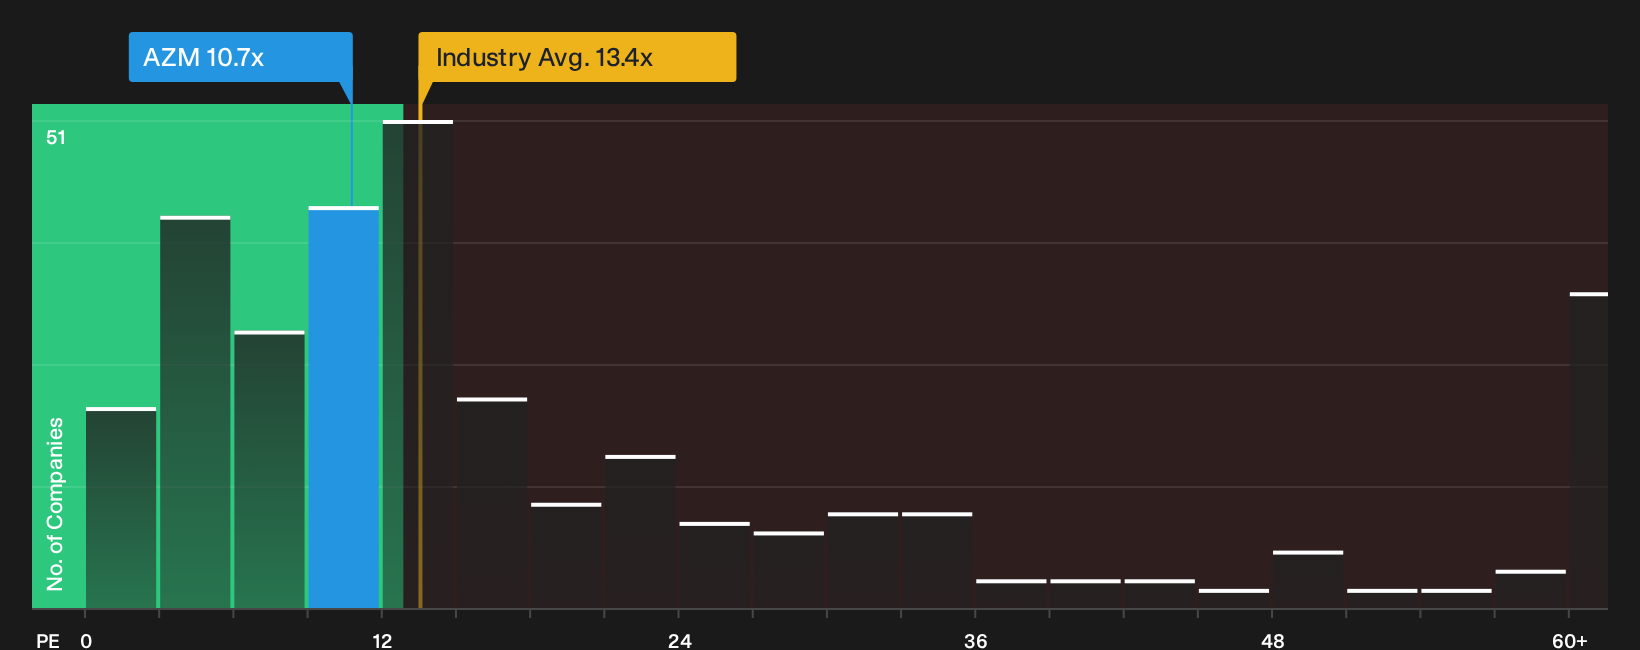
The earlier narrative leans on a fair value of about €42.04, yet Azimut Holding looks different when you focus on price multiples. The shares trade on a P/E of 10.7x, which is higher than local peers at 7.4x, but below the European Capital Markets average of 13.3x and under a fair ratio of 13.2x. This raises the question of whether the market is overpaying relative to Italian rivals or underpaying versus broader benchmarks.
To explore how those P/E gaps could close over time, and what that might imply for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Azimut Holding so far, with both concerns and bright spots in play, so move quickly to test the data yourself and weigh the trade offs. To frame that decision with a clear snapshot of the balance between opportunities and potential downsides, review the 3 key rewards and 2 important warning signs
Looking for more Azimut Holding sized investment ideas?
If Azimut Holding has sharpened your focus, do not stop here. Broaden your watchlist with fresh ideas that could suit different goals, timelines, and risk levels.
- Target dependable income by scanning companies that feature robust payouts and resilient cash generation through the 161 dividend fortresses.
- Hunt for quality that the market may be overlooking by filtering for stronger fundamentals and attractive pricing using the 615 high quality undiscovered gems.
- Prioritise capital protection by concentrating on businesses that show healthier finances and steadier risk profiles through the 229 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com