
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is MGM Resorts International (MGM) Undervalued Following Growth And Leverage Concerns?
Recent commentary around MGM Resorts International (MGM) has focused on its weaker long-term sales growth compared with the broader consumer discretionary sector, along with a sharp slide in return on invested capital, which has put the stock’s elevated leverage under a brighter spotlight.
On the price side, MGM Resorts International has seen momentum cool, with a 30-day share price return down 11.45% and a 90-day share price return down 17.46%, even though the year-to-date share price return is still up 6.14% and the 1-year total shareholder return is 12.29%. This indicates that investors may have become more cautious following earlier gains.
Compare MGM Resorts International's recent setbacks with other companies that pair healthier balance sheets and steadier momentum by scanning our hand picked 30 resilient stocks with low risk scores today.
MGM Resorts International still runs a broad gaming and entertainment platform, yet the recent share pullback raises a sharper question: Is this a resilient franchise temporarily marked down, or is the weaker growth and heavy debt already fairly reflected in the price?
Most Popular Narrative: 23% Undervalued
The most followed view on MGM Resorts International pegs fair value at $50.57, well above the last close at $38.73. This frames the recent share slide as a potential mispricing rather than a reset in expectations.
The development and opening of international integrated resorts, specifically the exclusive license in MGM Osaka, anticipated multibillion-dollar revenue potential, and Dubai project, should capture rising demand for destination travel among the growing global middle class, unlocking new recurring revenue streams and diversifying consolidated earnings over the long term.
See why 19 investors see MGM Resorts International as 23% undervalued.
Result: Fair Value of $50.57 (UNDERVALUED)
Still, the MGM Resorts International story can be knocked off course if large, long-dated projects strain cash flow or if physical visitation trends weaken further.
Find out about the key risks to this MGM Resorts International narrative.
Another View on MGM Resorts International’s Valuation
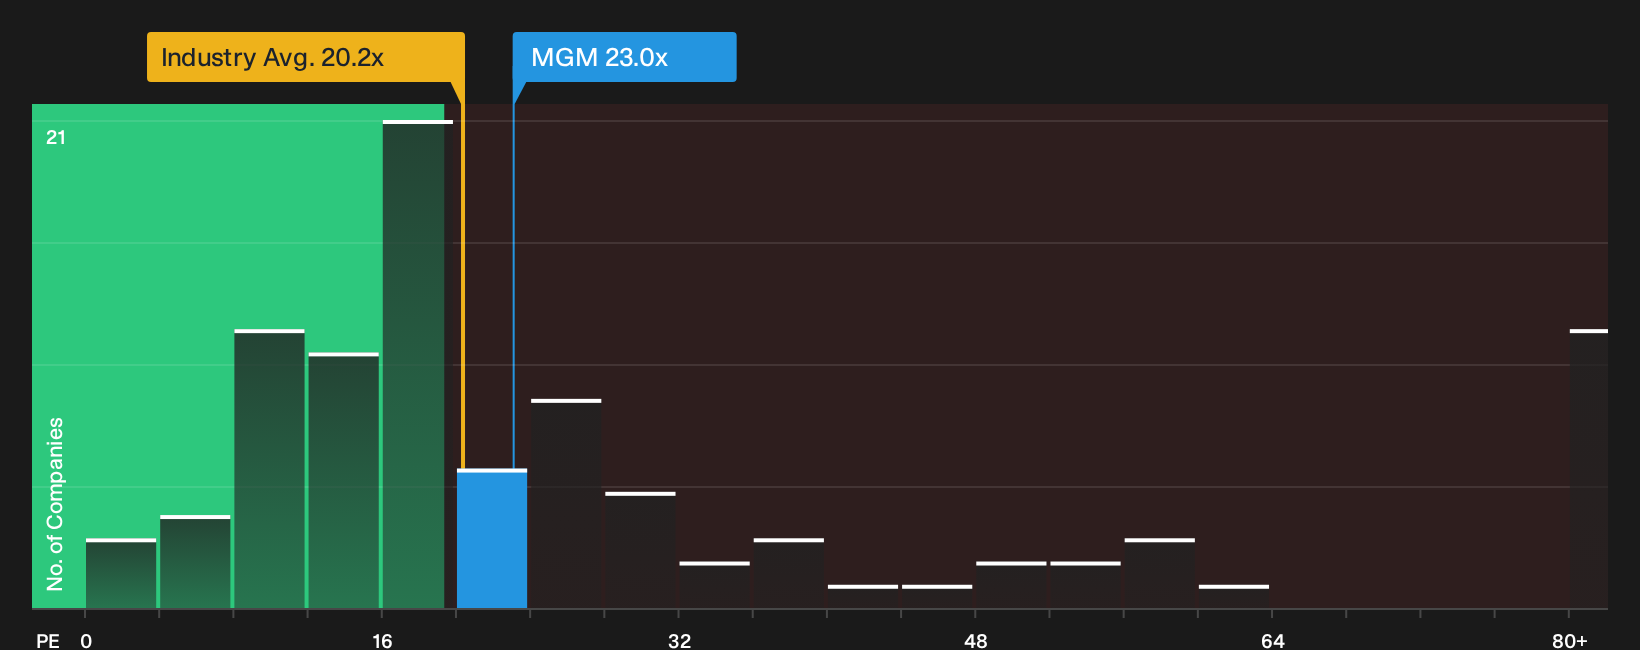
Multiples tell a different story. MGM Resorts International trades on a P/E of 23x, which is higher than its fair ratio of 18.3x, the US Hospitality industry at 20.3x, and a peer average of 13.2x. That gap points to valuation risk if sentiment or earnings expectations cool from here.
To pressure test those numbers against the underlying earnings profile and see what the ratios imply in practice, have a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on MGM Resorts International so far. If you want to move quickly and form your own view from the ground up, start by weighing its 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond MGM Resorts International?
If MGM Resorts International has your attention, do not stop here. Use fresh stock ideas as a cross-check so you are not leaning on a single storyline.
- Target cash rich opportunities and compare them against your current holdings by running a focused search through the list of solid balance sheet and fundamentals (23 results).
- Hunt for pricing gaps where quality and valuation meet by scanning the 17 high quality undiscovered gems before the wider market pays attention.
- Build a watchlist that is built around value and quality by screening for 30 high quality undervalued stocks right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com