
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Solaris Energy Infrastructure (SEI) Stock May Trade At A Premium As EBITDA Guidance Rises
Solaris Energy Infrastructure has delivered eye catching share gains in recent years, and the latest jump has pushed many investors to ask whether the current price is still supported by the company’s earnings power. With optimism around future profit potential back in focus after recent news, the question is how much of that story is already reflected in today’s valuation.
- Over the past 5 years, Solaris Energy Infrastructure has returned close to 10x, which puts real pressure on the earnings outlook to justify the move.
- Management now expects stronger profitability from core power services and the Omega Foundation Services acquisition, which can shift how investors think about future earnings and cash generation for the business.
- There is a second opinion on Solaris Energy Infrastructure worth weighing. See what analysts think Solaris Energy Infrastructure's shares could be worth.
The issue now is whether Solaris Energy Infrastructure's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to stress test this same earnings question across a broader set of companies tied to large scale infrastructure and power demand, take a look at 40 power grid technology and infrastructure stocks.
Does Solaris Energy Infrastructure Look Pricey on Earnings?
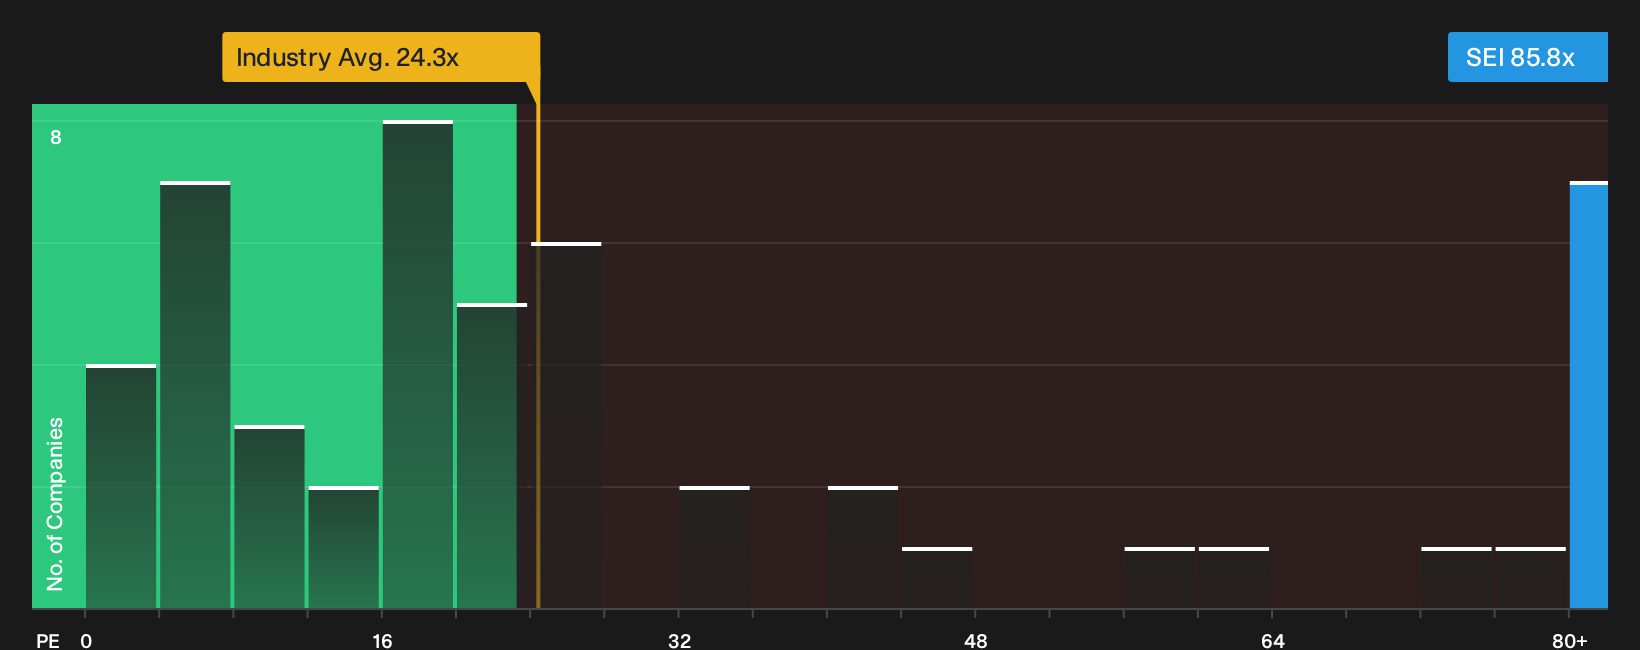
The P/E ratio is a useful shorthand here because Solaris Energy Infrastructure is now being valued squarely on its profit potential. The stock trades on a P/E of about 85.8x, which is more than triple the Energy Services industry average of roughly 24.3x and also well above the peer group closer to 41.0x.
Because the Fair Ratio framework adjusts for Solaris Energy Infrastructure's growth profile, margins, size and risk, the current P/E sitting far above that benchmark points to the shares looking overvalued on this model. The gap is so wide that the Fair Ratio is best read as a warning signal rather than a precise target, since the model is heavily penalising recent losses and the quality of earnings that support the valuation. Despite the upgraded EBITDA outlook around 2026 and 2027, the latest jump in Solaris Energy Infrastructure's share price leaves investors paying a very full earnings multiple for that story. Explore the numbers behind Solaris Energy Infrastructure's P/E valuation.
The Solaris Energy Infrastructure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Solaris Energy Infrastructure pick up where the valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for the shares to look meaningfully higher or lower than today. Rather than focusing on a single multiple or model result, each scenario lays out the assumptions behind its view of fair value so you can compare those expectations with the actual numbers as they are reported. Narratives for Solaris Energy Infrastructure sit on Simply Wall St's Community page, where you can weigh those frameworks against your own expectations for the business.
One of the top community narratives on Solaris Energy Infrastructure: 27% undervalued
"Rising demand for resilient power infrastructure and regulatory support are fueling Solaris's growth and securing longer-term contracts, which is increasing revenue certainty and earnings stability."
Discover why this Narrative puts Solaris Energy Infrastructure at 27% undervalued.
One more angle on Solaris Energy Infrastructure that could change the picture
Valuation only tells part of the story, because the people steering Solaris Energy Infrastructure and the way their pay is structured can heavily influence how future decisions line up with shareholder interests. See who runs Solaris Energy Infrastructure and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com