
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Here's Why We're Watching Protara Therapeutics' (NASDAQ:TARA) Cash Burn Situation
Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
So, the natural question for Protara Therapeutics (NASDAQ:TARA) shareholders is whether they should be concerned by its rate of cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
When Might Protara Therapeutics Run Out Of Money?
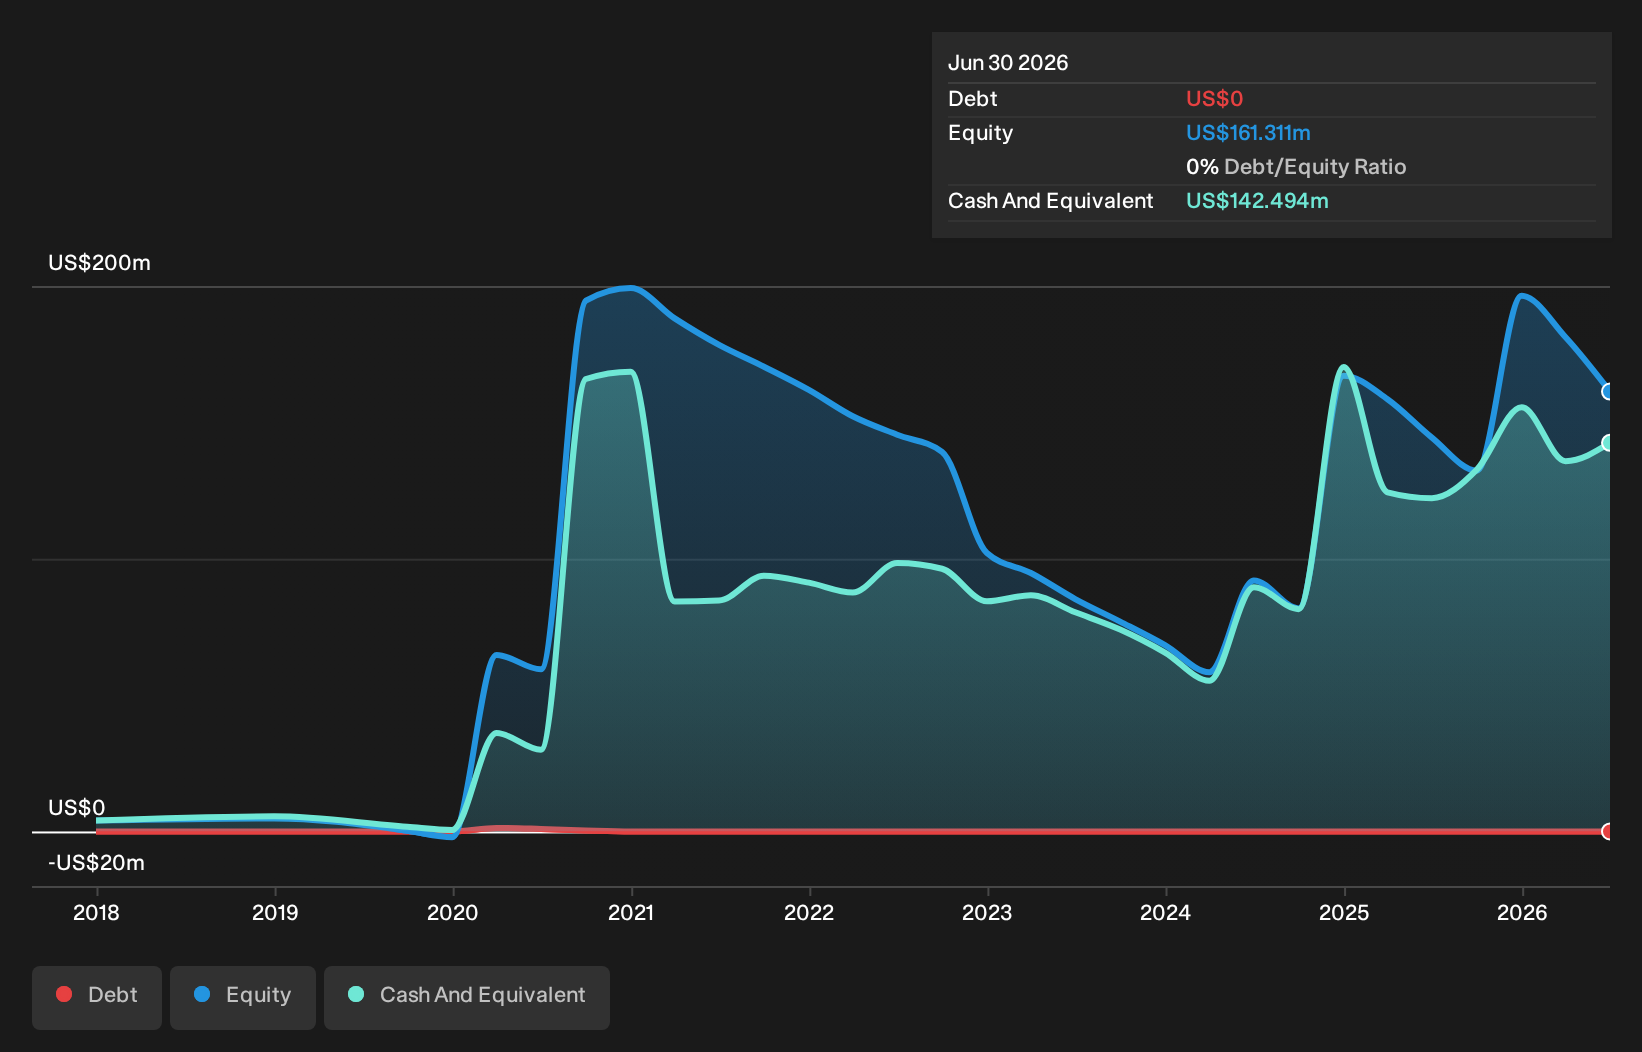
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. In June 2026, Protara Therapeutics had US$142m in cash, and was debt-free. Importantly, its cash burn was US$66m over the trailing twelve months. So it had a cash runway of about 2.1 years from June 2026. Notably, analysts forecast that Protara Therapeutics will break even (at a free cash flow level) in about 3 years. Essentially, that means the company will either reduce its cash burn, or else require more cash. The image below shows how its cash balance has been changing over the last few years.
View our latest analysis for Protara Therapeutics
How Is Protara Therapeutics' Cash Burn Changing Over Time?
Because Protara Therapeutics isn't currently generating revenue, we consider it an early-stage business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. With the cash burn rate up 48% in the last year, it seems that the company is ratcheting up investment in the business over time. However, the company's true cash runway will therefore be shorter than suggested above, if spending continues to increase. While the past is always worth studying, it is the future that matters most of all. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
Can Protara Therapeutics Raise More Cash Easily?
While Protara Therapeutics does have a solid cash runway, its cash burn trajectory may have some shareholders thinking ahead to when the company may need to raise more cash. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Protara Therapeutics has a market capitalisation of US$210m and burnt through US$66m last year, which is 32% of the company's market value. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
How Risky Is Protara Therapeutics' Cash Burn Situation?
Even though its increasing cash burn makes us a little nervous, we are compelled to mention that we thought Protara Therapeutics' cash runway was relatively promising. Shareholders can take heart from the fact that analysts are forecasting it will reach breakeven. Even though we don't think it has a problem with its cash burn, the analysis we've done in this article does suggest that shareholders should give some careful thought to the potential cost of raising more money in the future. Separately, we looked at different risks affecting the company and spotted 3 warning signs for Protara Therapeutics (of which 2 shouldn't be ignored!) you should know about.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.