
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Lender Price Integration Change Radian Group's (RDN) Narrative
- Radian Guaranty Inc. previously announced that its mortgage insurance quotes are now embedded in the Lender Price AI mortgage pricing platform, giving banks, lenders, credit unions, and brokers direct access to RADAR Rates and traditional rate cards from within their existing workflow.
- The move pulls Radian Group’s risk based pricing engine into the heart of loan officers’ daily tools. This may influence how often its mortgage insurance is considered during borrower scenario analysis and may speed up decisions for competing quotes.
- The next area of focus is how Radian Group’s integration of RADAR Rates into Lender Price might shape the broader investment narrative.
Scan Radian Group's move into AI-driven mortgage workflows against a curated list of solid balance sheet and fundamentals (23 results) that could benefit if lenders continue to focus on efficiency and risk control.
What Is Radian Group's Investment Narrative?
To own Radian Group, you need to believe the core mortgage insurance engine can keep throwing off solid cash while the firm gets more deeply wired into lenders’ day to day tools. The Lender Price integration sits squarely in that execution bucket. It embeds RADAR Rates directly into a popular pricing platform, which can tighten workflow, potentially lift quote volume and help defend share without a lot of extra capital.
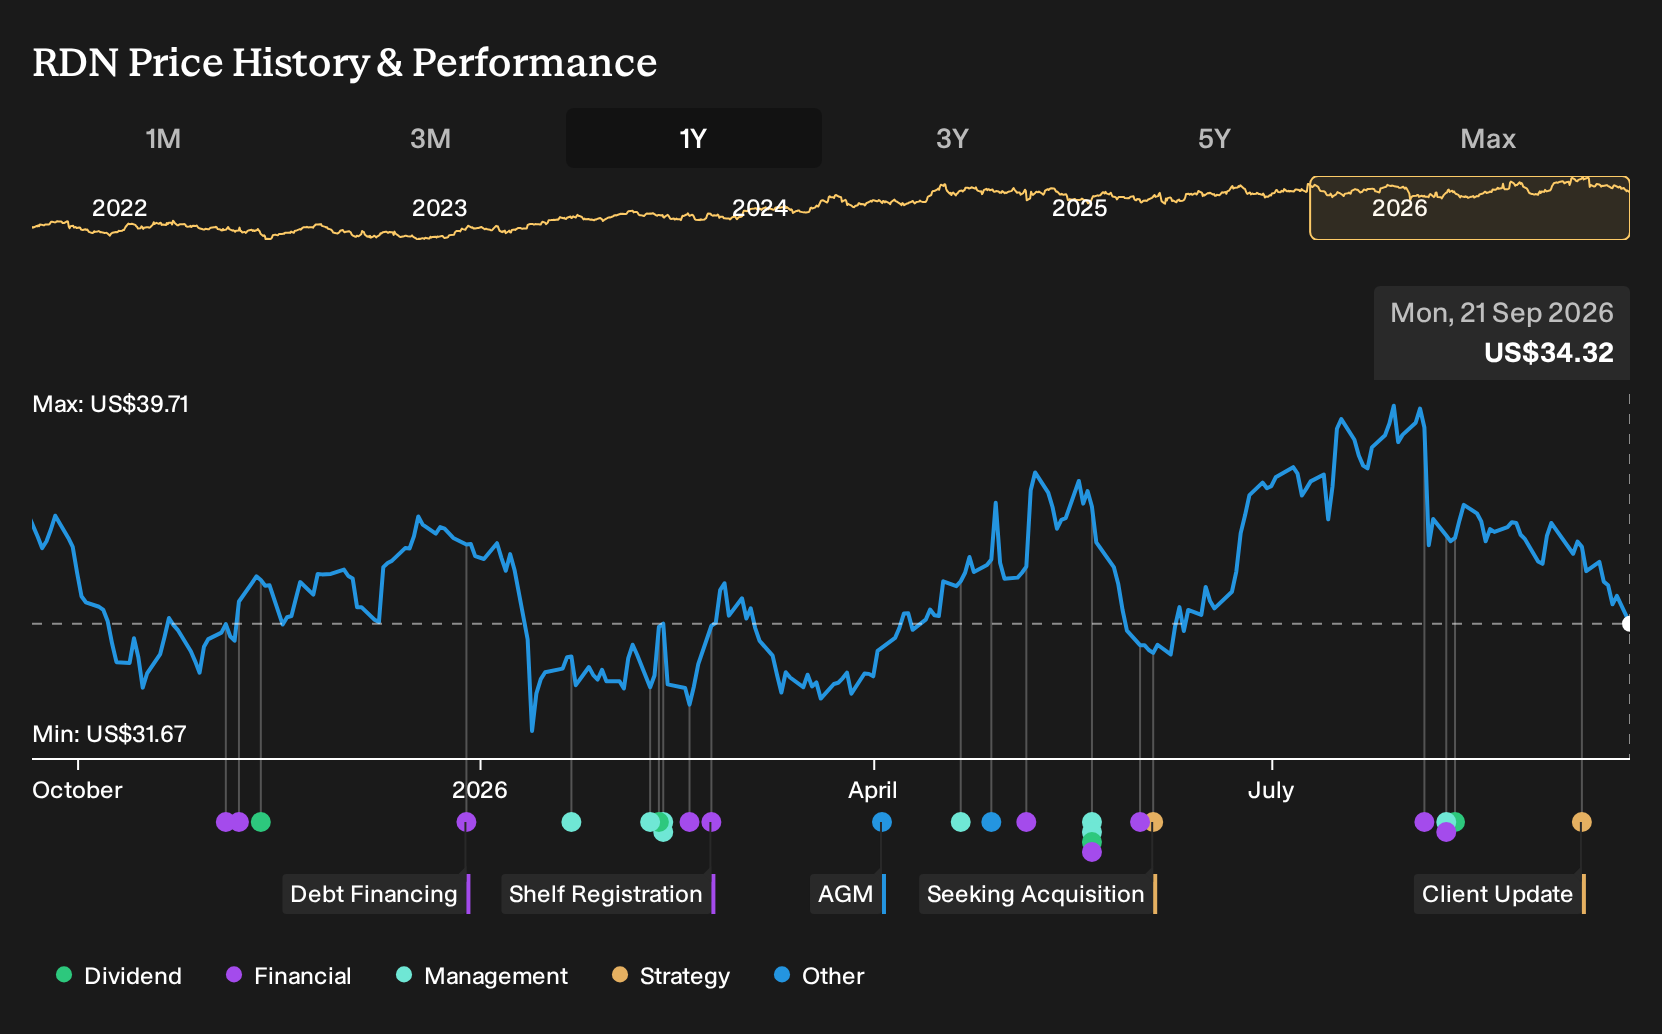
Short term, the more important levers still look like credit performance, pricing discipline and how much capital Radian Group needs to hold against its insured book. Profit margins have already stepped down from 53.1% to 33.9%, and earnings over the past year declined 12.2%, even though revenue and net income recently totaled US$1,649.5m and US$559.3m. The stock screens as good value on an 8.1x P/E, trades below some analyst targets and pays a 2.97% dividend, but those positives only matter if the underwriting and capital story holds.
That said, one issue still hangs over Radian Group that could change how comfortable you feel with those numbers...
There's only one way to know the right time to buy, sell or hold Radian Group. Head to Simply Wall St's company report for the latest analysis of Radian Group's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Radian Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Radian Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Radian Group's overall financial health at a glance.
Looking For More Radian Group Style Investment Ideas?
If you like the mix of cash generation, risk control, and capital discipline that shapes the Radian Group story, it can help to compare it with other companies that share similar financial traits. The Simply Wall St Screener lets you filter for those features directly instead of trawling through tickers one by one.
- For investors who want income with some resilience, take a look at companies that combine higher yields with balance sheet strength through the 7 dividend fortresses.
- If the appeal is owning companies that look cheap relative to their fundamentals, you can focus your search on value opportunities using the 30 high quality undervalued stocks.
- Readers who care most about downside protection can zero in on financially robust businesses by filtering with the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com