
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Defensive Growth Stocks For A Fragile Market Outside Mega Cap Tech
When the Nasdaq jumps 2% to a record while more S&P 500 stocks quietly hit 52 week lows than highs, the story is not just about mega cap tech. It is about a market that looks strong on the surface yet feels fragile underneath, which can matter for quality defensive growth stocks exposed to this news. This article walks through 3 such stocks from our screener that could help you decide where you want portfolio risk to sit on days like these.
The stocks covered below are just a starter set, and the full screen turned up 24 more U.S. large and mid cap defensive or steady growth companies with equally compelling stories that are not discussed in this article. If you want to identify, compare, and analyze your own highest conviction ideas from that broader list, head straight to the Quality Defensive Growth Stocks Outside Mega-Cap Tech screener.
National Beverage (FIZZ)
National Beverage is a consumer staples player anchored in sparkling water, juices, and soft drinks, which fits the screener’s defensive growth theme. It generated about US$1.2b from beverage operations in its latest year, almost all in the U.S., and carries a market value near US$3.0b.
National Beverage offers classic staples exposure through LaCroix and other brands, with steady earnings, strong profitability metrics and ongoing cash returns via special dividends and buybacks. Investors looking for ballast when mega cap tech dominates headlines may appreciate that resilience, although much still hinges on how one unseen pressure shapes margins and volume over the next few years.
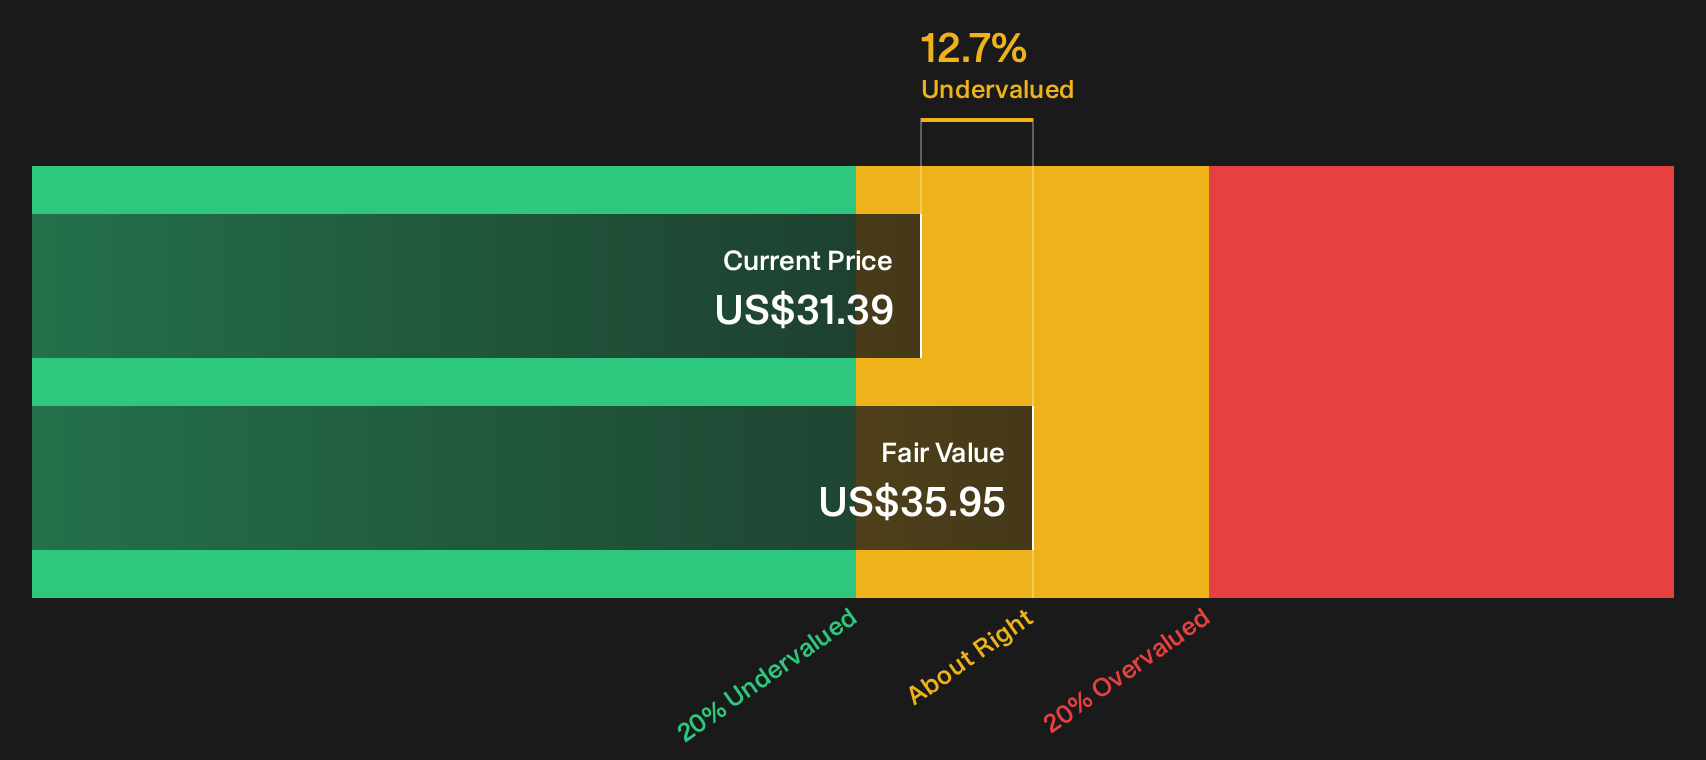
That unseen pressure on margins and volume is exactly what shows up when you run the DCF valuation analysis for National Beverage to see how much cushion the current price leaves.
Allegion (ALLE)
Allegion is a security products specialist that fits the screener’s quality defensive growth theme through locks, access control systems, and software sold into everyday settings like schools, hospitals, offices, and homes. Allegion Americas produces about US$3.4b of revenue and Allegion International about US$921 million, with the group valued near US$12.9b.
Allegion offers a mix of physical locks, electronic access systems, and recurring software and services that can appeal if you want steadier cash flows outside mega cap tech, particularly on days when market breadth looks fragile. High profitability, a long dividend record, and low volatility all support that defensive profile. The key variable to monitor is how its debt load interacts with funding costs over the next few years.
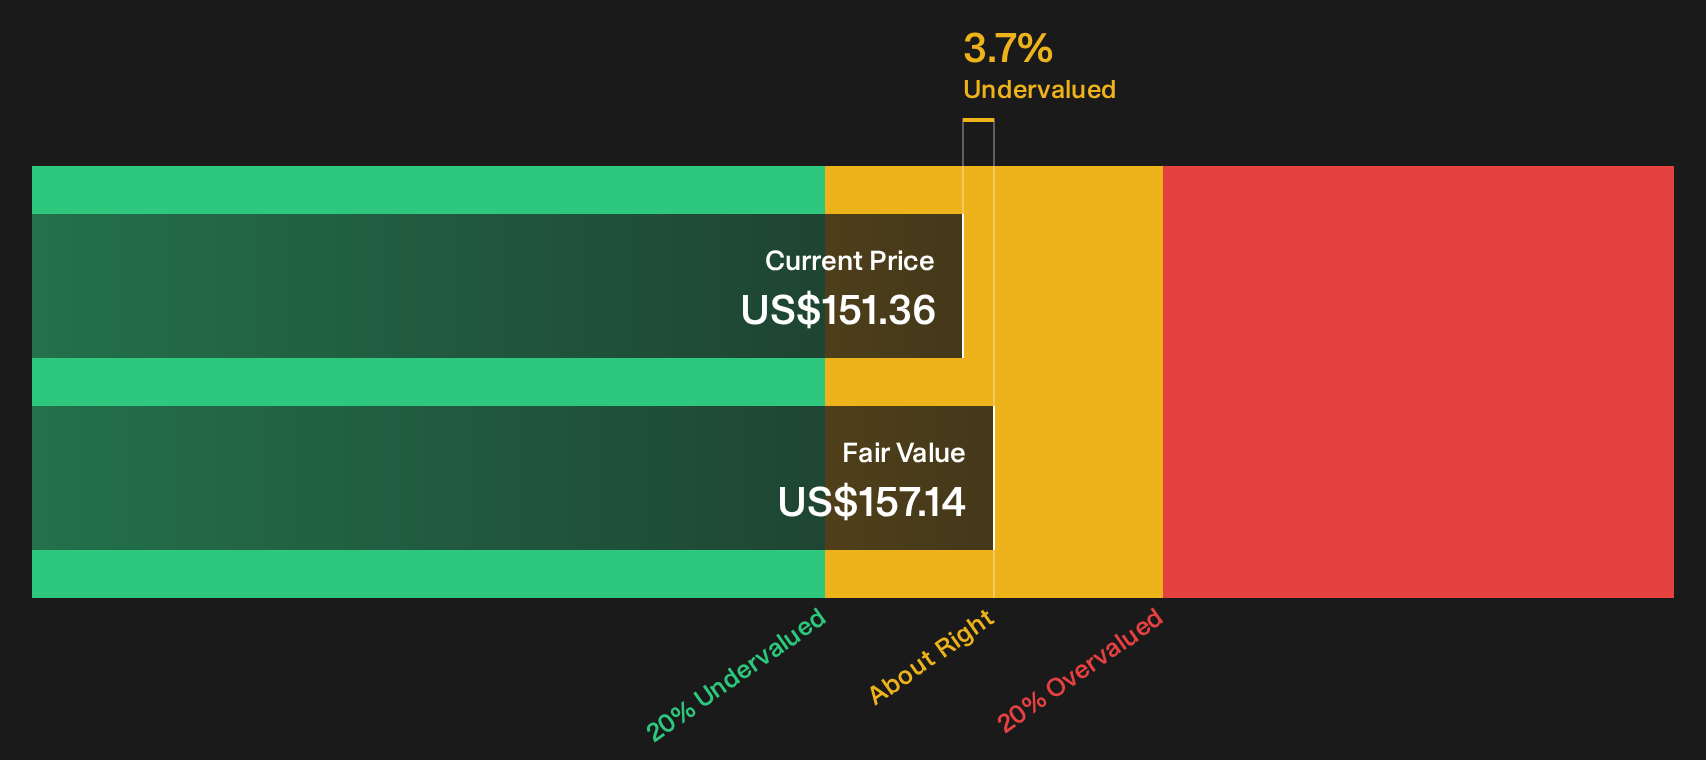
That debt question is where the real story starts, so unpack the 5 key rewards and 2 important warning signs to see how Allegion’s balance sheet and cash generation line up.
Donaldson Company (DCI)
Donaldson Company brings a different kind of defensiveness to this screener, with filtration gear and replacement parts that keep factories, vehicles, and life sciences equipment running. This can matter when market rallies narrow and investors prefer steadier industrial cash flows.
Donaldson Company manufactures filtration systems and parts worldwide, with about US$2.4b from Mobile Solutions, US$1.1b from Industrial Solutions, and US$333 million from Life Sciences, and holds a market value near US$10.0b.
"Global expansion of environmental regulations and emissions standards is increasing demand for advanced filtration across industrial and transportation sectors, positioning Donaldson to achieve record sales in both Industrial Solutions and Mobile Solutions, with a direct positive impact on revenue and earnings growth in FY26 and beyond."
What happens to Donaldson’s steady profile if a single assumption about customer replacement cycles or long-term maintenance spending starts to shift?
When that replacement cycle question starts to nag, the full narrative for Donaldson Company shows how Donaldson Company’s filtration footprint, pricing power, and risk profile could be quietly decoupling from the broader industrial cycle.

Curious About Fresh Market Alternatives?
Some stocks are already building quiet breakout momentum while attention stays glued to mega caps. Fresh prospects can get picked over fast. Before they stop flying under the radar, consider researching potential opportunities soon.
- Spot potential income workhorses early by scanning the curated 7 dividend fortresses that focus on durable payouts when markets feel stretched.
- Track early tech momentum by reviewing carefully filtered 36 AI small caps that connect real AI revenue to business models, not just hype.
- Position ahead of the next infrastructure buildout by checking the focused 40 power grid technology and infrastructure stocks that highlight enablers of grid upgrades and electrification trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com