
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
We Think Poltreg (WSE:PTG) Needs To Drive Business Growth Carefully
Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
Given this risk, we thought we'd take a look at whether Poltreg (WSE:PTG) shareholders should be worried about its cash burn. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
How Long Is Poltreg's Cash Runway?
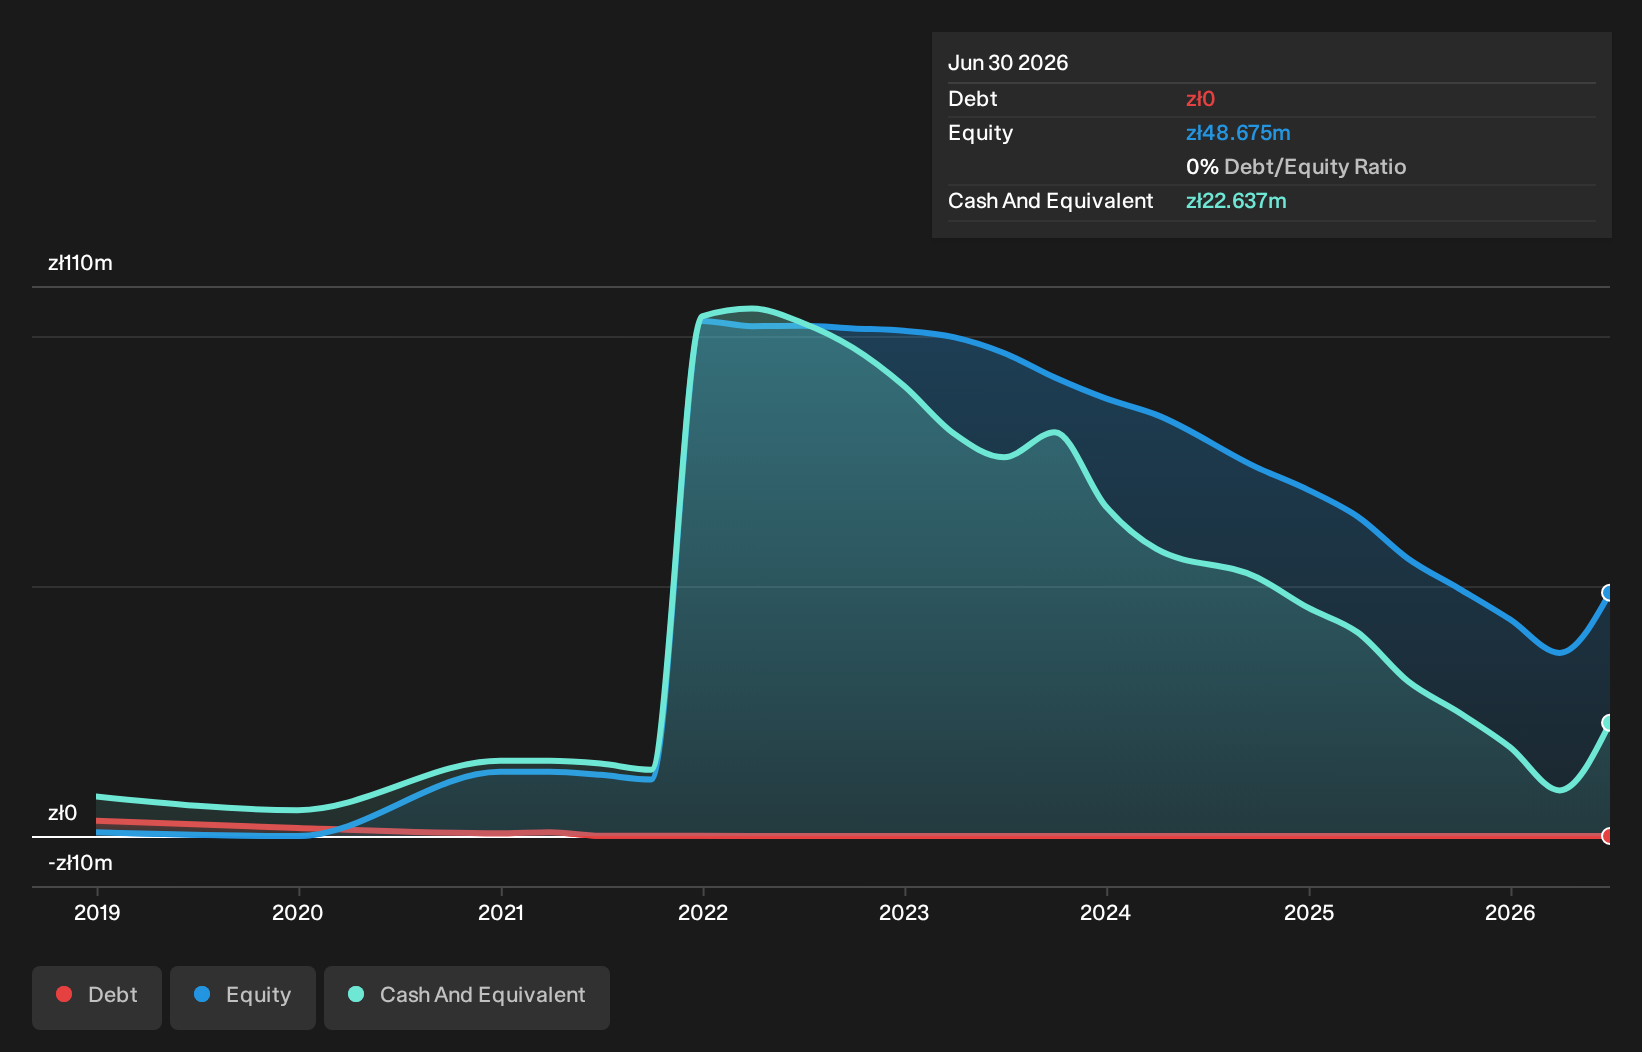
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, Poltreg had zł23m in cash, and was debt-free. Importantly, its cash burn was zł29m over the trailing twelve months. So it had a cash runway of approximately 9 months from June 2026. To be frank, this kind of short runway puts us on edge, as it indicates the company must reduce its cash burn significantly, or else raise cash imminently. Depicted below, you can see how its cash holdings have changed over time.
View our latest analysis for Poltreg
How Is Poltreg's Cash Burn Changing Over Time?
In our view, Poltreg doesn't yet produce significant amounts of operating revenue, since it reported just zł240k in the last twelve months. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. With the cash burn rate up 15% in the last year, it seems that the company is ratcheting up investment in the business over time. However, the company's true cash runway will therefore be shorter than suggested above, if spending continues to increase. Poltreg makes us a little nervous due to its lack of substantial operating revenue. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
How Easily Can Poltreg Raise Cash?
Since its cash burn is moving in the wrong direction, Poltreg shareholders may wish to think ahead to when the company may need to raise more cash. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Poltreg has a market capitalisation of zł121m and burnt through zł29m last year, which is 24% of the company's market value. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
How Risky Is Poltreg's Cash Burn Situation?
We must admit that we don't think Poltreg is in a very strong position, when it comes to its cash burn. Although we can understand if some shareholders find its cash burn relative to its market cap acceptable, we can't ignore the fact that we consider its cash runway to be downright troublesome. Summing up, we think the Poltreg's cash burn is a risk, based on the factors we mentioned in this article. Separately, we looked at different risks affecting the company and spotted 6 warning signs for Poltreg (of which 3 are a bit unpleasant!) you should know about.
Of course Poltreg may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.