
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Stocks With P E Up To 29
Talks between the US and China on artificial intelligence put a spotlight on where the real economic muscle is forming. Governments are treating AI like critical infrastructure, not just another tech trend. That level of attention can re-rate entire corners of the market, particularly stocks that appear inexpensive relative to their role in chips, software and cloud services. This article walks through three AI-related companies from our screener that currently screen as undervalued and may merit a closer look.
The three stocks in this article are just a starting sample from our undervalued AI list. The full screen surfaced 44 more companies with equally compelling narratives across chips, software, cloud and large language models that are not covered here.
To identify and analyze the highest conviction AI opportunities, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener
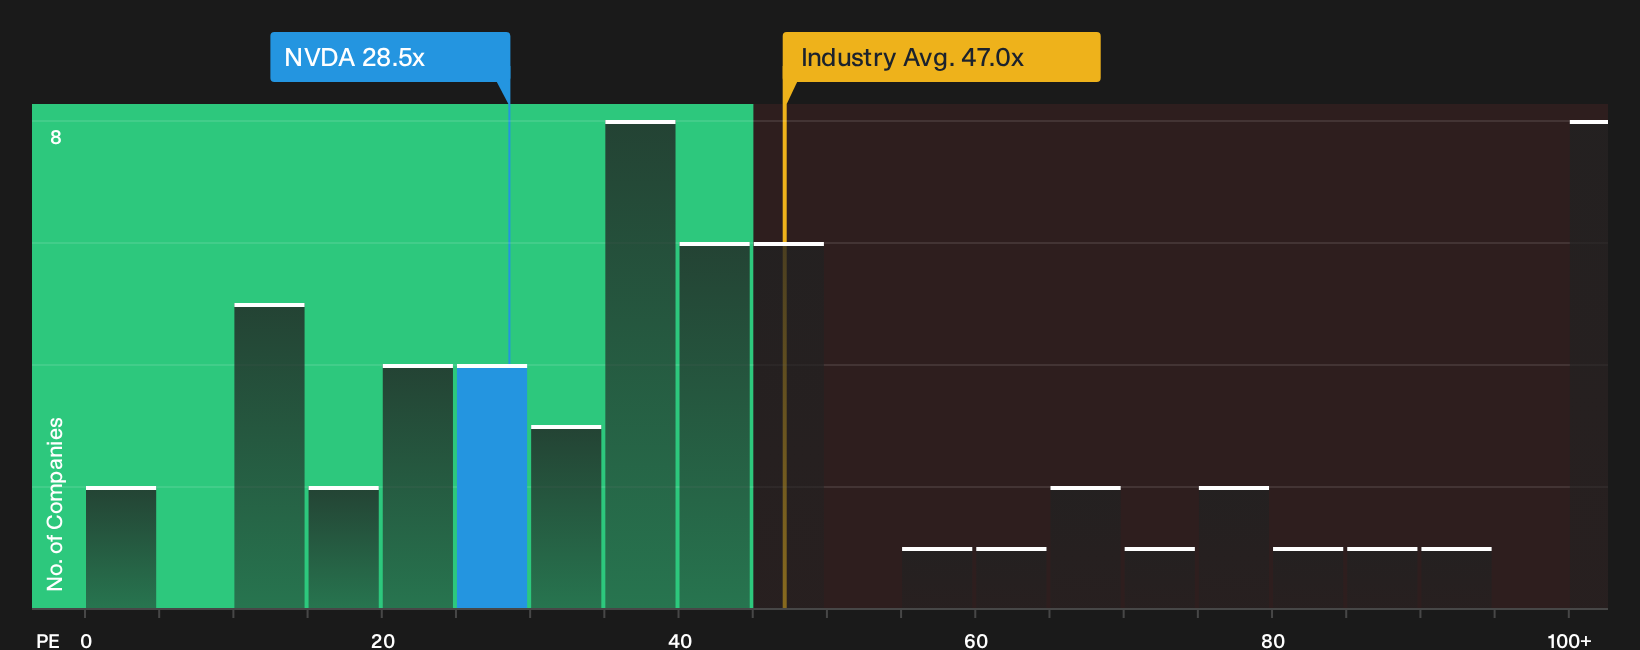
NVIDIA (NVDA)
Overview: NVIDIA is a global chip and software company that supplies GPU hardware and AI platforms powering data centers, gaming, and automotive uses.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, with revenue concentrated in the United States and Taiwan.
Market Cap: US$5,367.2b
NVIDIA matters for this AI screener because its data-center GPUs and software stack are a primary engine behind modern ChatGPT-style models and cloud AI infrastructure.
"Uptake of an open-source/cheaper/better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products (similar to what Apple did with its M-Series chips)"
What happens to NVIDIA’s AI story if a single core assumption about long-term pricing power in its ecosystem eventually breaks?
If that pricing power question sits at the center of your thesis, read the full narrative for NVIDIA to see how NVIDIA’s moat could evolve from here.
Adobe (ADBE)
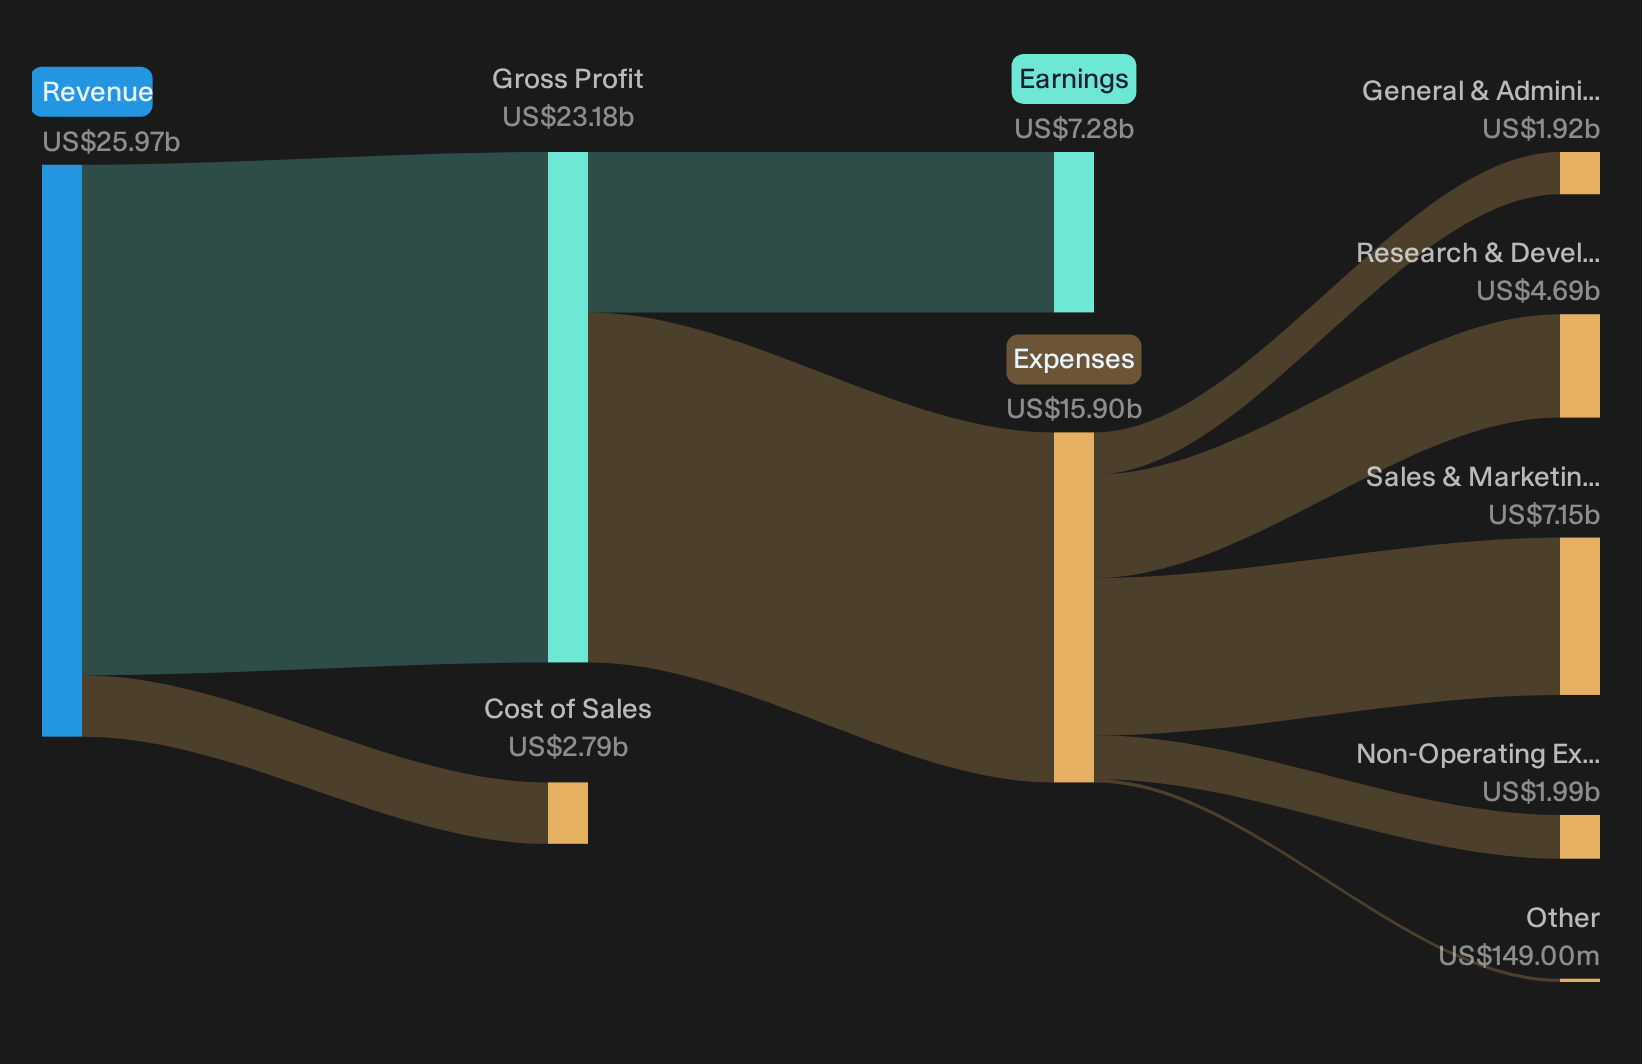
Overview: Adobe is a global software provider that powers creative tools and enterprise customer experience platforms, now weaving generative AI like Firefly directly into its Creative Cloud and Experience Cloud workflows.
Market Cap: US$98.9b
For this AI screen, Adobe matters because it plugs generative tools directly into the creative and marketing software professionals already rely on, turning the ChatGPT era into everyday workflow rather than a separate experiment.
"If Adobe can maintain its ~45% non-GAAP operating margin while scaling its GPU infrastructure, it will prove the scalability of its AI model."
What happens to Adobe’s AI story if one quiet assumption about how much customers will pay for that embedded automation eventually shifts?
That pricing shift could reshape how Adobe monetizes AI across its ecosystem, so read the full narrative for Adobe to see where that thesis accelerates or stalls next.
Alphabet (GOOGL)
Overview: Alphabet is a global technology group whose Google Cloud, Vertex AI and Gemini platforms supply core infrastructure for enterprise generative AI.
Operations: Alphabet generates about US$367.1b from Google Services and US$77.6b from Google Cloud, with revenue concentrated in the United States and EMEA.
Market Cap: US$4,246.5b
Alphabet matters for this AI-focused screen because Google Cloud’s Vertex AI and Gemini tools give enterprises a way to build ChatGPT-style services directly on its infrastructure, while the larger ads and consumer platforms give that AI push a deep funding base.
"Google Cloud has gone from “meh” to money-maker; as of 2023, Cloud turned operating profitable, and that momentum continues."
What happens to Alphabet’s AI economics if one quiet assumption about how quickly enterprise Gemini workloads scale across that backlog proves too optimistic?
If that workload risk sits in the back of your mind, read the full narrative for Alphabet to see whether Alphabet’s AI flywheel is quietly accelerating or stalling.

Seeking Alternatives Before They Fly Past
Fresh ideas move first, prices move next. Screen for potential breakouts while momentum is still building, before the crowd catches on and information goes stale.
- Hunt for potential high-upside outliers hiding in plain sight with the curated 17 high quality undiscovered gems that remain under the radar for now.
- Spot potential cash-rich opportunities by scanning the curated 7 dividend fortresses before yields get compressed.
- Target potential resilient compounders that may hold up when others wobble by working through the focused 30 resilient stocks with low risk scores while it still matters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com