
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
HKBN (SEHK:1310) Names A New Chair, Is The Stock Cheap?
Leadership change at HKBN
HKBN (SEHK:1310) just announced a major boardroom reshuffle, with long serving chairman Ling Hao stepping down and China Mobile Hong Kong chief executive Shi Xiaoping taking over as executive director and board chair.
The appointment places an experienced telecommunications operator at the top of a regional fibre, mobile, and enterprise services provider that already sits within the wider China Mobile Hong Kong corporate orbit.
Recent trading tells a mixed story for HKBN. The share price has slipped about 8.6% over the past month and 11.8% year to date, yet the 3 year total shareholder return of roughly 111%, alongside a weaker 1 year total shareholder return of about 10.8%, suggests longer term holders have seen strong gains. However, momentum has cooled recently as investors reassess future direction under new leadership.
Scan for other telecom plays undergoing leadership or strategic shifts by checking the hand-picked 616 high quality undiscovered gems that may be flying under most investors' radar.
So is HKBN’s recent share price slide a verdict on the fundamentals, or just sentiment resetting as a new China Mobile Hong Kong insider takes the chair and the market weighs what that means for value today?
Most popular HKBN valuation narrative: 24.5% undervalued
On the numbers, the most followed HKBN narrative pins fair value at HK$7.30 per share, compared with a last close of HK$5.51. The story centers on whether the gap reflects mispricing or genuine risk around execution and balance sheet pressure at a telecom and technology services group tightly linked to China Mobile Hong Kong.
The bundling of telecom services with the ICT/System Integration business allows HKBN to increase customer loyalty and upsell, thereby increasing average revenue per user (ARPU) and enhancing profitability.
See why 1 investors see HKBN as 25% undervalued.
On this view, analysts apply an 8.16% discount rate and assume long term revenue growth of about 1.72% with net profit margins reaching roughly 10.53%. Together, these assumptions support that HK$7.30 figure and imply HKBN is trading at about a 24.5% discount to this narrative fair value.
The same storyline leans on forecasts that annual earnings growth of roughly 43.8% outpaces the wider Hong Kong market, even though top line expansion is expected to remain modest at around 1.7% a year and below broader market revenue growth assumptions.
Investors weighing this thesis against the recent leadership overhaul and relatively short tenures across both management and the board will likely pay close attention to how quickly HKBN converts its broadband, ICT, and cybersecurity offerings into more stable margins and stronger coverage of interest and dividends from underlying profits.
Result: Fair Value of HK$7.30 (UNDERVALUED)
Still, HKBN’s reliance on Mainland China vendor partnerships and its shift away from reselling leave the narrative exposed if revenue or cash generation fall short of expectations.
Find out about the key risks to this HKBN narrative.
Another view on HKBN valuation
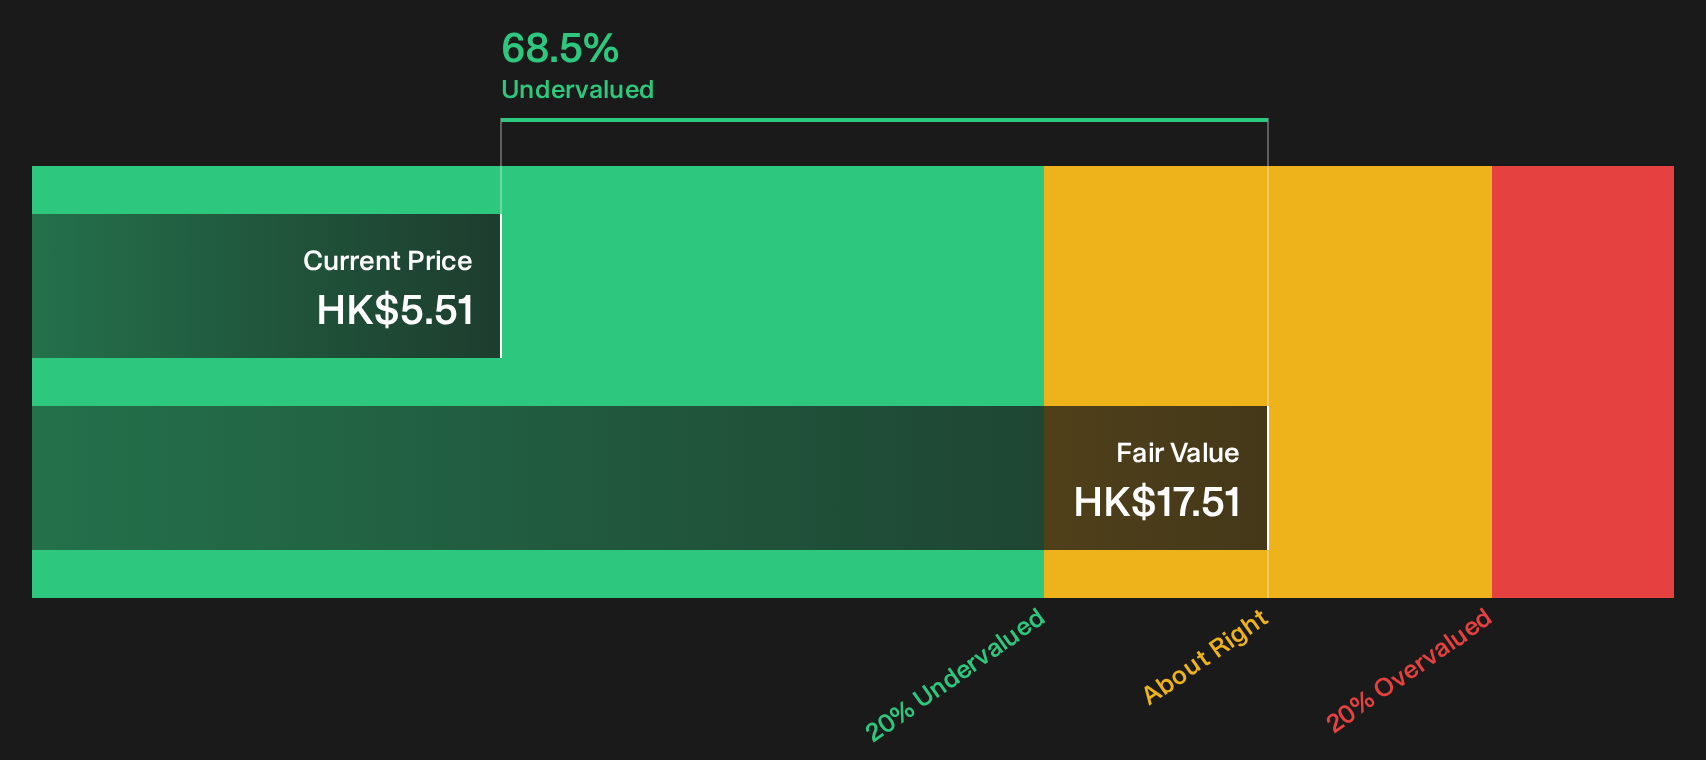
HKBN may look inexpensive compared with the HK$7.30 narrative fair value and the estimate of HK$17.51 from the SWS DCF model, which indicates the shares are trading 68.5% below that future cash flow value. The question is whether those cash flow assumptions are realistic or simply too generous for current conditions.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
The mix of optimism and concern around HKBN is clear, so move quickly, review the underlying data carefully, and shape your own stance by weighing the 3 key rewards and 3 important warning signs.
Looking for more HKBN investment ideas?
If HKBN has you thinking harder about where to put fresh capital next, do not leave your watchlist half built. Line up a few more contenders using focused screeners that surface specific types of opportunities you might otherwise miss.
- Target potential upside by scanning for quality companies trading below estimated value with the 174 high quality undervalued stocks.
- Lock in income potential by hunting for reliable payers through the 162 dividend fortresses.
- Dial back risk and focus on resilience by filtering for steadier candidates using the 229 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com