
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Shanghai Conant Optical (SEHK:2276) Rebounds After Interim Dividend Approval, But Does Valuation Still Look Rich?
Dividend approval and what it means for Shanghai Conant Optical shareholders
Shanghai Conant Optical (SEHK:2276) has approved an interim dividend of RMB 0.20 per share for the first half of 2026, equivalent to HK$0.232, with payment expected by 23 October 2026.
Recent trading suggests momentum in Shanghai Conant Optical is rebuilding, with a 1-day share price return of 8.23% to HK$43.92 and a 90-day share price return of 24.70%. This comes even though the year-to-date share price return is still down 18.82% and the 1-year total shareholder return has slipped 1.81%. These moves are set against a very large 3-year total shareholder return above 6x that may indicate how investors have been reassessing both growth potential and risk over time.
Scan how Shanghai Conant Optical's rebound compares to other potential opportunities in our hand picked list of 174 high quality undervalued stocks.
Shanghai Conant Optical has already delivered a very large 3 year return, yet the recent pullback and only partial price recovery leave a real tension. Has most of the upside already played out, or is the valuation still leaving room?
Price-to-earnings of 30.9x for Shanghai Conant Optical: Is it justified?
On simple multiples, Shanghai Conant Optical trades on a P/E of 30.9x at a last close of HK$43.92, which looks demanding against peers and the wider Hong Kong Medical Equipment sector.
The P/E ratio compares the current share price with earnings per share. For a business like Shanghai Conant Optical, which manufactures and sells spectacle lenses across several regions, this metric gives you a quick read on how much investors are willing to pay for each unit of current profit.
There is a clear gap between price and fundamentals when you line that 30.9x up against other benchmarks. The peer average sits at 14.6x. The Hong Kong Medical Equipment industry average is 17x. The internal fair P/E estimate is 20.5x, a level the market could move toward if sentiment or earnings expectations change.
Explore the SWS fair ratio for Shanghai Conant Optical.
Result: Price-to-earnings of 30.9x (OVERVALUED)
Still, Shanghai Conant Optical faces real pressure if earnings growth slows or if investors turn away from Medical Equipment stocks with higher multiples.
Find out about the key risks to this Shanghai Conant Optical narrative.
Another view on Shanghai Conant Optical's value
The P/E screen paints Shanghai Conant Optical as expensive, yet the SWS DCF model tells a softer story. At HK$43.92 the share price sits about 2.2% below an estimated fair value of HK$44.90. That is a small discount. Is it enough to justify today’s richer earnings multiple?
Look into how the SWS DCF model arrives at its fair value.
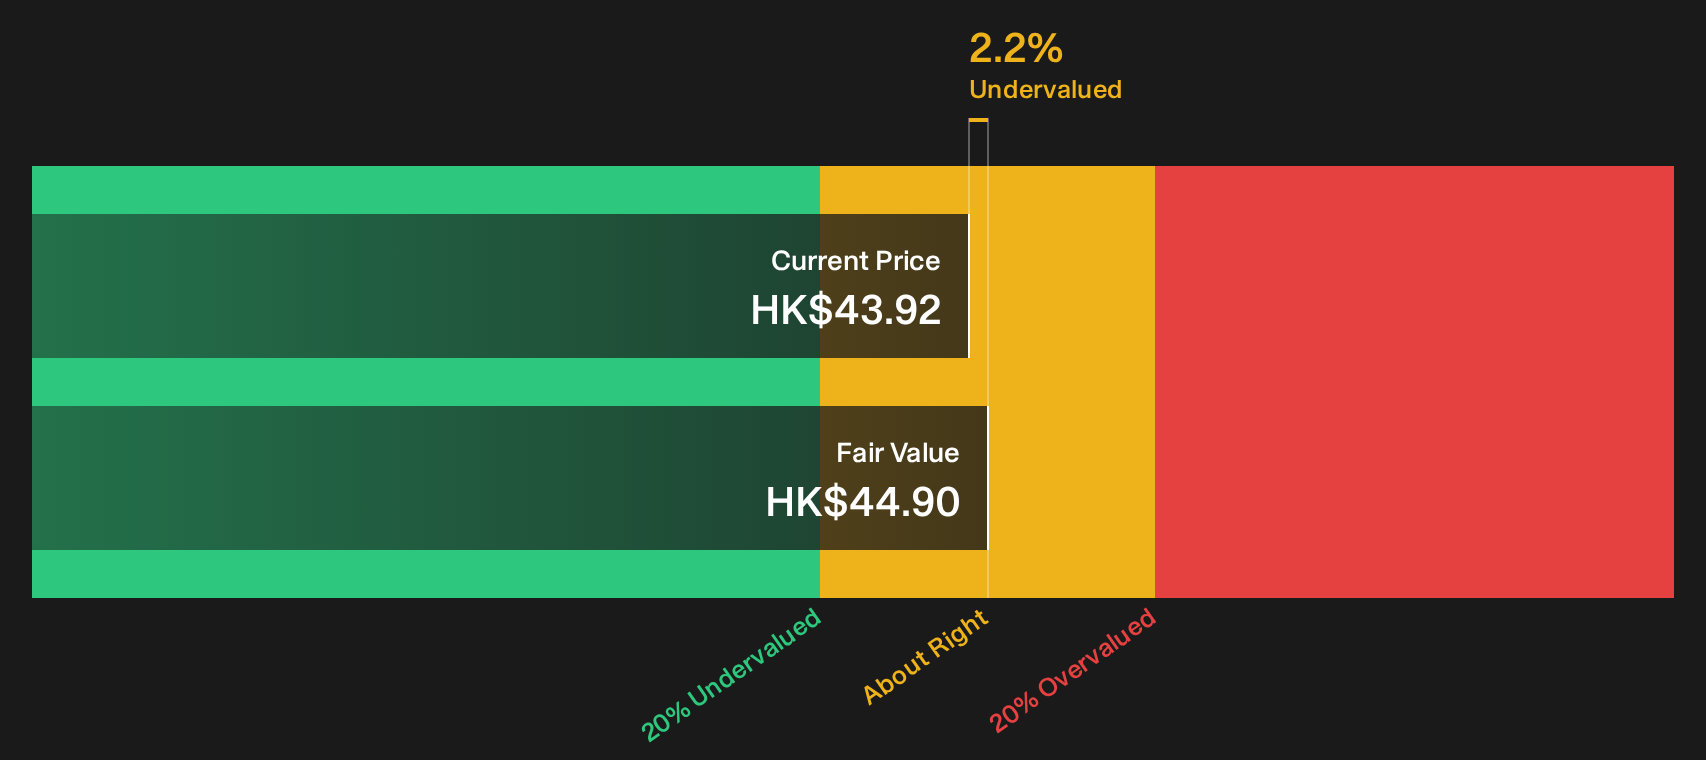
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shanghai Conant Optical for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment around Shanghai Conant Optical feels divided, that is the point; you need to review the numbers yourself and decide quickly where you stand. To see what optimism in the data looks like in practice, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Shanghai Conant Optical?
If Shanghai Conant Optical has your attention, do not stop here. The next step is widening your watchlist with focused stock ideas tailored to different goals.
- Target stability first and let potential returns build on top by checking a 229 resilient stocks with low risk scores. This screener filters for resilience when markets feel uncertain.
- Hunt for quality at a discount and see which companies currently appear mispriced through the 174 high quality undervalued stocks. This tool highlights strong fundamentals at lower prices.
- Spot potential future market favourites early by scanning the 616 high quality undiscovered gems and tracking businesses that have solid numbers but limited attention today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com