
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To AtkinsRéalis Group (TSX:ATRL) Pickering Nuclear Contract Win
- Aecon Group announced that its long-standing joint venture with AtkinsRéalis and a consortium with Siemens Energy secured Ontario Power Generation contracts related to the Pickering Nuclear Generating Station refurbishment, with an aggregate value of $3b and work expected to support long-term clean energy needs in Ontario.
- Candu Energy, an AtkinsRéalis subsidiary, in joint venture with Aecon, signed a three-year $1.7b contract for Pickering Unit 5 life-extension work. This adds to AtkinsRéalis' Nuclear backlog and highlights the operational weight of large, phased refurbishment programs in its project pipeline.
- We will now look at how AtkinsRéalis' investment narrative could be shaped by this large Pickering nuclear refurbishment win with Ontario Power Generation.
AtkinsRéalis Group Investment Narrative Recap
To own AtkinsRéalis Group, you need to believe that high value engineering and nuclear services can offset weaker pockets in traditional construction and lumpier regions like USLA and EMEA. The near term story still revolves around turning a record backlog into steadier earnings, while dealing with compressed net margins at 3.7% and recent one off charges.
The Pickering win adds contracted work to an already large nuclear book, but does not suddenly remove the key swing factors. Execution on complex, long cycle nuclear projects remains the most important short term catalyst, and project delay or cost overrun risk is still the biggest operational concern.
The three year, CA$1.7b Candu Energy and Aecon contract tied to Pickering Unit 5 matters most for this story. It directly feeds AtkinsRéalis Group's nuclear backlog and reinforces the role of life extension programs in supporting future revenue visibility in that segment.
For investors, the key question is whether management can deliver this refurbishment phase on time and on budget while margins recover from recent pressure. Strong execution here would help validate nuclear as a durable growth driver. Weak delivery would add weight to existing worries about fixed price exposure, earnings volatility and concentration in a few very large projects.
What The Forecasts Assume For AtkinsRéalis Group
AtkinsRéalis Group sits at an interesting crossroads. Analysts expect the business to keep lifting its top line even as profitability retreats from current levels. That mix matters if you are trying to weigh a large nuclear refurbishment win like Pickering against the rest of the portfolio.
The current analyst framework assumes roughly 6.5% yearly revenue growth over the next three years. Within that, earnings today are quoted at about CA$2.7b, with consensus forecasts pointing to CA$898.7m by 2029. That implies earnings would fall by around CA$1.8b from current levels, even as the Pickering contract and other long cycle nuclear work feed into the backlog.
Those projections also rely on a material reset in profitability. Analysts see profit margins moving from 23.2% today to 6.5% in three years. For investors, that sets a clear hurdle. The story only really works if the shift toward higher value engineering and nuclear services can eventually support returns that justify taking margin compression upfront.
The valuation piece ties those operating assumptions to the current share price. To line up with consensus, you would need to accept that by 2029 AtkinsRéalis Group could be generating CA$13.8b in revenue and CA$898.7m in earnings, while the market pays a P/E of 24.7x on those projected profits. That compares with a P/E of 5.5x on present earnings and sits slightly above the current P/E for the Canadian construction peer group at 24.1x.
In practice, this means the forecast relies more on a re rating of the multiple than on earnings expansion. Analysts also flag an expected 1.96% annual decline in share count over the next three years, which slightly lifts per share numbers if it plays out. The discount rate used in the Simply Wall St model is 8.2%, which anchors the present value of those 2029 outcomes.
If you compare this to the Pickering refurbishment narrative, it provides a useful framing tool. The contract win adds long duration work, yet the consensus path still bakes in lower earnings and thinner margins. That gap between strong order book visibility and weaker profit forecasts is where the core investment debate around AtkinsRéalis Group sits today.
AtkinsRéalis Group's narrative projects CA$13.8b revenue and CA$898.7m earnings by 2029. This requires 6.5% yearly revenue growth and an earnings decrease of about CA$1.8b from CA$2.7b today.
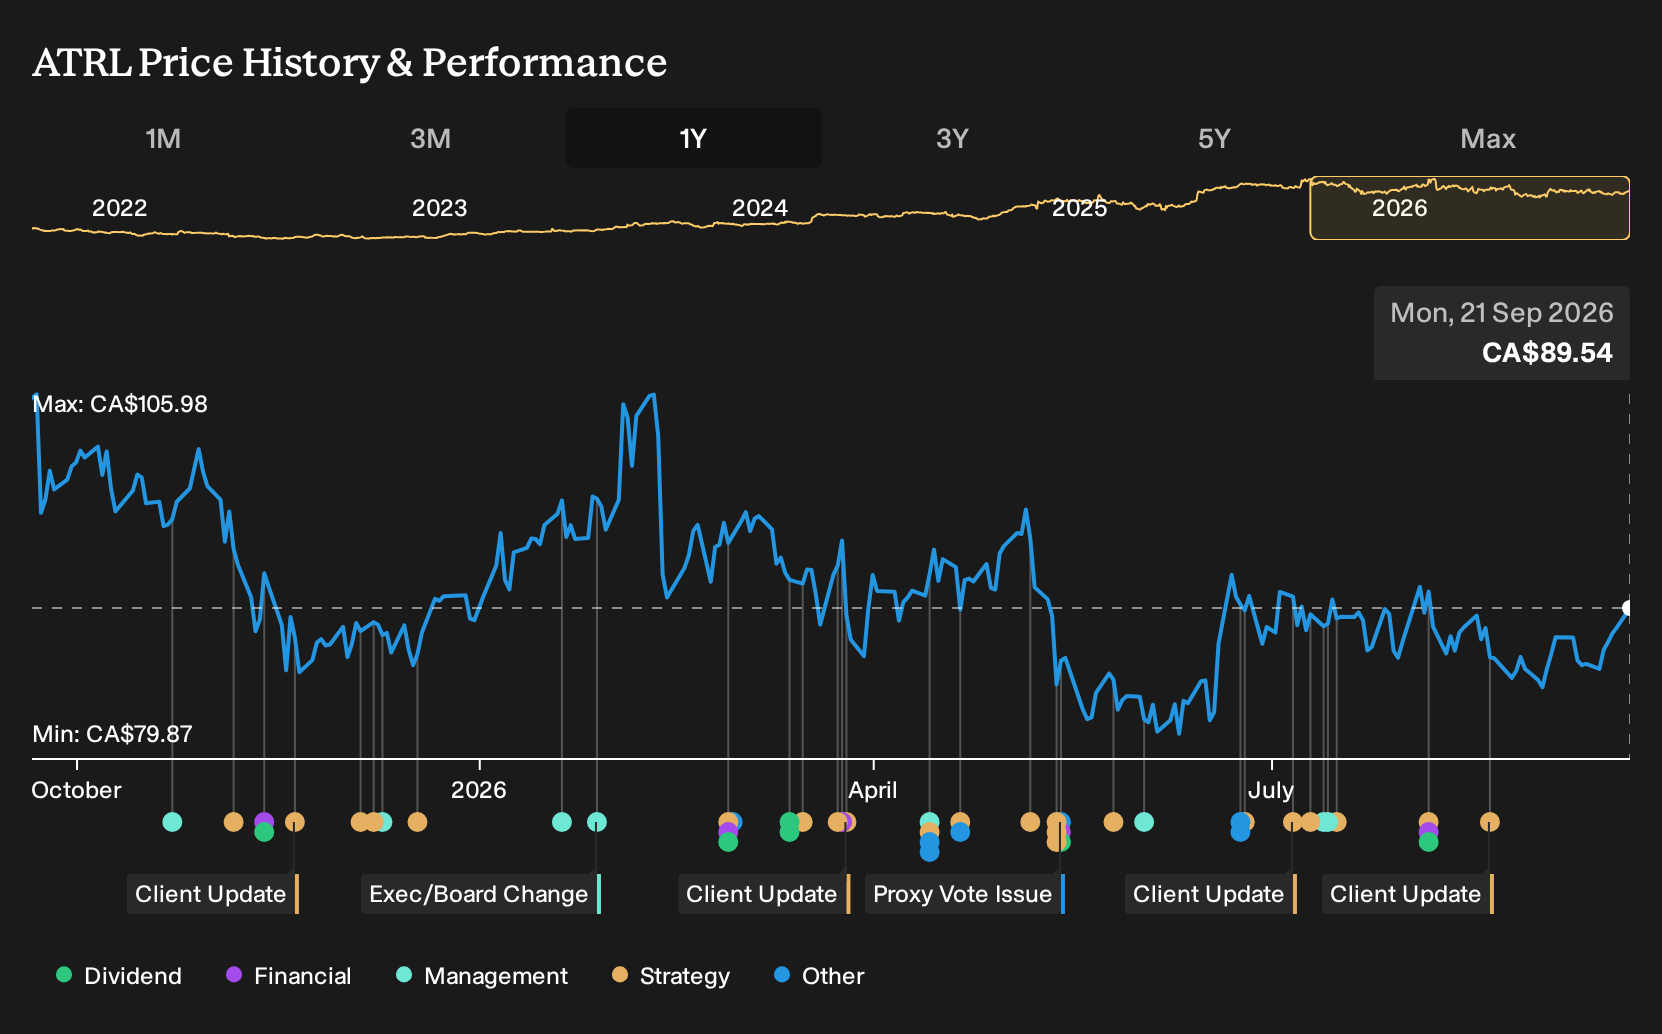
Uncover why AtkinsRéalis Group's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster in a tight CA$109.18 to CA$117.29 band, yet each retail forecaster builds a different story about AtkinsRéalis Group. Those models were set before the Pickering contracts, so execution risk in USLA and EMEA, plus nuclear concentration, could influence how you and others reassess the upside. It may be helpful to explore those alternative views before anchoring on one narrative.
Explore 3 other AtkinsRéalis Group fair value estimates, including one that suggests as much as 31% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AtkinsRéalis Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AtkinsRéalis Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AtkinsRéalis Group's overall financial health at a glance.
Looking for more investment ideas beyond AtkinsRéalis Group?
If the AtkinsRéalis Group story has you thinking about where long-term capital might work harder, it can help to scan a wider field of opportunities using the Simply Wall St Screener.
- For investors who want potential upside at a lower entry price, scan 20 elite penny stocks with strong financials that still carry solid financial profiles and clear business models.
- If capital preservation and balance sheet strength sit at the top of your checklist, focus on the list of solid balance sheet and fundamentals (7 results) to see which companies pair financial resilience with dependable fundamentals.
- When the goal is to combine quality with mispricing, use the 6 high quality undervalued stocks to find businesses the market may not be fully pricing in yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com