
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
China Index Research Institute: The popularity of local auctions continues to decline, and intensive land auctions will be welcomed in late September
The Zhitong Finance App learned that according to data from the China Index Research Institute, in the third week after the New Deal (9.14-9.20), 300 cities planned to build 7.31 million square meters of residential land, land concessions of 19.3 billion yuan, continued to decline; the average premium rate was 3.7%, and high-premium plots continued to decline. There were premium residential land transactions in Zhengzhou, Hangzhou, Tianjin, and Fuzhou this week, but housing companies' bids became more rational, and the land acquisition logic further focused on location certainty, total price controllability, and space for subsequent product operation. Among them, the Mingrenli plot in the 27th district of Zhengzhou was contested by the local housing company Zhenghong Real Estate for 1,218 billion yuan, with a premium rate of 32.67%. At the end of the month, core cities will host intensive land auctions. According to monitoring by the Central Index, in late September, key Tier 1 and 2 cities will be auctioned for more than 90 residential lots, starting at about 76 billion yuan. Shanghai's Jing'an, Hongkou North Bund, Beijing's Fengtai Yuezhuang, Beijing, and Yuzhu and Pazhou in Guangzhou will focus on auctions.
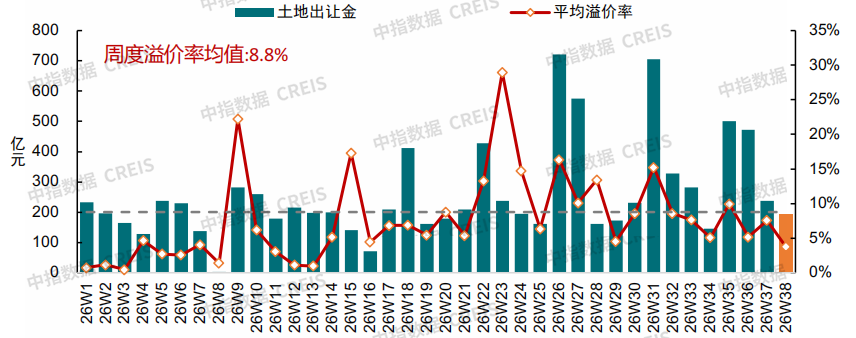
In the third week after the New Deal, land concession funds in 300 cities continued to decline, with an average premium rate of 3.7%
Figure: Trends in weekly residential land concessions and average premium rates in 300 cities
Data source: Middle Index Data CREIS
According to China Index data, in the third week after the implementation of the 8.28 New Deal (9.14-9.20), 300 cities had a planned construction area of 7.31 million square meters, land concessions of 19.3 billion yuan, and concession funds continued to decline; the average premium rate was 3.7%. Only some high-quality land plots in Hangzhou, Zhengzhou, and Tianjin were active in the local auction market this week.
Since September (9.1-9.20), residential land in 300 cities has sold 20.52 million square meters, with a concession of 70 billion yuan. According to monitoring by the China Index, from September 21 to 30, the planned construction area of residential land in 300 cities is about 21 million square meters, with a starting price of about 110 billion yuan. In late September, several core cities will host a land shooting campaign.
Location, total price, and product space are currently the definitive measures for real estate companies to acquire land
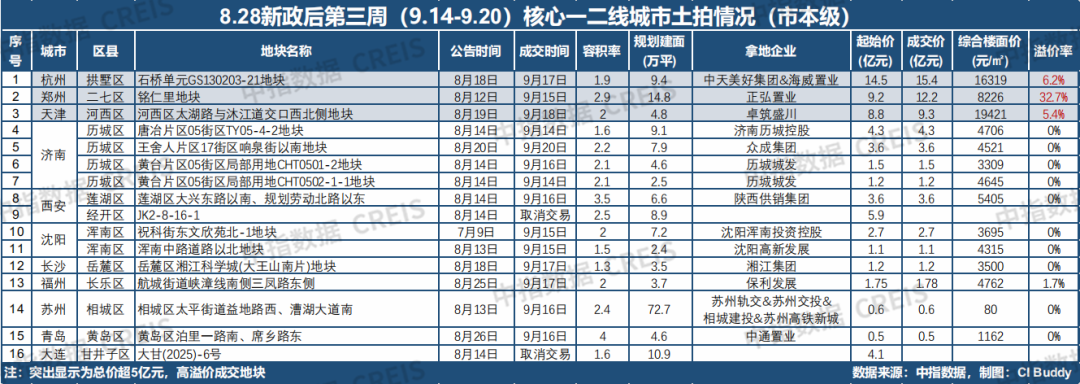
Looking at key cities, the overall land market remained lackluster in the third week after the New Deal, with premium transactions concentrated on a few plots with better conditions. Compared with high-premium transactions for individual plots in the first half of the month, housing companies' bids have become more cautious this week, and the popularity of land plots and premium rates have declined somewhat. Looking at premium land, corporate investment judgments further focus on the demand base, land price level, total price scale, and subsequent transaction risk. High-quality land can still compete, but the willingness to pursue land at high prices has weakened.
This week, the Mingrenli plot in the Erqi District of Zhengzhou was relatively popular. Zhenghong Real Estate competed with 1.22 billion yuan and a 32.7% premium rate, and the floor price was 8,226 yuan/㎡. The plot has a planned construction area of about 148,000 square meters, and the transaction floor price is relatively low, reserving a certain amount of space for subsequent product positioning, apartment layout and price strategy of the project.
The land plot in Hexi District of Tianjin was sold for 930 million yuan, with a floor price of 19,421 yuan/㎡ and a premium rate of 5.4%. The sector where the plot is located has a certain basis for improved demand. The total price is less than 1 billion yuan, and the capital consumption is relatively manageable, thus attracting housing enterprises to participate in the auction, but in the end, the premium rate is low.
Housing enterprises are also reducing investment risks through cooperative land acquisition and controlling land acquisition costs. The Shiqiao unit plot in Gongshu District of Hangzhou was jointly contested by Zhongtian Meimei Group and Haiwei Real Estate at a premium rate of 1.54 billion yuan and 6.2%. In an environment where total prices are high and where decentralization is still fragmented, joint land acquisition helps share capital investment and development risks. It also shows that private housing enterprises pay more attention to cash flow safety and resource coordination when returning to core cities. Poly Development, on the other hand, competed for land in Changle District of Fuzhou for 178 million yuan, with a premium rate of only 1.7%, which is closer to supplementing peripheral sector project reserves at a lower cost.
Typical plot conditions
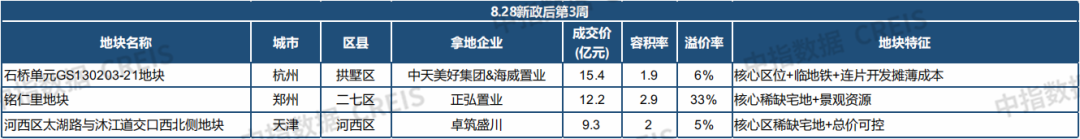
1. Zhengzhou Mingrenli plot: scarce residential land+park landscape resources in the first ring, obtained at a high premium by Zhenghong Real Estate
On September 15, plots north of Mingrenli and west of Minggong Road in the 27th district of Zhengzhou were sold. The plot is a government reserve plot with a sale area of 51070.93 square meters (about 76.6 acres), a planned construction area of about 148,900 square meters, a floor area ratio of 2.9 million meters, a building height of less than 80 meters, a starting price of 918 million yuan, and a starting floor price of about 6,200 yuan/square meter. Henan Zhenghong Real Estate Group competed for 1,218 billion yuan, with a premium rate of 32.67% and a transaction floor price of 8,226 yuan/square meter.
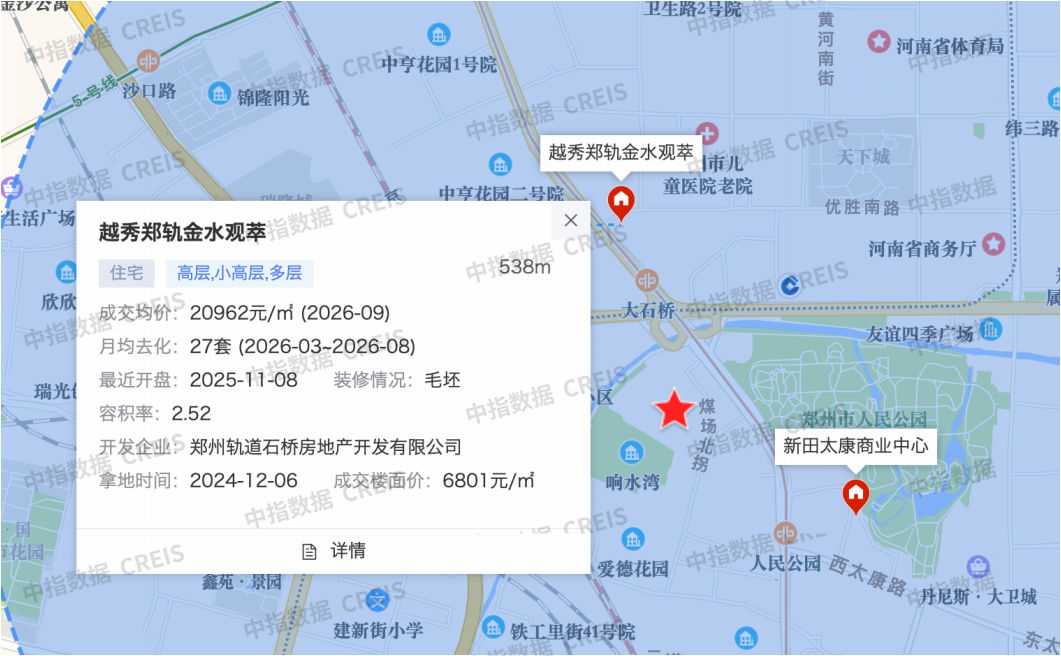
The plot is located in the core area along the First Ring Road of Zhengzhou. It is bordered by the Jinshui River in the north and People's Park in the east. Waterfront landscape and park resources are scarce in the main city; nearby, educational resources such as the East Campus of Zhengzhou No. 4 Junior High School are mature, and the urban interface and facilities are mature, making it a typical scarce residential land at the core of the main city. It is worth noting that the plot is close to the Yuexiu-Zheng Rail Jinshui Scenic Area Project. The project was developed by Yuexiu Real Estate in cooperation with Zheng Rail Real Estate. It was launched on November 8, 2025. A total of 337 units were listed, 291 units were sold, and 86% have been eliminated. It is a representative improvement project in the core area of the main city of Zhengzhou. There has been no new residential land supply in the area for many years. The good removal of Jinshui Guancui has verified the depth of demand for geographical improvement in the area and the price carrying capacity of improved products in the core area, providing a basis for research and judgment on subsequent product positioning and sales decisions in the local area.
Zhenghong Real Estate is a local private enterprise in Zhengzhou. It has been deeply involved in the Zhengzhou market for a long time, and has deeply accumulated the needs of local customers and the value of the core area. In the context of the New Deal raising pre-sale and repayment thresholds, local housing enterprises with local market accumulation and controllable capital for individual projects still maintain a certain willingness to acquire land on scarce core plots.
2. Plot GS130203-21, Shiqiao Unit, Hangzhou: the core and rail transit are superimposed, and Zhongtian Haiwei once again replenished the warehouse
On September 17, plot GS130203-21, Shiqiao Unit, Gongshu District, Hangzhou (former Huafeng Unit XC1005-R21-04 plot) was sold. The plot covers an area of 49,566 square meters, with a planned construction area of about 94,200 square meters, a floor area ratio of 1.9, a construction height limit of 50 meters, and a construction density of not more than 22%. It is a pilot project to improve the quality of housing throughout the city, and has space for a combination of high and low products. This plot is the second residential land sold by Hangzhou after the 8.28 New Deal. Previously, the Donghu Xincheng plot in Linping District was sold at a reserve price.
The starting price of the plot is 1,447 billion yuan, and the starting floor price is 15,363 yuan/square meter. After 9 rounds of bidding, the Zhongtian & Haiwei Consortium (Hangzhou Meishu Real Estate Co., Ltd.) finally competed for 1,537 billion yuan, with a premium rate of 6.22% and a floor price of 16,319 yuan/square meter. Compared with the neighboring Weixing Xingyi Jiayingfu plot sold in July 2025 (transaction price 1,627 yuan/square meter, premium rate 28.13%), the floor price of this transaction was about 3,300 yuan/square meter lower; compared with the average premium rate for residential land in the main urban area of Hangzhou since 2026 (44.8%), this premium level has also dropped significantly, reflecting the early implementation of the new housing sales policy. Pre-sale standards have been raised and repayment nodes have been delayed. In addition, the implementation rules of Hangzhou are still unclear. sex.
The plot is located at the core of the Shiqiao section in Gongshu District. It is about 600 meters from Huafeng Road Station of Metro Line 3. There are educational and commercial facilities such as Fenghua Middle School, Qiuzhi Primary School, Jingcheng Experimental School, Qinglan Qinghua Experimental Primary School, Gongshu Wuyue Plaza, and Da Runfa. The living atmosphere is strong. The land has just been repositioned in combination with the sector. It is expected to focus on small and high-rise products to meet regional market needs.
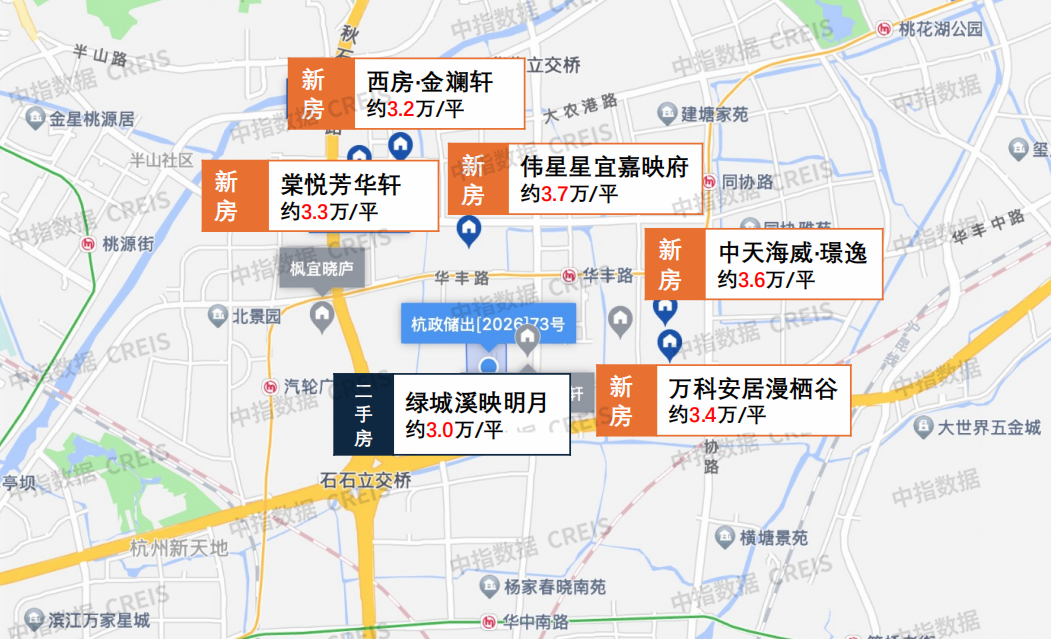
There are many internal sales projects in the sector. Projects such as Zhongtian Haiwei Jingyi Yuefu, Weixing Xingyi Jiayingfu, Vanke Anju Manqi Yunjing, Binjiang Tangyue Fanghuaxuan, and Xifang Jinlanxuan sell for about 32,000-37,000 yuan/square meter, and short-term supply competition is fierce; however, due to the extended development and pre-sale cycle after the New Deal, the entry time for new land concessions into the market will be significantly delayed. At that time, the sector's on-sale projects are expected to be basically completed, and the long-term competitive pressure is expected to ease. Zhongtian & Haiwei have previously cooperated to develop the Jingyi Yuefu project (currently about 90% have been eliminated), and have mature cooperative trading experience. This time, they have once again joined the main market, which not only reflects the desire of local housing enterprises to continue to lay out high-quality sectors in Hangzhou, but also shares financial pressure and reduces development risks through consortia, which is in line with the investment orientation of housing enterprises to “control costs and stabilize cash flow” under the New Deal.
3. Land plot in Hexi District, Tianjin: scarce residential land in the core area+controllable total price, local private enterprises can obtain it at a low premium
On September 18, the sale of the new Badali plot in Hexi District of Tianjin was completed. The land concession area is 23,814 square meters, the planned construction area is 47,628 square meters, the floor area ratio is not greater than 2.0, and it is compatible with 1100 square meters of commercial space. The project was originally an urban apartment site. In May of this year, the regulations were adjusted to residential land and the floor area ratio was lowered. It is regarded as the last pure commercial residential land in Xinbadali in the past 11 years. It is also the first residential land sold in Hexi District this year. The scarce nature is quite prominent.
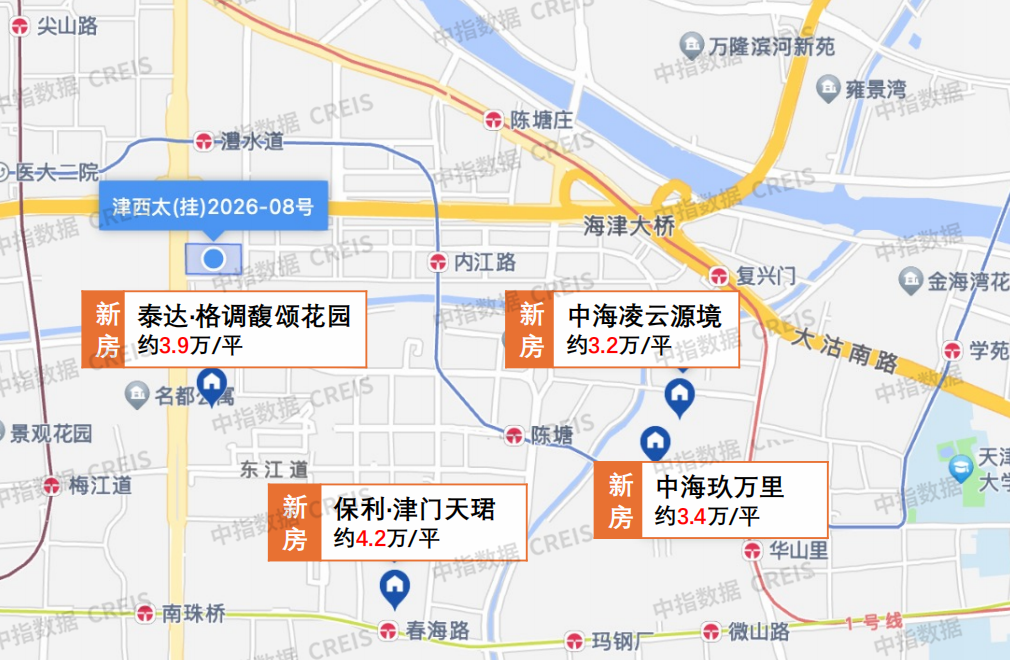
The starting price of the plot was 888 million yuan, and the starting floor price was 18,435 yuan/square meter. After 15 rounds of bidding, 4 housing companies from Zhonghai, Jinmao, Teda Construction, and Shanchuan Group participated. After 15 rounds of bidding, Tianjin Zhuochen Shengchuan, the new entity of the Yamachuan Group system, competed for 925 million yuan. The transaction floor price was 19,421 yuan/square meter, with a 5.35% premium. Looking at surrounding housing prices, Zhonghai Lingyun Yuanjing is about 40,000 yuan/square meter, Zhonghai Jiuwan is about 39,000 yuan/square meter, Teda Style Fusong Garden and Poly Jinmen Tianjun are about 42,000 yuan/square meter. At the same time, the total land price is less than 1 billion yuan, and the construction area is less than 50,000 square meters, so the capital occupation in urban residential areas is relatively manageable. It should be noted that several improvement projects have already entered the market in neighboring sectors, and the projects will face some competition in the future.
The latest listing announcements and plots to be shot in key cities in late September
1. Newly announced plots: Newly listed residential land in key cities this week has not been detected to clarify existing housing sales requirements; since the New Deal, only some plots in cities such as Xiamen, Lishui, and Jiangmen have clarified existing housing sales requirements
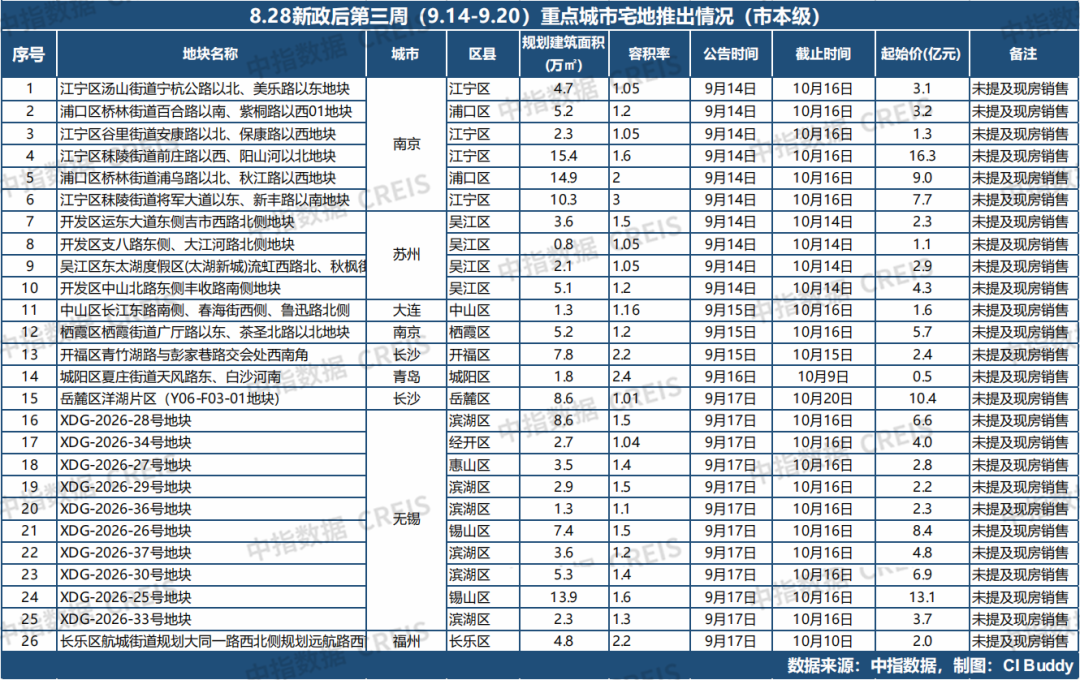
In the third week after the implementation of the New Deal, key cities such as Nanjing, Suzhou, and Wuxi issued residential land concession announcements, but judging from the sale conditions that have been disclosed so far, these residential land sales requirements are not clearly mentioned in the sale documents.
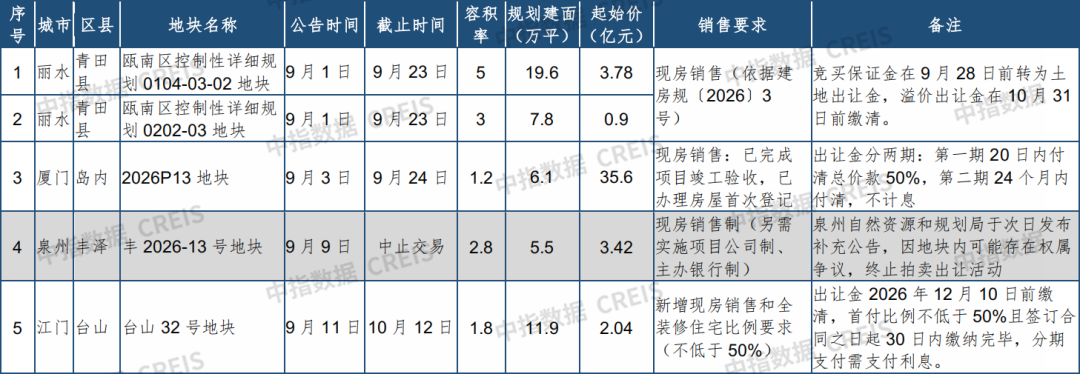
Table: Status of land plots requiring the sale of existing homes since the August 28 New Deal
Data source: China Index Research Institute as a whole
Since the New Deal (8.31-9.20), 300 cities have announced a total of 762 parcels of residential land. Only 1 in Xiamen, 2 in Lishui, 1 in Quanzhou, and 1 parcel in Jiangmen have been clearly sold. Among them, the Quanzhou “Feng 2026-13” plot issued a supplementary announcement the next day stating that the sale was terminated due to possible ownership disputes.
Also, there are differences in supporting payment policies. The 2026P13 plot concession in Xiamen can be paid in two installments. The first installment is 50% of the total price within 20 days, and the second installment is paid within 24 months without interest; the Jiangmen Taishan plot requires that the concession be paid before December 10, 2026, with a down payment ratio of not less than 50%, and payment is completed within 30 days from the date the contract is signed, and interest is payable in installments.
In the context of the New Deal extending the capital occupation cycle, Xiamen's “installment+interest-free” payment arrangement hedged the cash flow pressure on housing enterprises to a certain extent and provided a reference for local supporting policies.
2. Land to be photographed in late September: Core cities will host intensive land shooting activities at the end of the month
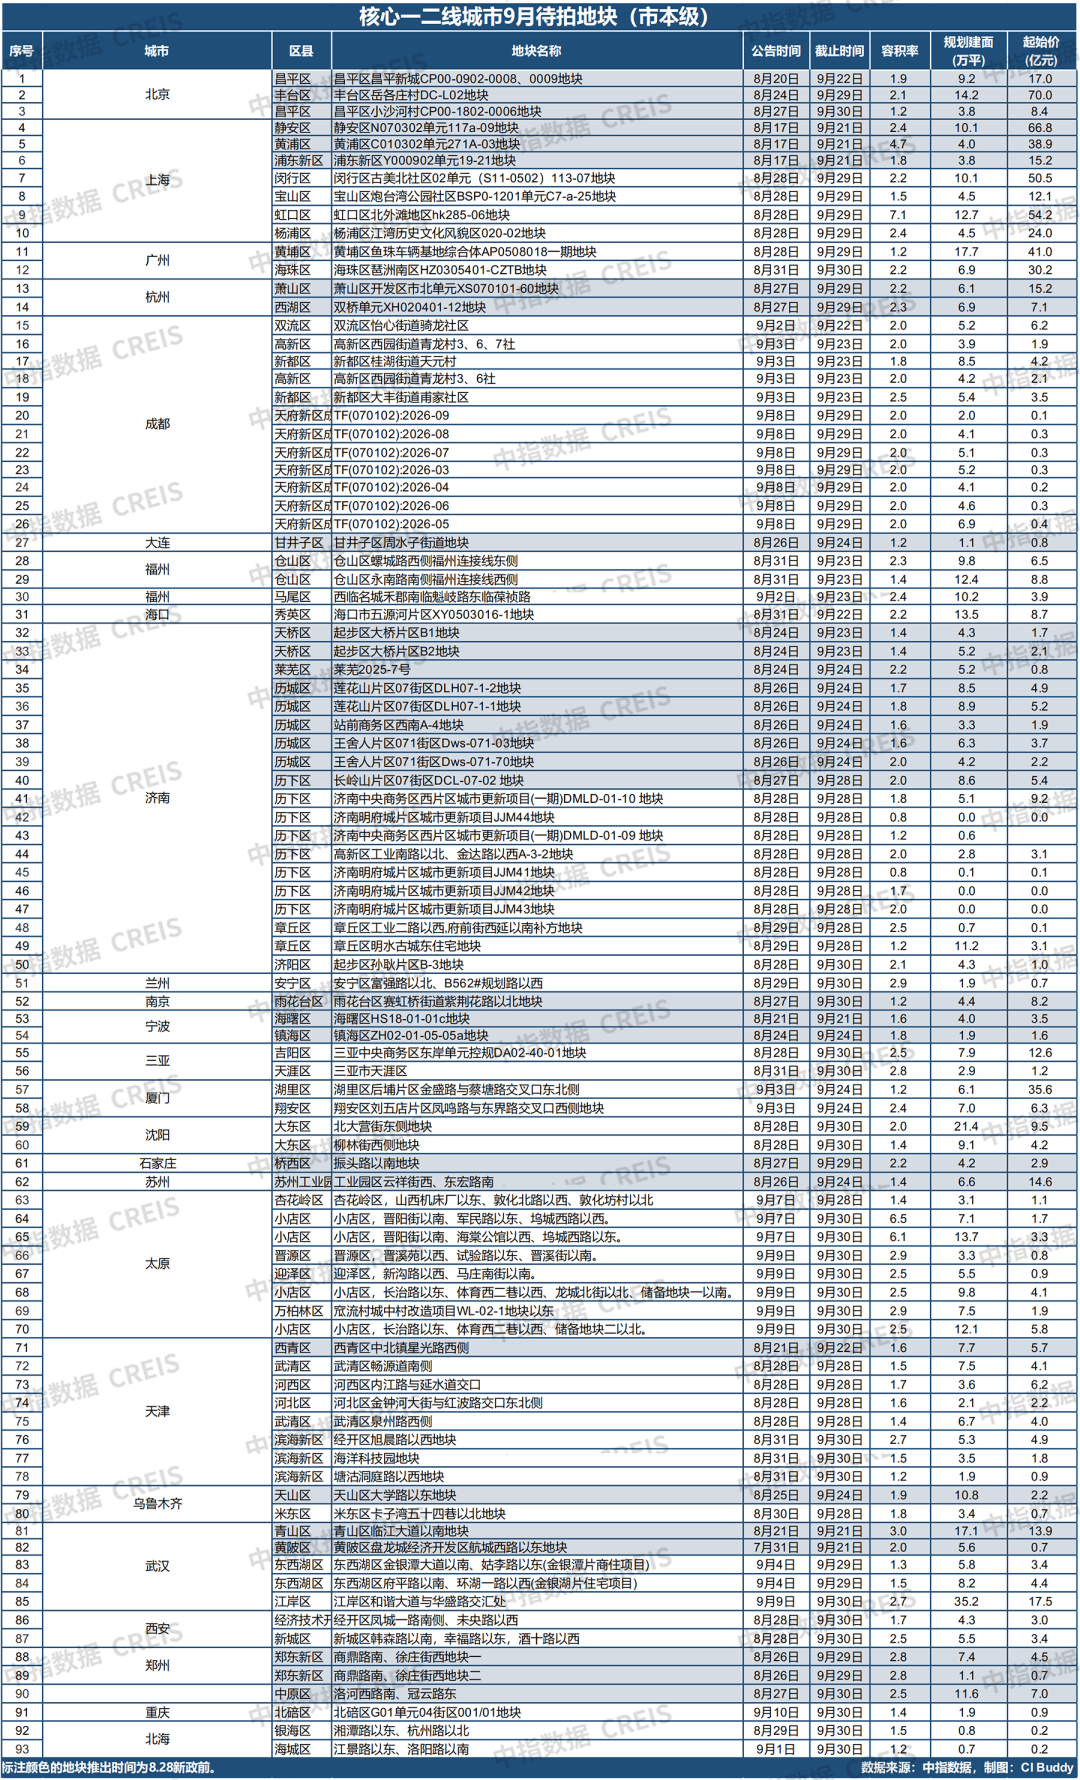
According to monitoring by the China Index, in the remaining 2 weeks of September, core Tier 1 and 2 cities will host intensive land shooting activities. 93 plots are to be filmed, with a planned construction area of about 5.97 million square meters, with a total starting price of about 75.7 billion yuan, involving various cities such as Beijing, Shanghai, Guangzhou, Hangzhou, Wuhan, Chengdu, Tianjin, and Zhengzhou. Among them, some land plots listed after the New Deal will be auctioned off, including existing land for sale in Xiamen, Lishui, etc.
By city, the frontline was still the core of the land supply at the end of the month. Seven in Shanghai, with a starting price of about 26.2 billion yuan, including key plots such as Jing'an 6.68 billion yuan, Hongkou North Bund 5.42 billion yuan, and Minhang Gumei 5.05 billion yuan; Beijing's 3 lots were about 9.5 billion yuan, mainly 7 billion yuan in Yuzhu, Fengtai; Yuzhu, Guangzhou, 4.1 billion yuan, and Haizhu Pazhou were also on the list.
epilogue
Judging from the performance of the past three weeks, the impact of the August 28 New Deal on the land market is gradually showing, but overall it is still in the policy transition stage. Currently, most of the land plots sold and to be sold are announcements before the New Deal, and the scale of newly introduced land plots after the New Deal has not yet reached scale; at the same time, there are differences in implementation standards in terms of existing housing sales and land price payment methods in various regions, and the actual effects of the policy are still to be seen. Compared to the pace of policy advancement, the reaction on the financial side of housing enterprises is more forward-looking. Against the backdrop of rising pre-sale thresholds and a lengthening capital occupation cycle, corporate quotations tend to be cautious. Reserve prices and low premium transactions are still the mainstream for non-core plots; high-quality residential land in core cities with clear locations, controllable total prices, and strong certainty of elimination still maintains a certain level of competition, and the land market is further highlighted around “certainty”.
Looking ahead to the future market, it is recommended to focus on two aspects: first, the specific settings of existing housing sales requirements and land price payment terms in the land price payment terms announced after the New Deal, which will directly affect the financial calculation and quotation level of housing enterprises; second, the registration structure and transaction premiums for key plots during the peak land supply in Beijing, Shanghai, and Sui in late September. The auction results will be an important reference for observing the investment intentions of housing enterprises. The China Index Research Institute will continue to track land market trends and changes in corporate investment strategies in key cities.