
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hinge Health (HNGE) Is In The Valuation Spotlight, Is It Still 11% Undervalued?
Jim Cramer’s recent Mad Money spotlight on Hinge Health (HNGE) put the digital musculoskeletal specialist on many watchlists, as investors weigh its rapid expansion against the current price of about $94.45 per share.
Hinge Health’s recent TV spotlight comes on top of a powerful run, with the share price up 34.2% over 90 days and a 107.31% year-to-date share price return, while the 1-year total shareholder return of 63.3% points to momentum that has already rewarded existing holders.
Scan beyond Hinge Health and see how other digital health and healthcare technology players are moving with the market by reviewing the curated 37 healthcare AI stocks.
Hinge Health has a strong share price story and clear business traction, yet those can reflect either deeper fundamentals or shifting sentiment. How does today’s valuation stack up against what the company is actually delivering?
Most Popular Narrative: 11% Undervalued
On Simply Wall St’s most followed narrative, Hinge Health’s fair value sits at $106.47, compared with the recent $94.45 close. This frames the current price as a discount to the long term earnings path that analysts have modelled using a 7.24% discount rate.
Expansion of integrated digital and in person offerings through HingeSelect and broader provider network build out positions the company to pursue a larger share of MSK and adjacent care pathways, potentially increasing lives under contract and long term revenue per client.
See why 5 investors see Hinge Health as 11% undervalued.
Result: Fair Value of $106.47 (UNDERVALUED)
Still, the Hinge Health story depends on employers and health plans sticking with digital MSK programs and on HingeSelect avoiding cost overruns that drag on margins.
Find out about the key risks to this Hinge Health narrative.
Another View: Hinge Health Through A Richer Multiple Lens
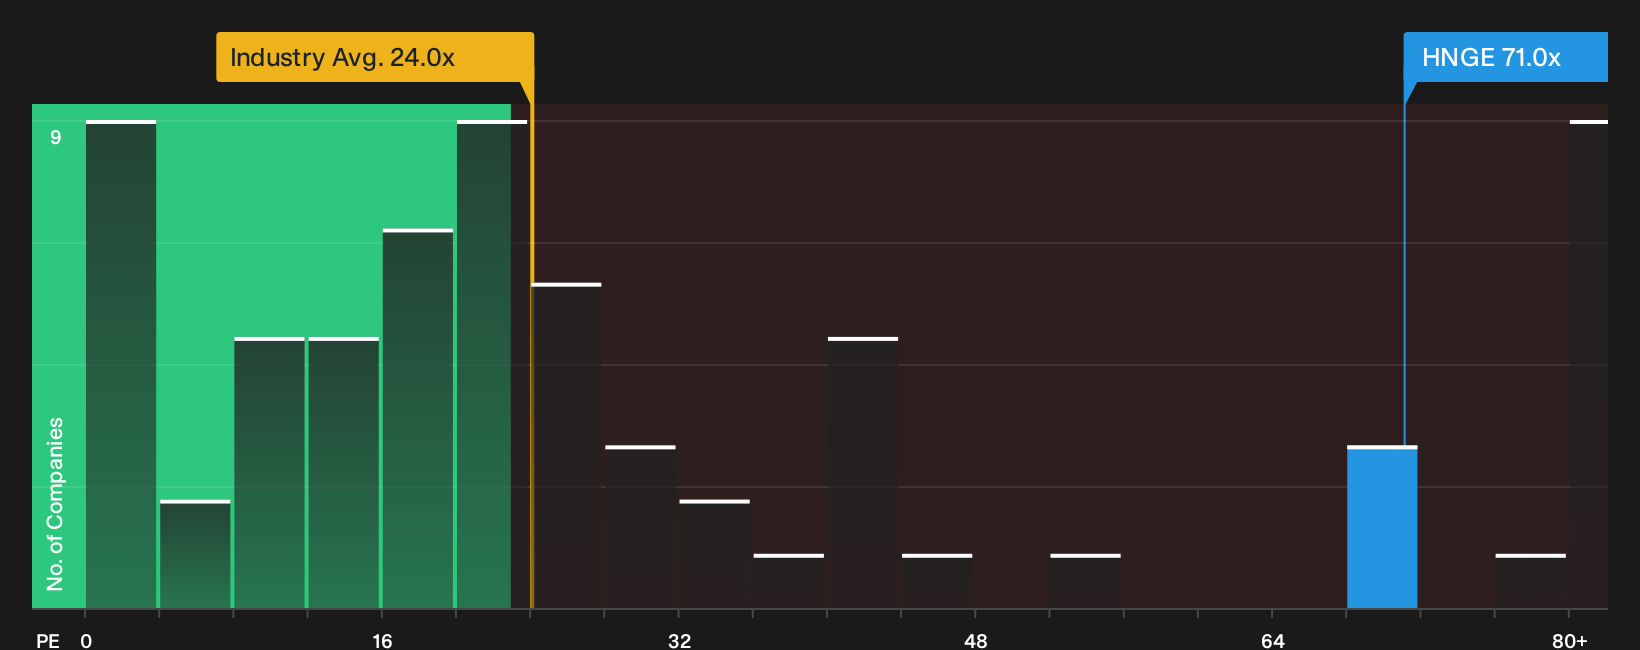
The story looks very different when shifting from fair value models to a simple earnings multiple. Hinge Health trades on a P/E of 71x, compared with 24x for the broader US Healthcare industry and 58.1x for direct peers, while the fair ratio sits at 39x.
That gap implies investors are already paying a premium for HNGE’s growth profile and profitability, which can amplify downside if sentiment cools faster than fundamentals change. How comfortable are you paying nearly double the fair ratio for this kind of growth story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Seen enough optimism around Hinge Health to be curious but still undecided on the numbers and narrative beneath it all? Act while sentiment is fresh: review the full picture and pressure test those positive factors with the 3 key rewards.
Looking for more ideas beyond Hinge Health?
If Hinge Health has sharpened your focus on opportunities in healthcare, widen your search now with a few targeted stock ideas so you do not miss what fits you best.
- Zero in on quality at a discount by scanning the 30 high quality undervalued stocks that combine strong fundamentals with prices below their assessed worth.
- Prioritise resilience by reviewing the 30 resilient stocks with low risk scores that show steadier risk profiles for investors who want fewer surprises.
- Hunt for potential future leaders by checking the 17 high quality undiscovered gems that have solid numbers but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com