
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Undervalued Stocks Trading Up To 47% Below Fair Value
Long term interest rates have shifted higher as the Federal Reserve signals a world of stickier inflation and less generous money, which puts pressure on richly priced growth stories and speculative themes. Cash now matters more than headlines. That is where businesses with solid cash generation yet modest valuations can offer a different kind of appeal. This article spotlights three candidates that screen as underpriced based on their future cash flows.
The three stocks below are just a sample, and the full screen surfaced 195 more businesses with similarly cash-rich stories and discounted valuations that are not covered here. To identify and analyze the ideas that best fit your own playbook, head straight into the Undervalued Stocks Based On Cash Flows screener.
UiPath (PATH)
Overview: UiPath provides an automation platform that uses RPA and API tools to automate workflows for enterprises across finance, healthcare, manufacturing, and retail.
Operations: UiPath generates about $1.72b in Software & Programming revenue, with around $750 million from the United States and the rest split across international regions.
Market Cap: $7.0b
UiPath matters for this cash flow focused screen because its automation platform is built around recurring subscriptions and usage based contracts that can support predictable cash generation if customers keep expanding automation across their operations.
"UiPath's focus on accelerating innovation across the agentic automation road map is expected to grow deeper customer relationships and strategic partnerships, likely driving future revenue growth."
What really moves the needle for UiPath now is whether one unresolved pressure on expansion rates quietly reshapes the margin and cash flow story.
If that pressure point matters to you, read the full narrative for UiPath to see whether automation momentum outweighs the risks now circling UiPath's expansion story.
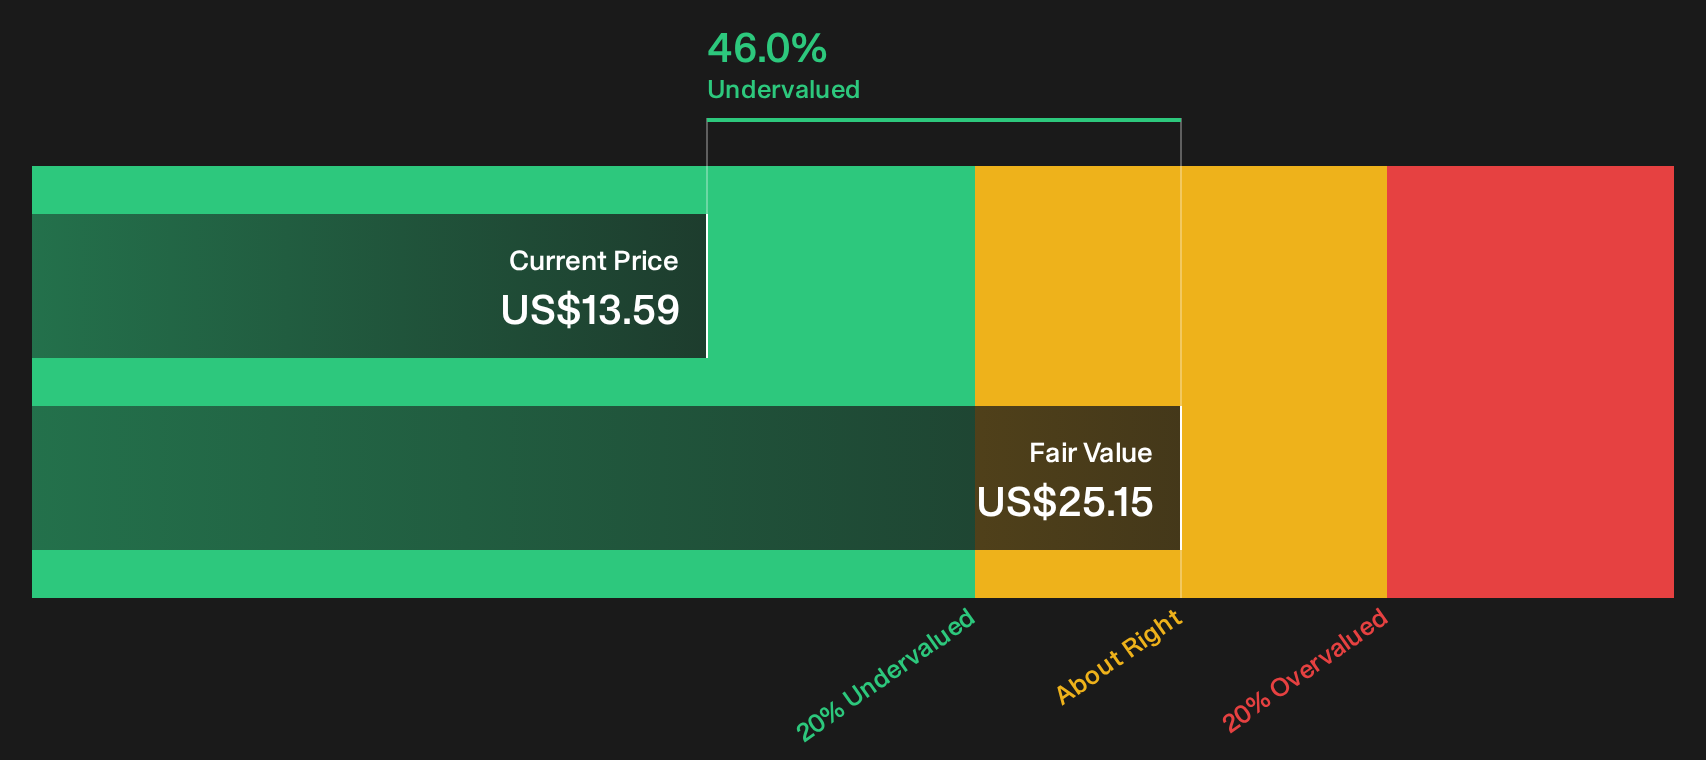
Comfort Systems USA (FIX)
Overview: Comfort Systems USA provides mechanical and electrical contracting services across HVAC, plumbing, and building energy systems, including installation, renovation, and recurring maintenance that tie directly into cash flow focused MEP work.
Operations: Comfort Systems USA generates about $8.0b from Mechanical Services and $3.2b from Electrical Services, all from customers in the United States.
Market Cap: $58.0b
Comfort Systems USA matters for this cash flow screen because its MEP installation work feeds into long term service and monitoring contracts that can support recurring free cash generation if customers keep relying on the business to run critical building systems.
"Robust and expanding project backlog, currently at a record $8.1 billion with 37% same-store growth year-over-year, demonstrates sustained customer demand for new builds and retrofit/modernization projects, directly supporting future revenue and earnings growth as the company executes on this pipeline."
What could really reshape the long term cash story is how one subtle shift in higher complexity work filters through pricing power and margins.
As that mix of complexity and pricing power plays out, read the full narrative for Comfort Systems USA to see how Comfort Systems USA could convert backlog into lasting cash strength.

Autodesk (ADSK)
Overview: Autodesk delivers cloud-based design, engineering, and construction software that turns one-off licenses into recurring subscription cash flows worldwide.
Operations: Autodesk generates about $7.79b from CAD / CAM Software, with revenue led by EMEA at $3.06b and the U.S. at $2.76b.
Market Cap: $45.34b
Autodesk matters in this cash flow focused screen because its construction and AEC cloud platforms shift customers onto steady subscription streams that feed long term DCF models.
"If one engineer with AI eventually does the work that previously required three, does the firm still need three Autodesk seats? Maybe not."
What really shapes Autodesk's cash story now is whether its subscription model can absorb that AI driven efficiency shock without losing pricing power.
To see how that tension between AI efficiency and Autodesk pricing power could actually play out, go straight to the full narrative for Autodesk for the full cash story.

Seeking Fresh Alternatives Before They Fly
New breakout stories often move fast, and the best entry points get caught by early movers while it still matters. Do not let fresh ideas pass by; get in early.
- Spot cash rich businesses built on strong foundations before they get crowded by late money through the curated list of solid balance sheet and fundamentals (23 results).
- Track where steady income and high yields meet, and see which payout heavy candidates make the cut in the focused 7 dividend fortresses.
- Follow the quiet build out of nuclear power infrastructure and see which potential suppliers could gain momentum inside the specialist 19 nuclear energy infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com