
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 Australian Value Stocks To Watch In September 2026
Central banks are lifting interest rates to tackle sticky inflation, which puts pressure on highly leveraged businesses but can reward investors who focus on real cash being generated today. Australian companies that throw off solid cash flows yet trade below their estimated fair value can offer a rare combination of resilience and potential upside. This article profiles three such stocks that screen well on discounted cash flow metrics.
The three stocks highlighted below are a small sample from this idea. The full screen surfaces 1 more business with cash flow stories that are not covered here but sit in the same value bucket. To identify and analyze the full opportunity set for this theme, head straight to the Undervalued Stocks Based On Cash Flows screener.
Regis Resources (ASX:RRL)
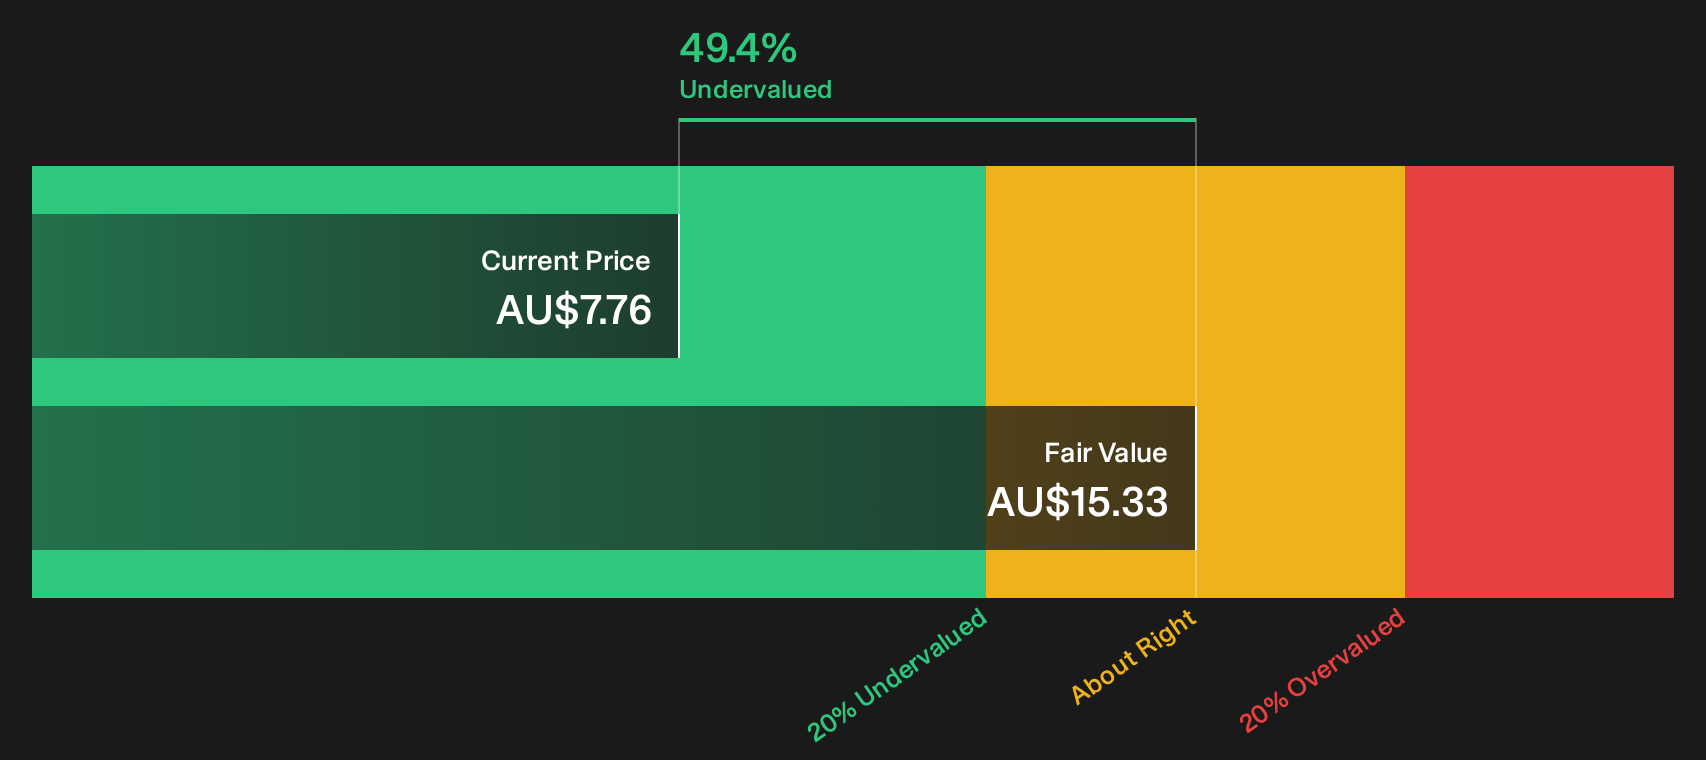
Regis Resources is a pure-play Australian gold producer whose cash-generative mines fit neatly with a screener focused on discounted cash flow value. This gives investors exposure to current production and an internal pipeline rather than early stage exploration risk.
Regis Resources runs producing gold operations at Duketon and Tropicana and is progressing the McPhillamys project. Duketon contributed about A$1.5b of revenue and Tropicana about A$900 million, entirely from Australia, and the business carries a market value of roughly A$5.9b.
"Regulatory and environmental barriers are stifling new mine supply globally, increasing the strategic value of established, expandable operations like those of Regis. This dynamic supports a long-term upward shift in realized gold prices and offers the potential for durable revenue and margin expansion for existing shareholders."
What really matters now is how one unresolved cost and timing pressure interacts with those cash rich assets and feeds through to future margins.
Those cost and timing pressures are exactly what the full narrative for Regis Resources unpacks, showing where near term friction could be masking longer term cash strength.
NobleOak Life (ASX:NOL)
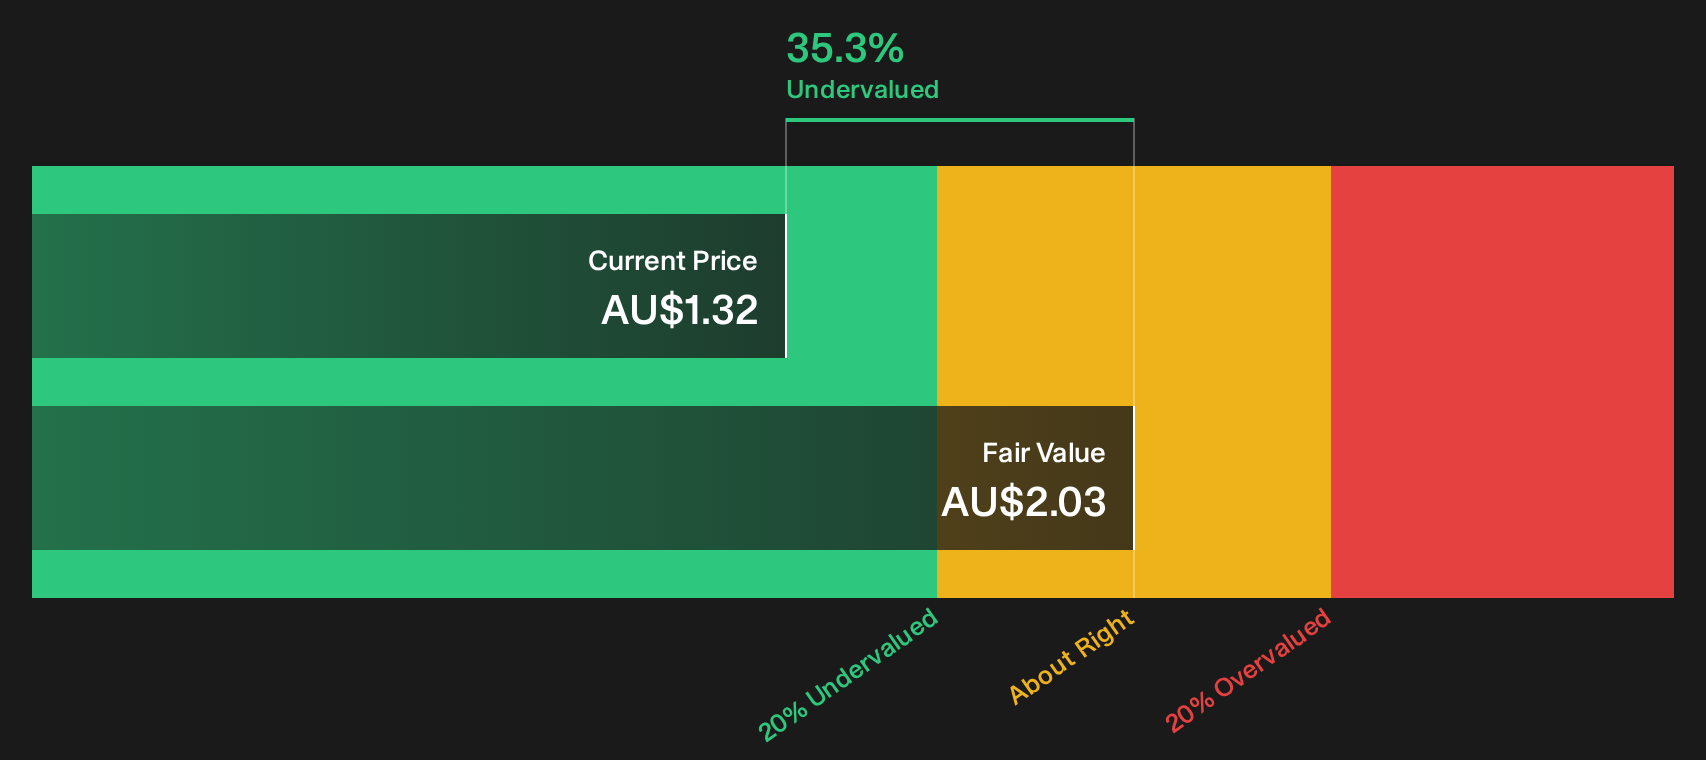
NobleOak Life is a Sydney based insurer focused on life, income protection, TPD and trauma cover, where recurring premiums are well suited to discounted cash flow analysis. It generated about A$399 million from strategic partnerships, A$106 million from direct channels and A$15 million from Genus, and has a market value near A$120 million.
NobleOak Life trades on a P/E of 8.5x against a global insurance average of 11.8x, while screener estimates place fair value materially above the current share price based on its recurring premium streams. The appeal of that valuation gap depends on how one unseen pressure shapes funding costs and future margins.
That hidden pressure is exactly what the analysis report for NobleOak Life unpacks, showing where recurring premiums could be masking either stretched capital or underappreciated earnings power.
JB Hi-Fi (ASX:JBH)
JB Hi-Fi is a large Australian retailer of consumer electronics and home appliances, where high-margin items like TVs, computers and whitegoods are central to the cash generation that underpins its place in this cash-flow-focused screen.
It produces most of its sales through JB Hi-Fi Australia at about A$7.4b and The Good Guys at roughly A$2.9b, with smaller contributions from JB Hi-Fi New Zealand at about A$431 million and e&s at about A$273 million, and the stock carries a market value near A$7.2b.
For value-focused investors, JB Hi-Fi is of interest because those electronics and appliance sales convert into cash, which supports a discounted cash flow view of the stock rather than a pure sales growth story.
"The acquisition of e&s is expected to enhance JB Hi Fi's access to premium home appliances and expand the customer base to include builders and commercial clients, with the potential to support revenue growth."
What matters from here is how one unresolved pressure on profitability interacts with that extra volume and shapes long term cash returns.
That profit pressure is exactly what the full narrative for JB Hi-Fi breaks down, showing where cash generation, e&s integration and margin risks may be masking JB Hi-Fi's next leg of earnings power.

Curious About What You Are Missing?
Fresh ideas move first. By the time momentum is flying, the easy entry points are gone. Scan curated stock lists that are under the radar for now and act now.
- Spot early trend leaders before headlines catch up by running your filters through the 88 AI infrastructure stocks while the build out of digital plumbing is still priced cautiously.
- Hunt for income streams that can steady a portfolio by reviewing the curated 4 dividend fortresses before yields drop and the chase for dependable payouts intensifies.
- Track capital pouring into clean atomic power by checking the focused 19 nuclear energy infrastructure stocks while sentiment is still rebuilding and select operators trade quietly.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com