
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Main Street Capital (MAIN) Could Be 5% Undervalued As Dividend Sustainability Stays In Focus
Main Street Capital (MAIN) just reaffirmed its income-focused story with a declared monthly dividend of $0.27 per share payable on 15 October 2026, while investors debate its elevated payout ratio of 0.87.
Recent trading suggests momentum in Main Street Capital has cooled, with the 30 day share price return down 3.45% and the year to date share price return down 8.86% even after a 12.52% gain over 90 days. Yet long term income holders have still seen resilience, with total shareholder return of 75.67% over three years and 99.44% over five years. This indicates that dividends have played a major role in the overall outcome, even as the current US$56.28 share price reflects renewed debate around valuation and dividend sustainability.
Compare Main Street Capital's income profile with a curated list of other high-yield candidates by scanning 7 dividend fortresses that share a focus on durable cash distributions.
After a three year run where dividends did much of the heavy lifting, and a recent pullback that cooled enthusiasm, is the real upside in Main Street Capital still ahead or already mostly behind the current US$56.28 price tag?
Most Popular Narrative: 5% Undervalued
With Main Street Capital last closing at $56.28 against a narrative fair value of $59.50, the story hinges on whether income strength and portfolio breadth can outweigh concerns about credit quality and payout pressure.
The strong liquidity and conservative leverage profile maintained by Main Street Capital, supported by long-term lender relationships and successful debt offerings, provide financial stability and flexibility, potentially enhancing its ability to navigate economic downturns better than anticipated and drive share price growth.
Continuous positive results from Main Street's asset management business and the generation of significant incentive fee income denote another stable revenue stream, improving the company’s financial health and potentially leading to an increase in its share price contrary to the expectation of a decrease.
See why 88 investors see Main Street Capital as 5% undervalued.
Result: Fair Value of $59.50 (UNDERVALUED)
Still, credit issues in consumer facing borrowers, along with the possibility of weaker supplemental dividends at Main Street Capital, could quickly challenge this underpriced thesis.
Find out about the key risks to this Main Street Capital narrative.
Another View: Main Street Capital On Earnings Power
The first story around Main Street Capital leans on an analyst fair value of $59.50, which paints the stock as modestly underpriced. A different lens tells a less forgiving story. The Simply Wall St DCF model estimates future cash flow value at $39.17, with MAIN trading well above that at $56.28.
This gap suggests that even with Main Street Capital’s income appeal, cash flow assumptions may already be running hot in the current price. For investors who prefer to anchor decisions in long term cash generation rather than dividends or P/E ratios, the key question is simple: Which narrative do you trust more when the next rough patch hits, the income story or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
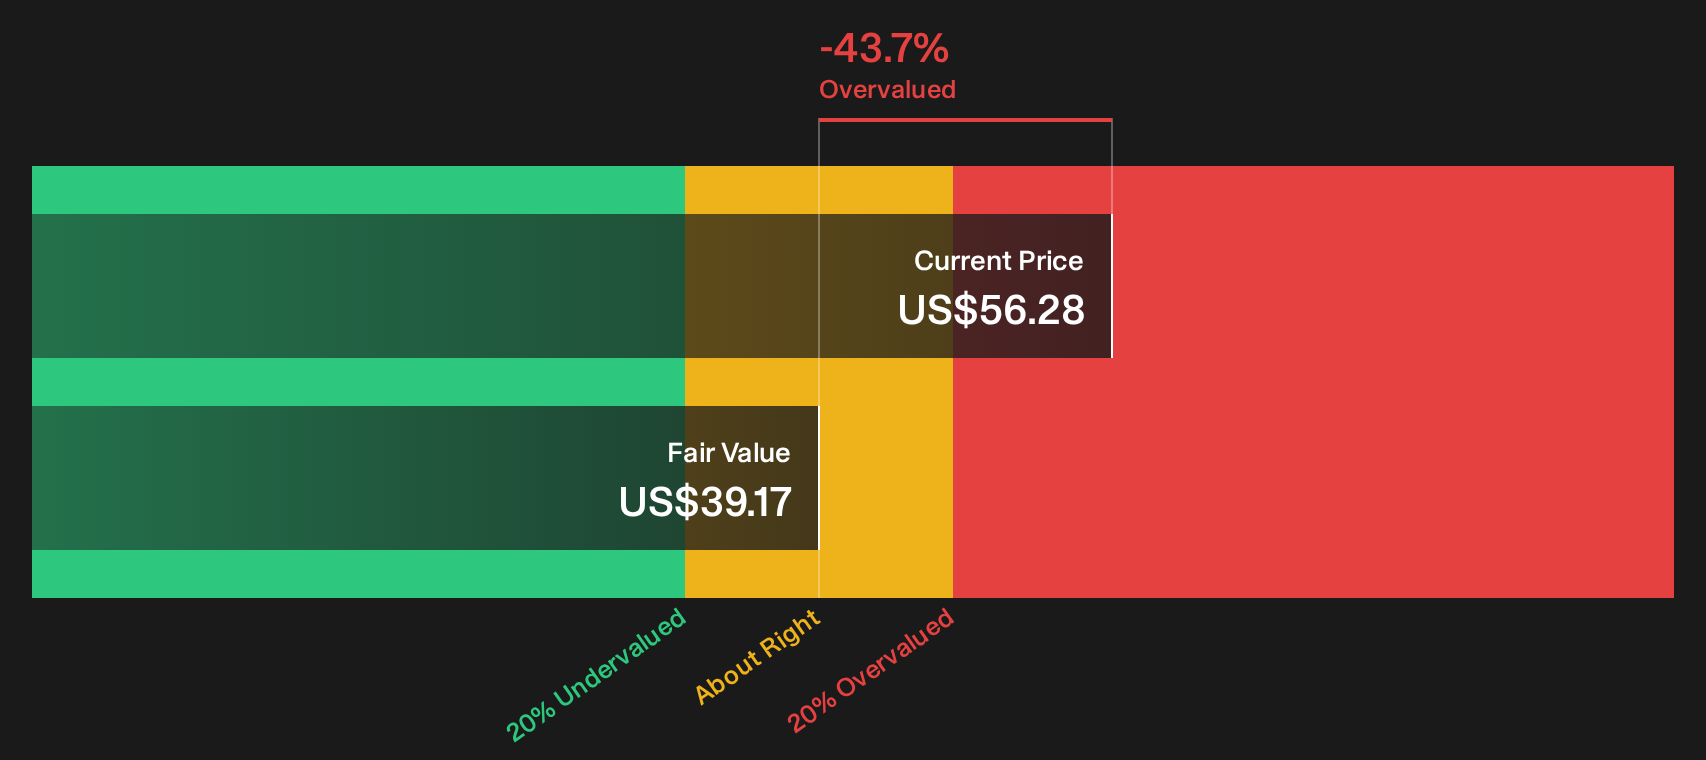
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Main Street Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Main Street Capital's value case are clear, so consider promptly stress testing the upside and downside for yourself using the 1 key reward and 5 important warning signs.
Ready For More Ideas Beyond Main Street Capital?
If Main Street Capital has sharpened your income lens, do not stop here. Use fresh tools to find other opportunities that better fit your goals and risk comfort.
- Target steady compounders by scanning the 30 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their underlying strength.
- Lock in stronger balance sheet protection by reviewing the list of solid balance sheet and fundamentals (23 results) that can help cushion your portfolio when conditions turn rough.
- Hunt for tomorrow's potential standouts by checking the 16 high quality undiscovered gems before the broader market starts paying closer attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com