
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Jeep Recall Change The Bull Case For Stellantis (BIT:STLAM)?
- Stellantis has recalled 201,976 Jeep vehicles in the U.S. due to a tire pressure monitoring software issue and is updating the software at no cost to owners, while also overhauling its manufacturing footprint through moves such as the Brampton plant sale and the Hordain van facility upgrade.
- The combination of quality-focused recalls and factory reconfiguration puts Stellantis' execution on costs, capital allocation, and product reliability under sharper scrutiny for long term fundamentals.
- The next area of focus will be how Stellantis' investment narrative is affected by the large U.S. Jeep recall and related quality efforts.
Stellantis Investment Narrative Recap
To own Stellantis, you need to believe the group can turn a broad, complex portfolio into consistent cash despite recalls, electrification costs and trade pressure. The Jeep software recall and fresh questions around quality control keep execution in the spotlight but do not radically change the near term story, which still hinges on stabilising margins and cash flow.
The key near term catalyst is progress on restructuring and factory retooling that supports future BEV and LCV volumes. The biggest risk remains execution drag, from tariff related cost pressure to warranty and recall charges. Quality issues tied to Jeep feed that risk, yet the operational fixes look manageable if warranty costs do not escalate.
The most relevant fresh data point for that debate is the new 2027 Jeep Wrangler JL 2A special edition. It leans heavily on Jeep heritage and Rubicon capability, which matters because Jeep is central to Stellantis and to its pricing power story in North America. Product storytelling still appears strong even as quality and recalls take oxygen.
For you as an investor, the JL 2A helps frame the trade off. Stellantis keeps investing in higher content and enthusiast leaning Jeeps that can support mix and brand strength, while facing margin risk from BEV rollouts, tariffs and operational clean up. How effectively it delivers both emotionally resonant product and tighter cost control will shape how current catalysts play out.
Stellantis' current analyst narrative points to revenues of €174.5b and earnings of €4.9b by 2029. That profile lines up with an assumed 2.7% yearly increase in revenue and an earnings swing of €24.4b from earnings of a €19.5b loss today to the projected €4.9b profit.
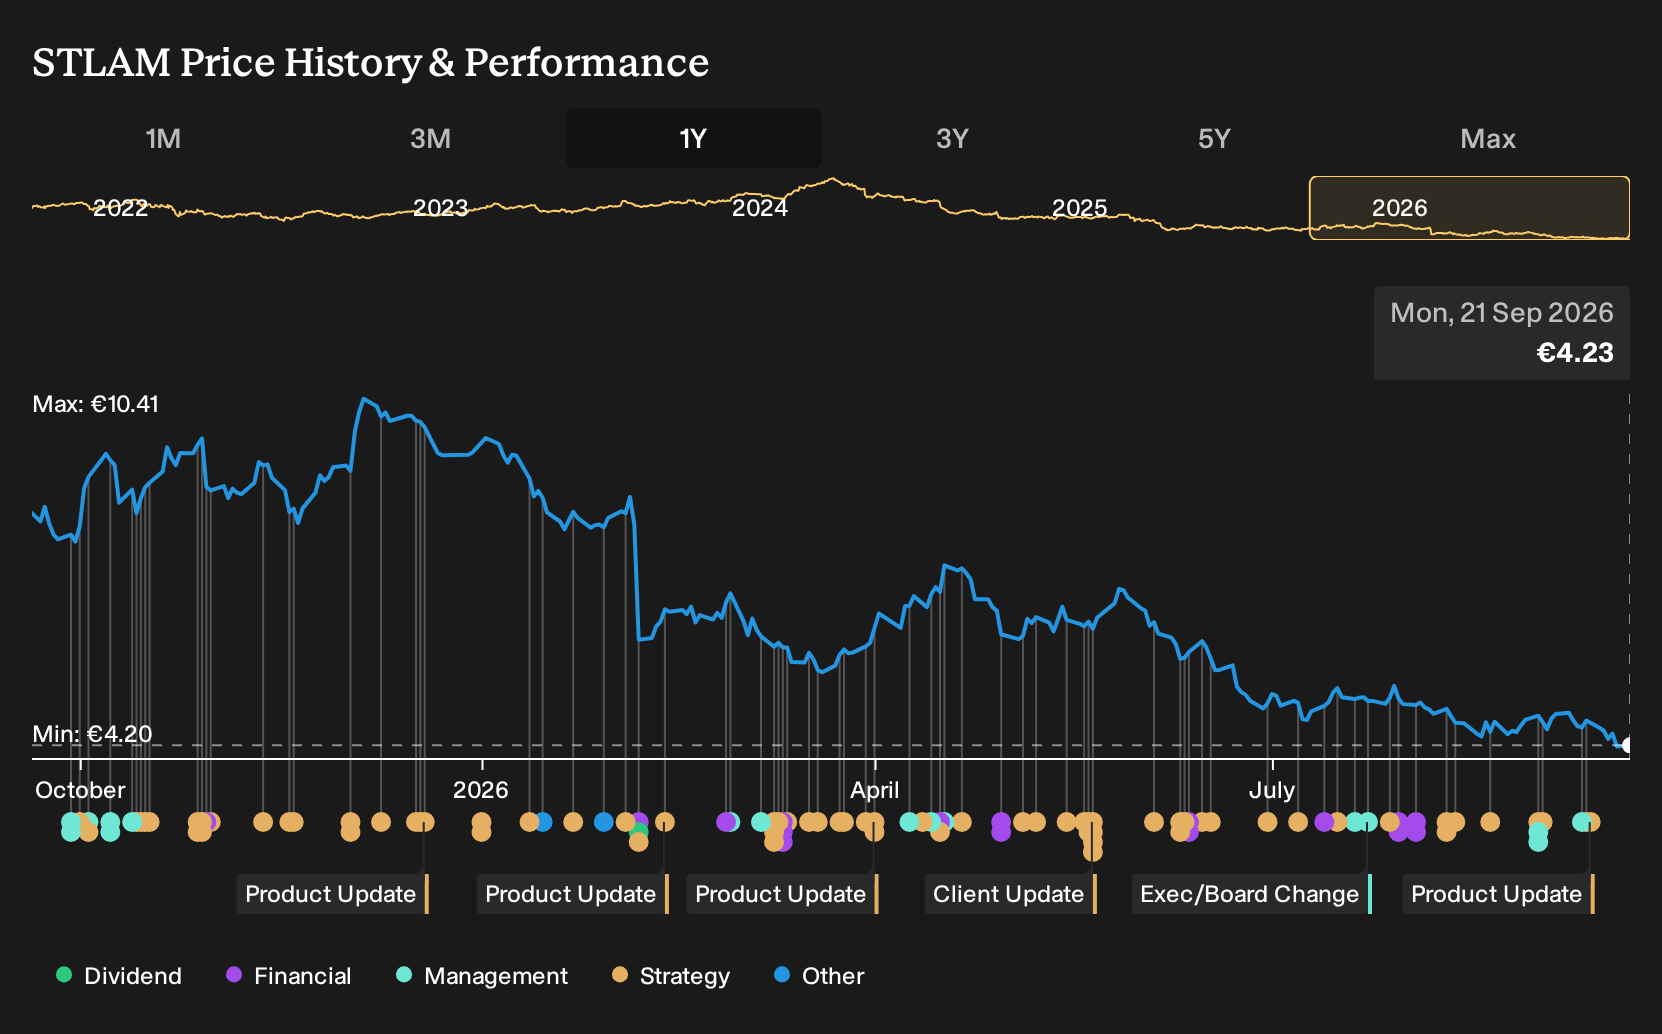
Uncover how Stellantis' fair value indicates a 37% potential upside to its current price before that gap starts to close.
Exploring Other Perspectives
One catalyst the most optimistic analysts keep circling back to is Stellantis' product pipeline. Before this Jeep recall and the JL 2A launch, the bullish camp was projecting revenue of about €189.9b and earnings of €11.1b by 2029, far above consensus. You can read that as a much more upbeat story that may shift as quality headlines evolve.
Explore 10 other Stellantis fair value estimates, including one that suggests as much as 292% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stellantis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stellantis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stellantis' overall financial health at a glance.
Looking For More Ideas Beyond Stellantis?
If the Stellantis story has sharpened your thinking about quality, balance sheets and execution risk, it can be useful to line it up against other businesses with different profiles. The Simply Wall St Screener lets you quickly scan prepared shortlists so you can compare risk, income and valuation trade offs in a structured way instead of jumping between tickers at random.
- For investors who care most about strong finances and resilient operations, start with a list of solid balance sheet and fundamentals (198 results) that keep financial strength front and centre.
- If your priority is finding potential value opportunities with robust fundamentals, broaden the search with a curated set of 615 high quality undiscovered gems that may not yet be widely followed.
- Income focused investors who want cash flow today as well as long term potential can scan a focused group of 160 dividend fortresses that balance yield with business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com