
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How FTSE All World Inclusion At Jabil Stock Has Changed Its Investment Story
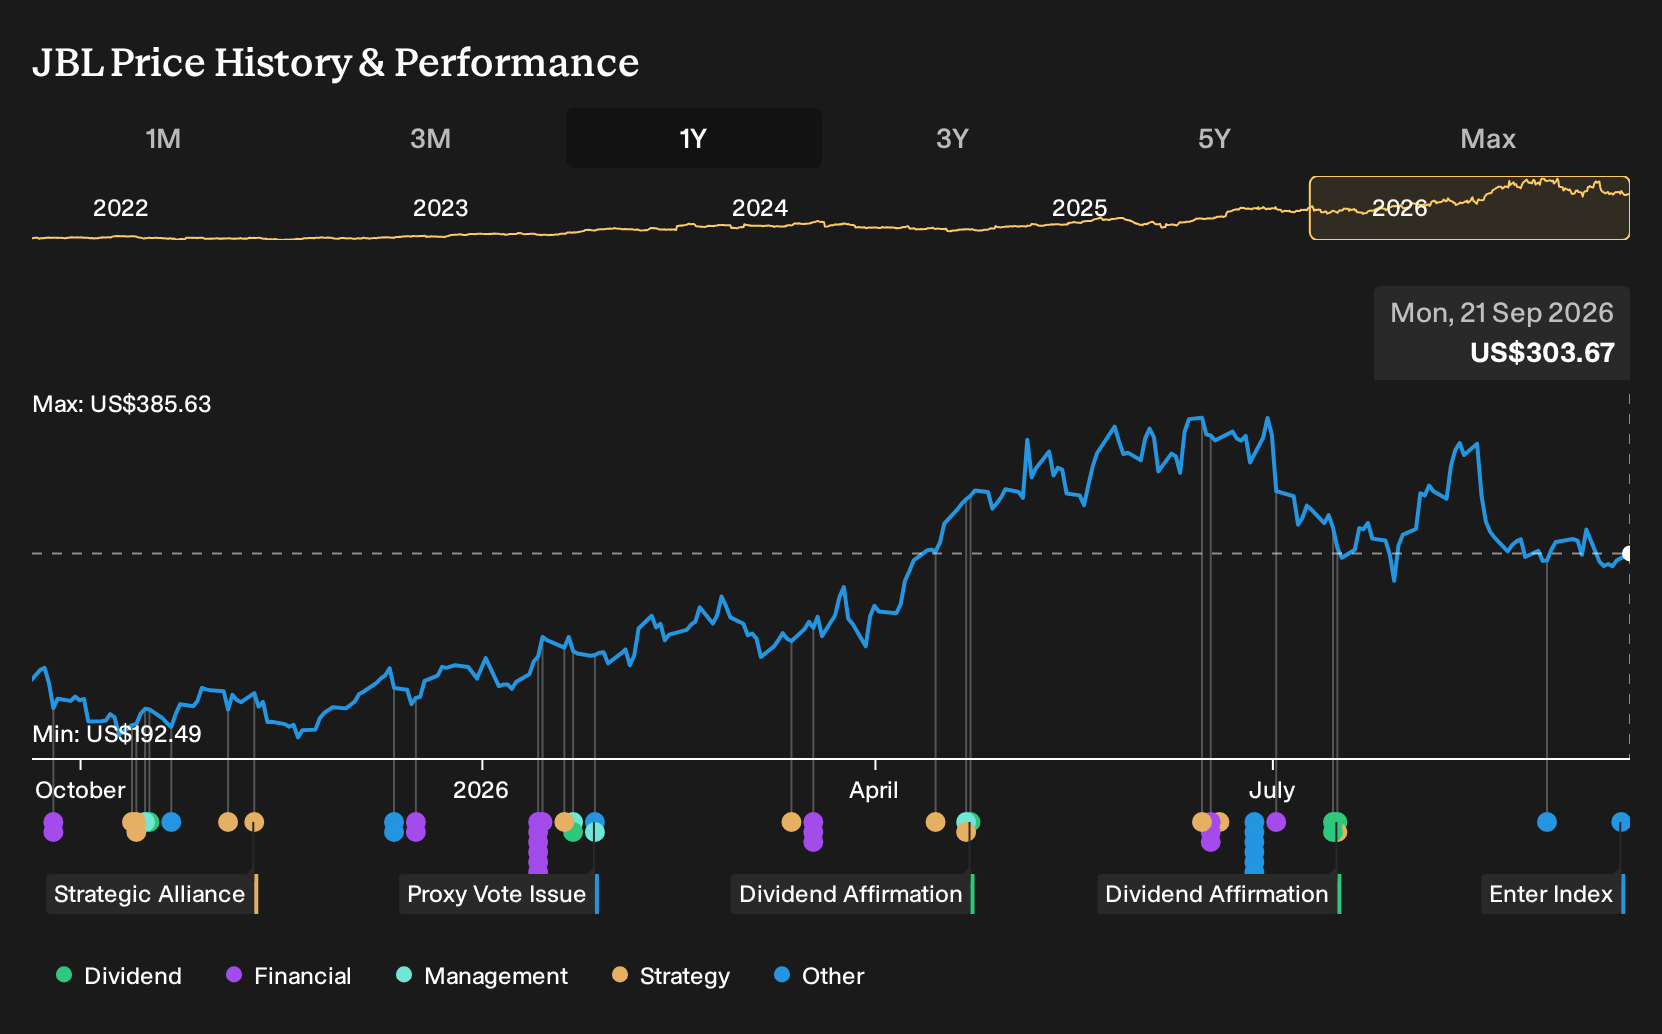
- Jabil was added to the FTSE All-World Index in September 2026, placing the electronics manufacturer inside a widely tracked global benchmark.
- The move could influence how index-linked funds and asset allocators access Jabil, which already operates across U.S. manufacturing, India expansion and pharmaceuticals.
- This development may contribute to shaping Jabil's broader investment narrative for long term holders.
Scan how index inclusion is reshaping interest beyond Jabil by reviewing the curated list of solid balance sheet and fundamentals (23 results) that already attracts benchmark trackers and long term fund flows.
Jabil Investment Narrative Recap
To own Jabil, you need to believe the manufacturing platform can keep winning work across regulated industries, infrastructure and connected devices while handling softer demand in areas like EVs, renewables and consumer electronics. The FTSE All World inclusion does not change that core thesis. The key near term swing factor remains execution on higher margin programs such as AI related hardware and pharmaceutical solutions.
The biggest risk still sits in end market demand and capital intensity rather than index membership. Weakness in EV and renewable projects, along with pressure in Connected Living, could weigh on revenue mix and cash generation. Higher debt levels and slightly elevated inventory days also put more focus on consistent free cash flow delivery.
With no fresh operating announcements alongside the FTSE All World addition, the most relevant reference point remains Jabil's expansion efforts in areas flagged by analysts. The business has been building out its U.S. manufacturing footprint, India capacity and pharmaceutical capabilities through the Pharmaceutics International acquisition. Those moves align with the segments analysts expect to be important future contributors.
For you as a shareholder, the practical question is execution. Added index visibility may support liquidity, but the real catalyst still lies in converting AI related demand, India scale up and pharma outsourcing into steady earnings and cash flows. In contrast, tariff uncertainty, higher risk funding and exposure to slower segments like EVs and renewables remain on the risk checklist.
What The Current Jabil Forecasts Assume
Jabil's narrative projects US$54.9b revenue and US$2.2b earnings by 2029. This rests on analysts pencilling in 17.8% yearly revenue growth and an earnings increase of about US$1.3b from US$862.0m today.
Uncover why Jabil's fair value points to a 41% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
You can see how divided opinion on Jabil really is when you look at AI data center exposure. The most cautious analysts worry this demand cools and had pencilled in revenue of about US$48.9b and earnings near US$2.0b by 2029, compared with the higher consensus, before this index inclusion even arrived. That gap may shift as forecasts update.
Explore 2 other Jabil fair value estimates, including one that suggests it could be worth just $429.56!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Jabil research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jabil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jabil's overall financial health at a glance.
Looking For More Ideas Beyond Jabil?
If you want to stress test your thesis on Jabil and widen your opportunity set at the same time, the Simply Wall St Screener can help you scan for other businesses that fit your preferred mix of quality, resilience and upside potential.
- For investors who care about robust finances and staying power, start with a list of solid balance sheet and fundamentals (23 results) that can help you focus on companies with room to handle tougher conditions.
- If value is your priority and you like the idea of strong fundamentals at a price that still looks reasonable, filter for a 30 high quality undervalued stocks that might complement or contrast with your view on Jabil.
- Income focused readers who want their portfolio to work harder on the yield side can review a 7 dividend fortresses that highlights stocks offering higher payouts supported by underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com