
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UL Solutions (ULS) Expands Testing Capacity, Is The Stock Cheap Or Pricey?
UL Solutions (ULS) has put fresh attention on its testing and certification business after expanding its Lowell, Arkansas, Retail Center of Excellence and rolling out a new vehicle to grid certification program.
Despite these product and lab initiatives, UL Solutions’ recent share price return has come under pressure, with the stock down 11.64% over 30 days and 26.06% over 90 days, while the 1-year total shareholder return has declined a milder 2.59%. This suggests shorter term momentum has faded even as long term holders have seen a smaller drag.
Scan a hand picked group of testing, certification and infrastructure peers by reviewing the list of solid balance sheet and fundamentals (23 results), which may offer a steadier backdrop than UL Solutions' recent share price swings.
UL Solutions is rolling out fresh lab capacity and new programs just as the share price has retreated sharply. Is this slide pointing to cracks in the business, or mainly a reset in sentiment that valuation now needs to explain?
Most Popular Narrative: 32% Undervalued
Against a last close of $66.32 for UL Solutions, the most widely followed narrative anchors fair value closer to $98, which frames the recent share price slide as more of a valuation gap than a collapse in the testing franchise.
UL Solutions' robust revenue growth, strong profitability, strategic investments, and stable income streams position the company for sustained success and future expansion.
See why 5 investors see UL Solutions as 32% undervalued.
Result: Fair Value of $98.23 (UNDERVALUED)
Still, if UL Solutions faces weaker product demand or tighter customer budgets, that could pressure revenue, while a higher effective tax rate may restrain earnings.
Find out about the key risks to this UL Solutions narrative.
Another View on UL Solutions’ Valuation
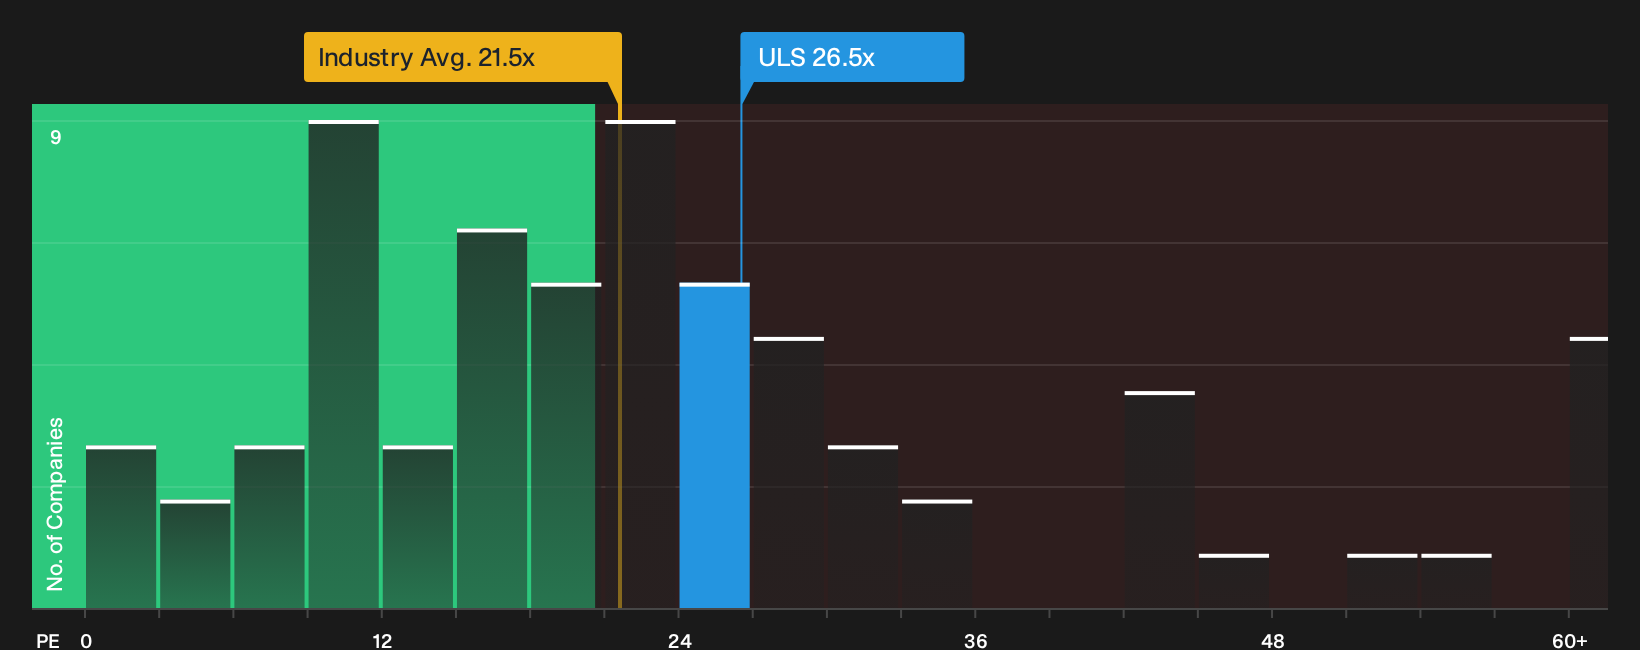
The first narrative leans heavily on discounted cash flows and analyst targets that cluster around $98. Yet on simple P/E, UL Solutions looks expensive. The stock trades on 26.5x earnings, while the fair ratio is 17.6x, the US Professional Services group sits at 21.5x, and peers average 25.8x.
This gap suggests investors today pay a richer price than both the modelled fair ratio and the wider industry. It raises the question of whether that premium reflects durable quality, or whether it leaves less room if sentiment cools further.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There have been mixed messages on UL Solutions so far, and that tension may be clear in the valuation discussion. Act promptly and review the balance of concerns and potential upsides by checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond UL Solutions?
If UL Solutions has you reassessing where your capital works hardest, widen the lens and line up a few fresh ideas before the next move passes you by.
- Target potential mispricing by scanning a curated pool of quality companies that screens for valuation support through the 30 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by reviewing a 30 resilient stocks with low risk scores that filters for sturdier fundamentals and more stable profiles.
- Get ahead of the crowd by checking a 16 high quality undiscovered gems that focuses on under-followed businesses with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com