
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Undervalued Asian Small Caps With Insider Buying To Consider
In recent months, the Asian markets have experienced a mix of volatility and growth, with small-cap stocks in particular facing challenges amid fluctuating economic indicators and broader market sentiment. As investors navigate these conditions, identifying stocks with strong fundamentals and insider buying can offer valuable insights into potential opportunities within the small-cap sector.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| China Aircraft Leasing Group Holdings | 7.4x | 1.0x | 35.34% | ★★★★★☆ |
| Australian Finance Group | 7.5x | 0.3x | 23.92% | ★★★★★☆ |
| Universal Robina | 11.4x | 0.7x | 29.94% | ★★★★★☆ |
| Ho Bee Land | 13.1x | 2.7x | 43.63% | ★★★★★☆ |
| SHAPE Australia | 18.3x | 0.5x | 46.14% | ★★★★☆☆ |
| Mader Group | 19.7x | 1.3x | 49.30% | ★★★★☆☆ |
| Domino's Pizza Enterprises | NA | 0.9x | 14.55% | ★★★★☆☆ |
| ReadyTech Holdings | NA | 1.4x | 48.07% | ★★★★☆☆ |
| Aztech Global | 12.6x | 1.1x | -100.43% | ★★★☆☆☆ |
| Paragon Care | NA | 0.1x | -12.00% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
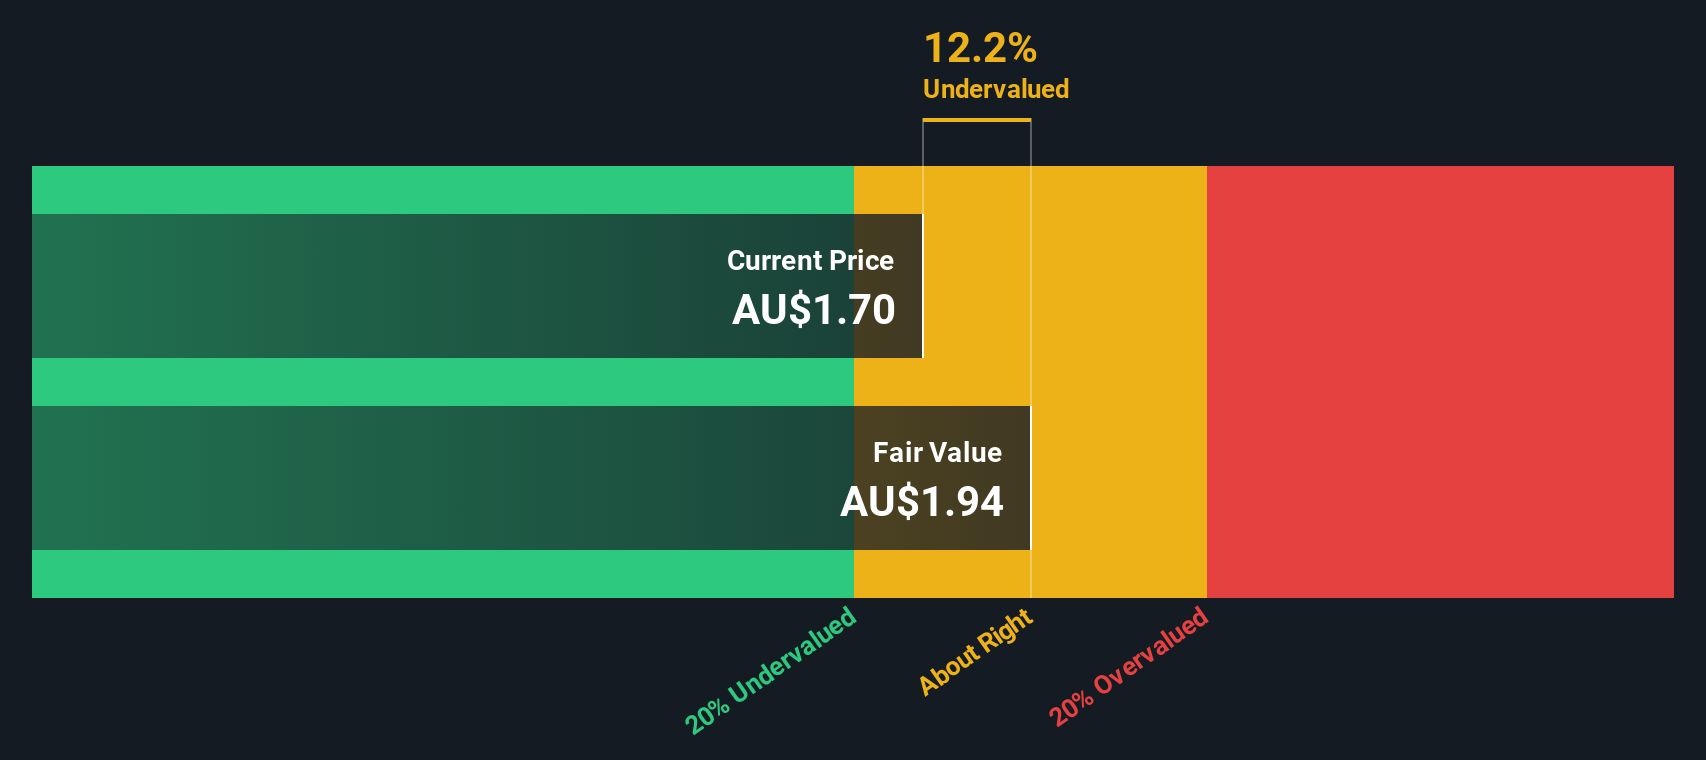
Nine Entertainment Holdings (ASX:NEC)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Nine Entertainment Holdings operates in the media sector, encompassing outdoor advertising, corporate services, publishing, and streaming & broadcast segments with a market capitalization of A$3.95 billion.
Operations: Nine Entertainment Holdings generates revenue primarily from its Streaming & Broadcast segment, which contributes A$1.60 billion, and the Publishing segment, contributing A$517.49 million. The company's gross profit margin has shown variability over time, reaching 26.83% in December 2022 before declining to 16.00% by June 2026. Operating expenses and non-operating expenses have been significant factors affecting profitability across periods analyzed.
PE: -3.5x
Nine Entertainment Holdings, a small player in the media landscape, recently reported a significant rise in net income to A$511.29 million for the year ending June 2026, up from A$103.89 million previously. Despite high debt levels and reliance on external borrowing, insider confidence is evident with recent share purchases. The company's earnings are projected to grow by 58% annually, suggesting potential growth amidst financial challenges. An experienced media executive joined their board in August 2026, potentially steering strategic initiatives forward.
Philippine National Bank (PSE:PNB)
Simply Wall St Value Rating: ★★★★★☆
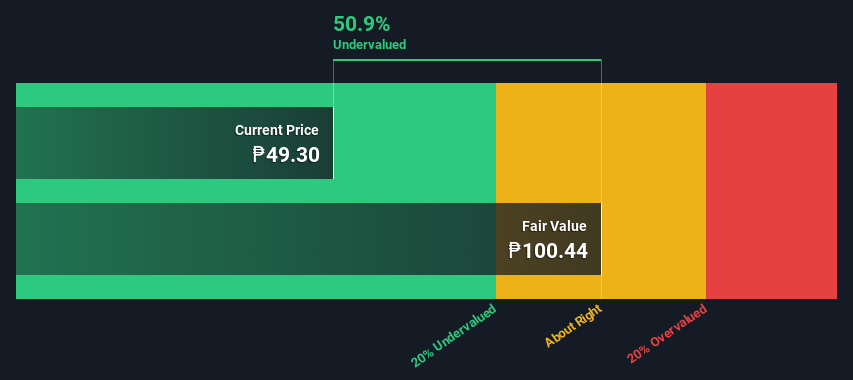
Overview: Philippine National Bank is a financial institution engaged in retail and corporate banking, treasury operations, and other financial services, with a market capitalization of ₱50.02 billion.
Operations: The bank generates revenue primarily from retail banking, treasury operations, and corporate banking, with retail banking contributing the highest at ₱29.76 billion. Operating expenses are significant, with general and administrative expenses being a major component. The net income margin has seen fluctuations over the periods but reached 40.38% in mid-2026.
PE: 4.3x
Philippine National Bank, a smaller player in the Asian financial sector, is drawing attention due to its potential for growth despite challenges. The bank reported a significant increase in net income for Q2 2026, reaching PHP 8.2 billion from PHP 6.4 billion the previous year, showcasing resilience amid high bad loans at 5.1% and low allowance coverage of 82%. Recent leadership changes aim to bolster their tech and international banking capabilities, reflecting strategic shifts to enhance operations and address industry demands.
- Take a closer look at Philippine National Bank's potential here in our valuation report.
Assess Philippine National Bank's past performance with our detailed historical performance reports.
Shougang Fushan Resources Group (SEHK:639)
Simply Wall St Value Rating: ★★★★☆☆
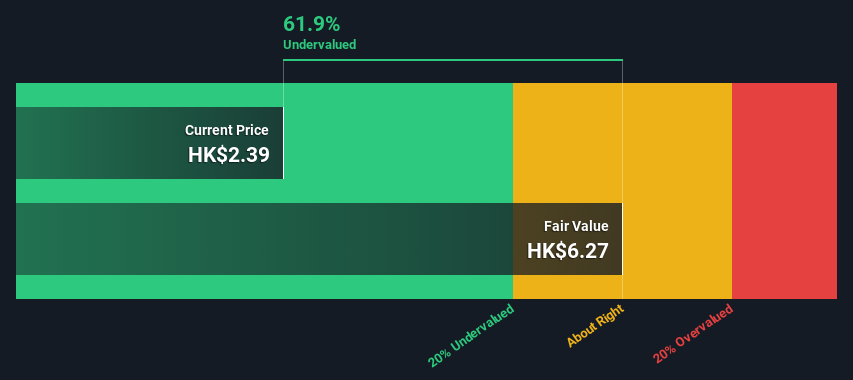
Overview: Shougang Fushan Resources Group is engaged in coking coal mining operations and has a market capitalization of approximately HK$10.89 billion.
Operations: The primary revenue stream is from coking coal mining, with the latest reported revenue at HK$6.20 billion. The gross profit margin has shown fluctuations, currently standing at 25.25%. Operating expenses are a significant cost component, with general and administrative expenses being notable within this category.
PE: 17.4x
Shougang Fushan Resources Group, a small player in the Asian market, recently reported impressive half-year sales of HK$3.24 billion, up from HK$2.1 billion last year, with net income climbing to HK$588.65 million from HK$404.14 million. Despite lower profit margins at 13.2% compared to 22.5% previously, insider confidence is evident with recent share purchases by executives in August 2026, suggesting belief in future growth potential under new leadership by Li Meng who brings extensive industry experience and strategic vision for operational efficiency enhancement and sustained development.
Seize The Opportunity
- Take a closer look at our Undervalued Asian Small Caps With Insider Buying list of 52 companies by clicking here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com