
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asian Growth Companies With Significant Insider Ownership
In recent weeks, Asian markets have shown mixed performance, with some regions experiencing volatility due to fluctuating oil prices and geopolitical tensions. Despite these challenges, growth stocks in Asia continue to capture investor interest, particularly those with significant insider ownership which often signals confidence in the company's future prospects. In this environment, companies that exhibit robust growth potential combined with high levels of insider ownership can be attractive as they may align management's interests closely with those of shareholders.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Zhejiang Taotao Vehicles (SZSE:301345) | 27.9% | 30.6% |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
Let's uncover some gems from our specialized screener.
Momenta Global (SEHK:6880)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Momenta Global Limited is a company that provides autonomous driving solutions in China and has a market cap of HK$44.14 billion.
Operations: Momenta Global Limited generates revenue primarily from its Software & Programming segment, amounting to CN¥2.41 billion.
Insider Ownership: 12.5%
Revenue Growth Forecast: 35.1% p.a.
Momenta Global recently completed a HK$5.89 billion IPO, highlighting its growth potential in Asia. Despite reporting a net loss of CNY 3.46 billion for 2025, revenue surged by over 82% year-on-year to CNY 2.41 billion, and future revenue is expected to grow at 35.1% annually, outpacing the Hong Kong market's average growth rate. Analysts project profitability within three years with substantial stock price appreciation potential; however, the company faces challenges like negative equity and share price volatility.
- Get an in-depth perspective on Momenta Global's performance by reading our analyst estimates report here.
- The analysis detailed in our Momenta Global valuation report hints at an inflated share price compared to its estimated value.

Maxscend Microelectronics (SZSE:300782)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Maxscend Microelectronics Company Limited, along with its subsidiaries, focuses on the research, development, production, and sale of radio frequency integrated circuits in China and internationally with a market cap of approximately CN¥43.89 billion.
Operations: Maxscend Microelectronics generates revenue through its research, development, production, and sale of radio frequency integrated circuits both domestically and internationally.
Insider Ownership: 24.9%
Revenue Growth Forecast: 19.1% p.a.
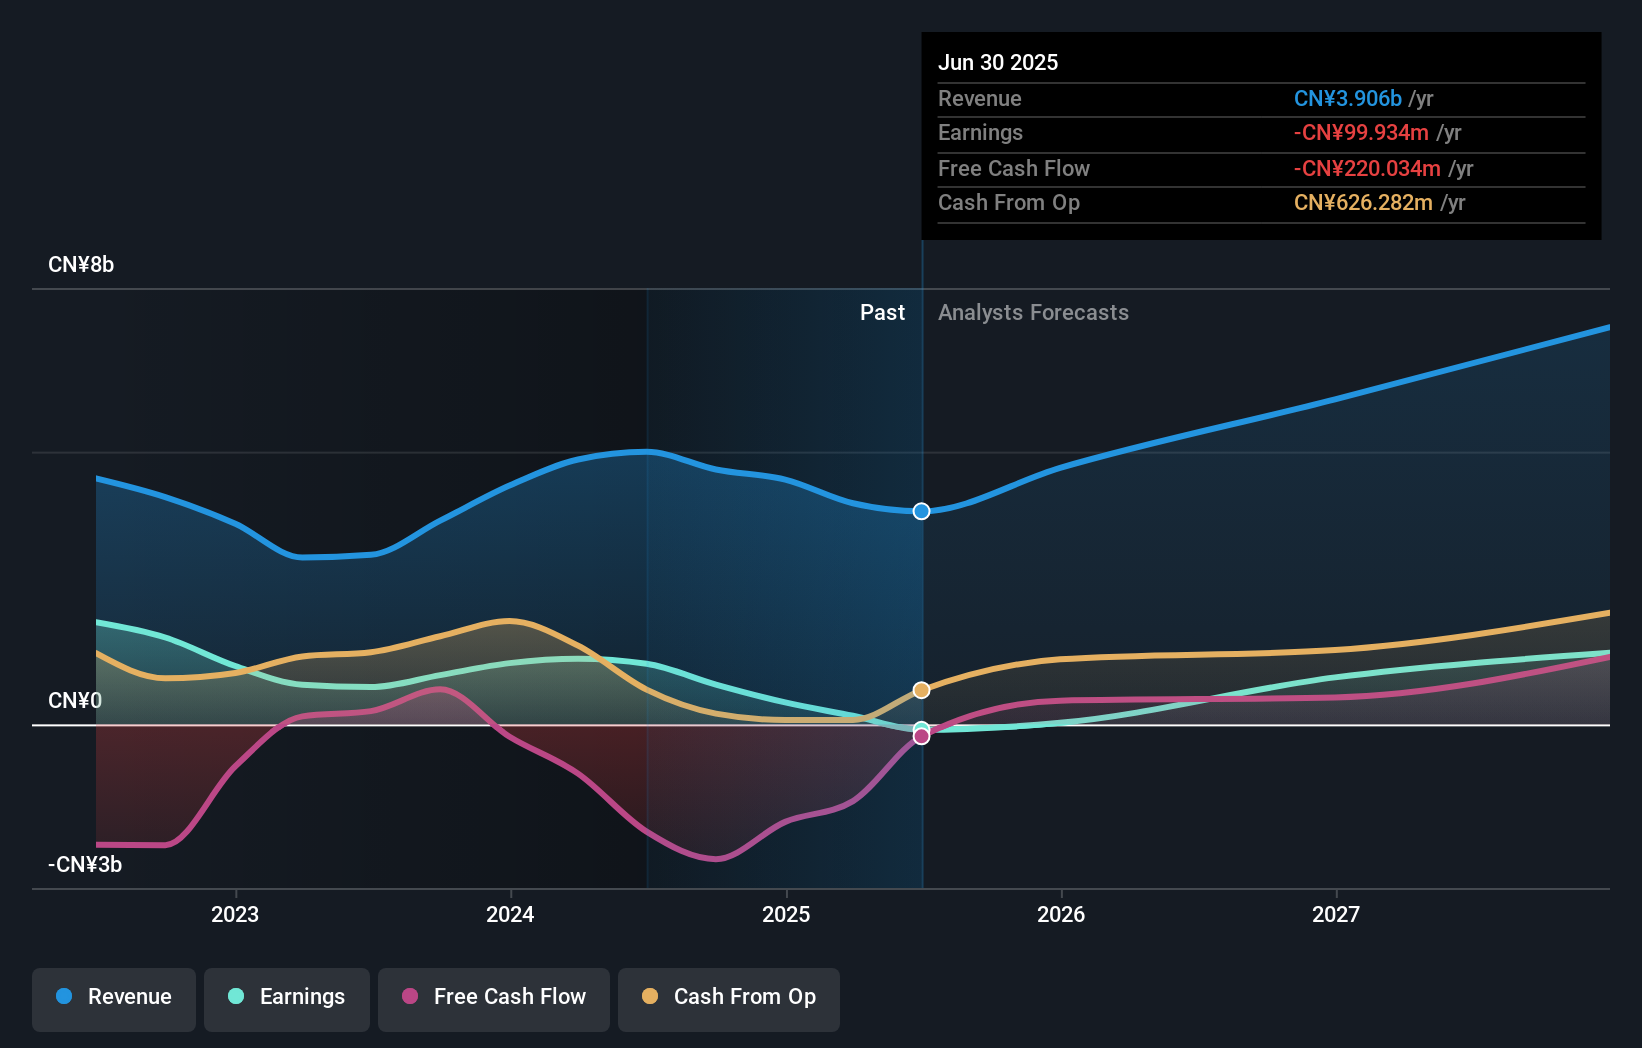
Maxscend Microelectronics is experiencing moderate growth, with revenue expected to increase by 19.1% annually, exceeding the Chinese market average of 17.4%. Despite a net loss of CNY 370.75 million for the first half of 2026, analysts anticipate profitability within three years. Recent board changes and amendments to company bylaws reflect strategic restructuring efforts. High insider ownership aligns management interests with shareholders, although current return on equity forecasts remain low at 6.8% in three years.
- Unlock comprehensive insights into our analysis of Maxscend Microelectronics stock in this growth report.
- Our valuation report here indicates Maxscend Microelectronics may be overvalued.
Phison Electronics (TPEX:8299)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Phison Electronics Corp. designs, manufactures, and sells flash memory controllers and peripheral system applications globally, with a market cap of NT$475.50 billion.
Operations: The company's revenue primarily comes from its Flash Memory Control Chip Design segment, which generated NT$149.79 billion.
Insider Ownership: 10.2%
Revenue Growth Forecast: 25.3% p.a.
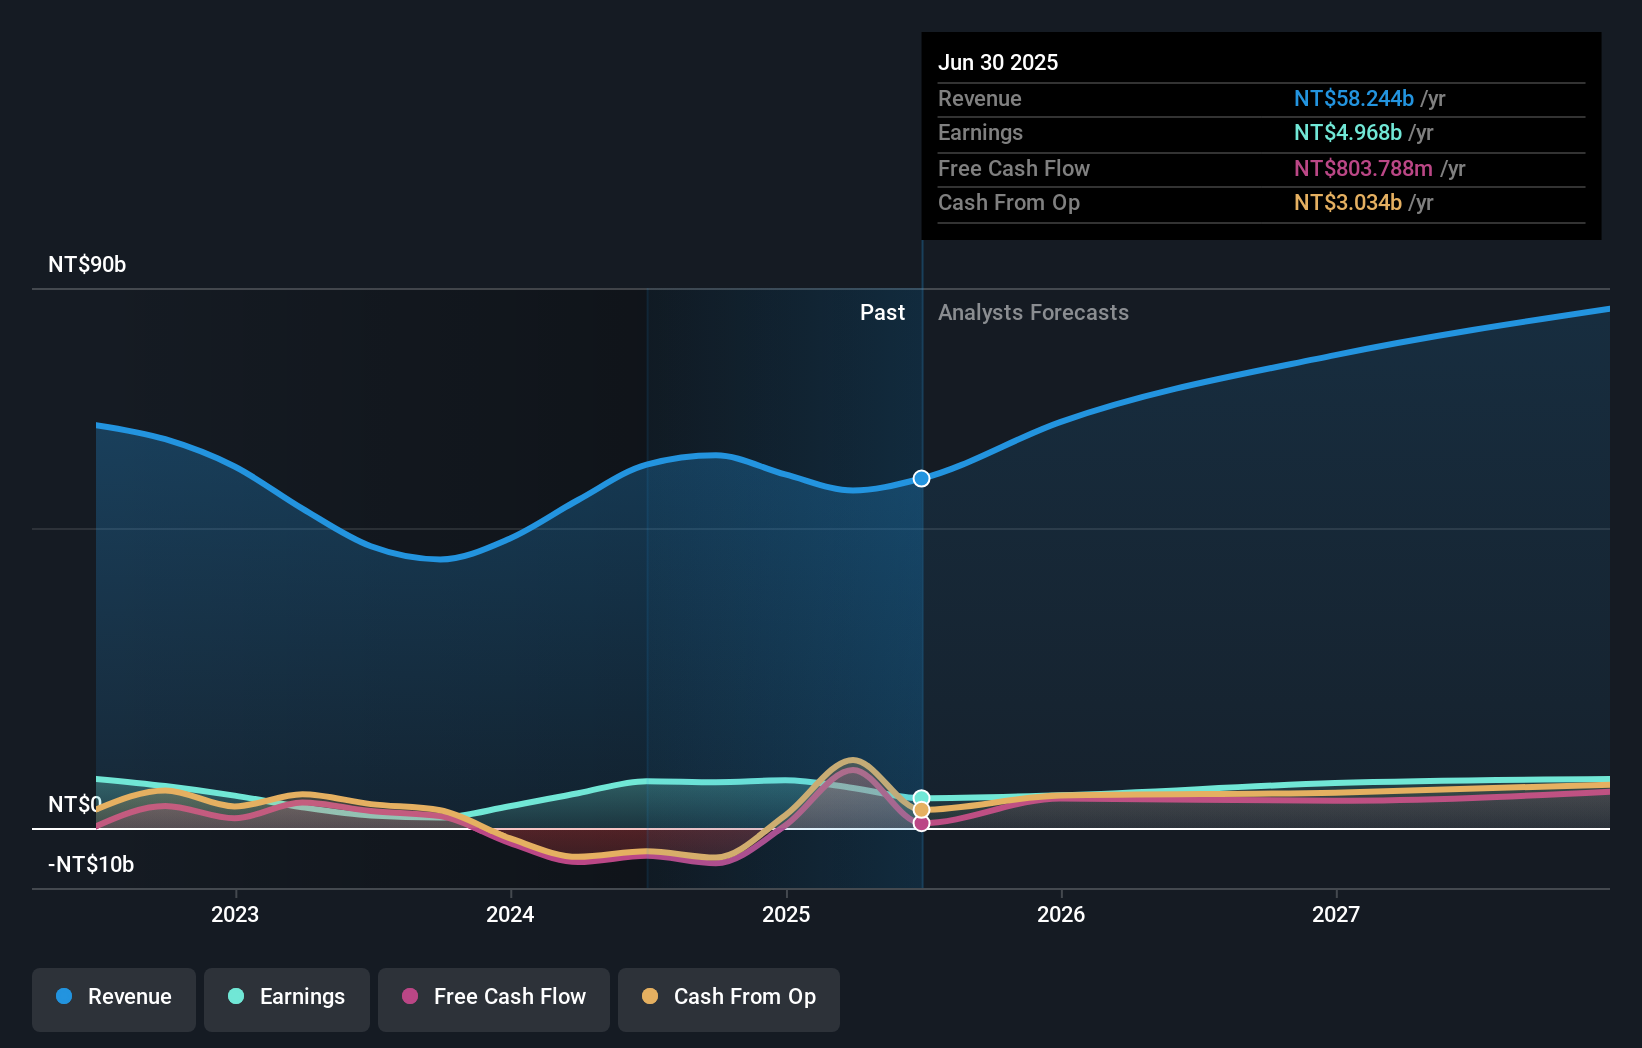
Phison Electronics is expanding its European operations, enhancing its strategic position in AI and enterprise markets. Recent leadership appointments aim to accelerate regional growth. Despite high earnings volatility, Phison reported substantial profit increases recently, with net income reaching TWD 26.22 billion for Q2 2026. Forecasts suggest revenue growth of 25.3% annually, outpacing the Taiwan market average but with slower earnings growth at 1.91%. The stock trades significantly below estimated fair value, indicating potential investment appeal despite high share price volatility.
- Click to explore a detailed breakdown of our findings in Phison Electronics' earnings growth report.
- The analysis detailed in our Phison Electronics valuation report hints at an deflated share price compared to its estimated value.
Turning Ideas Into Actions
- Unlock more gems! Our Fast Growing Asian Companies With High Insider Ownership screener has unearthed 492 more companies for you to explore.Click here to unveil our expertly curated list of 495 Fast Growing Asian Companies With High Insider Ownership.
- Contemplating Other Strategies? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com