
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Cobre Limited (ASX:CBE): Is Breakeven Near?
We feel now is a pretty good time to analyse Cobre Limited's (ASX:CBE) business as it appears the company may be on the cusp of a considerable accomplishment. Cobre Limited engages in the exploration and evaluation of mineral properties in Australia and Botswana. The company’s loss has recently broadened since it announced a AU$2.1m loss in the full financial year, compared to the latest trailing-twelve-month loss of AU$3.1m, moving it further away from breakeven. The most pressing concern for investors is Cobre's path to profitability – when will it breakeven? Below we will provide a high-level summary of the industry analysts’ expectations for the company.
According to some industry analysts covering Cobre, breakeven is near. They anticipate the company to incur a final loss in 2026, before generating positive profits of AU$12m in 2027. So, the company is predicted to breakeven just over a year from today. How fast will the company have to grow each year in order to reach the breakeven point by 2027? Working backwards from analyst estimates, it turns out that they expect the company to grow 63% year-on-year, on average, which is extremely buoyant. Should the business grow at a slower rate, it will become profitable at a later date than expected.
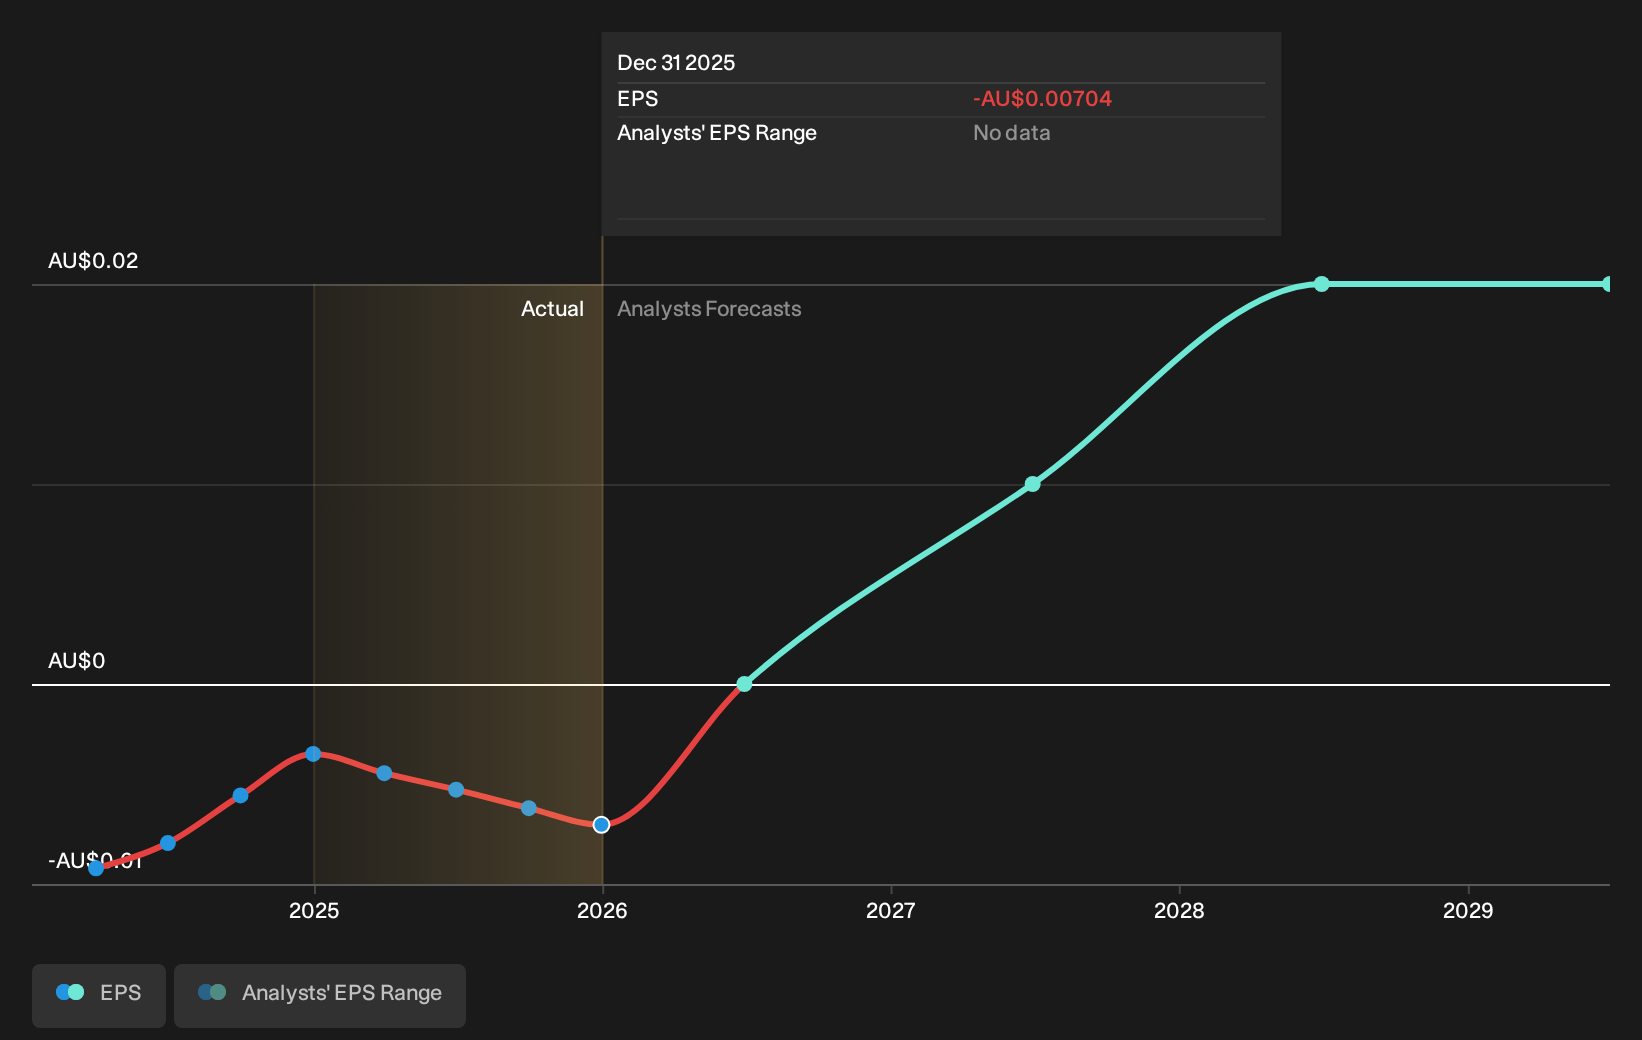
We're not going to go through company-specific developments for Cobre given that this is a high-level summary, but, bear in mind that generally a metal and mining business has lumpy cash flows which are contingent on the natural resource mined and stage at which the company is operating. This means that a high growth rate is not unusual, especially if the company is currently in an investment period.
See our latest analysis for Cobre
Before we wrap up, there’s one aspect worth mentioning. Cobre currently has no debt on its balance sheet, which is rare for a loss-making metals and mining company, which typically has high debt relative to its equity. The company currently operates purely off its shareholder funding and has no debt obligation, reducing concerns around repayments and making it a less risky investment.
Next Steps:
This article is not intended to be a comprehensive analysis on Cobre, so if you are interested in understanding the company at a deeper level, take a look at Cobre's company page on Simply Wall St. We've also compiled a list of pertinent aspects you should look at:
- Historical Track Record: What has Cobre's performance been like over the past? Go into more detail in the past track record analysis and take a look at the free visual representations of our analysis for more clarity.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Cobre's board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.