
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Index Removal Change Brilliance China Automotive Holdings' (SEHK:1114) Narrative
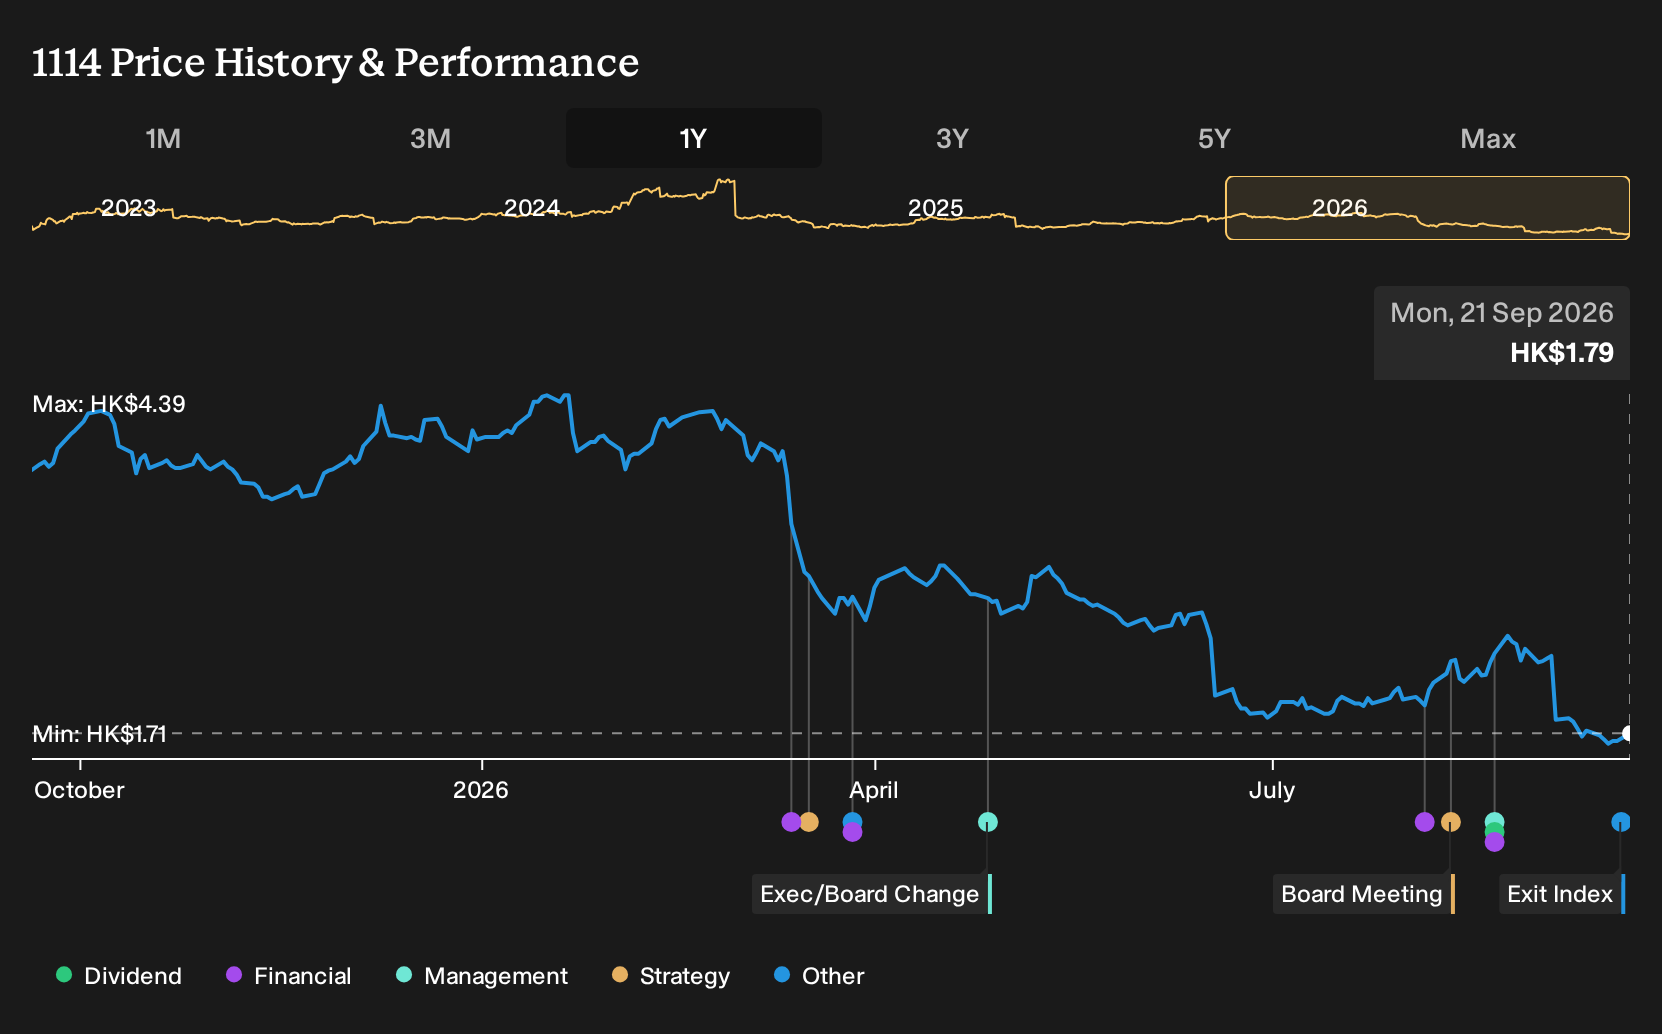
- Brilliance China Automotive Holdings was removed from the FTSE All-World Index after the latest review, an index change that occurred before 21 September 2026 and directly affects its inclusion in many global equity benchmarks.
- This exit from a widely tracked index can matter for Brilliance China Automotive Holdings because passive funds linked to that benchmark may need to rebalance, which can influence liquidity and the investor mix around the stock.
- We will now look at how Brilliance China Automotive Holdings' investment narrative could be influenced by its removal from the FTSE All-World Index.
Compare how Brilliance China Automotive Holdings' index exit stacks up against other globally listed businesses that may be off the radar but still feature in our 615 high quality undiscovered gems.
What Is Brilliance China Automotive Holdings' Investment Narrative?
For Brilliance China Automotive Holdings, the core belief is about execution in a tough auto market. The group leans heavily on its manufacturing partnership for BMW vehicles and components, plus a smaller non BMW and auto financing footprint. That mix relies on steady demand, disciplined pricing and ongoing capital spend to keep plants and product lines competitive. Earnings are forecast to grow 13.73% per year while revenue is expected to rise 3.1% per year, so the story hinges on profit quality more than rapid top line expansion.
The recent drop from the FTSE All World Index mainly affects who owns the stock, not how many cars roll off the line or how financing books perform. It can still matter at the margin through liquidity and short term price pressure, especially after the share price fell 25.6% over 30 days and is down 56% year to date. Big near term swing factors remain profit sustainability, given margins have softened versus last year, and a dividend yield of 27.93% that is not well covered by earnings or free cash flow.
That said, the one issue that could really change the story around Brilliance China Automotive Holdings over the next few years is...
There's only one way to know the right time to buy, sell or hold Brilliance China Automotive Holdings. Head to Simply Wall St's company report for the latest analysis of Brilliance China Automotive Holdings's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Brilliance China Automotive Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Brilliance China Automotive Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brilliance China Automotive Holdings' overall financial health at a glance.
Looking For More Brilliance China Automotive Holdings Investment Ideas?
If Brilliance China Automotive Holdings is on your radar, it can help to compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors hunting for potential upside in smaller stocks, review 139 elite penny stocks with strong financials that already show robust financials instead of just stories.
- If resilience matters more than excitement for your portfolio, filter for companies in the 229 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- For those who want income without ignoring fundamentals, sort through the 159 dividend fortresses that combine payout potential with financial discipline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com