
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
China Zheshang Bank (SEHK:2016) Could Be 64% Below Fair Value On XTransfer Deal
XTransfer’s new cooperation with China Zheshang Bank (SEHK:2016) on all currency settlement and minor currency collection puts cross border payment plumbing at center stage for anyone tracking the stock.
The cooperation lands while China Zheshang Bank’s 30 day share price return of 6.78% and 90 day share price return of 6.09% point to improving short term momentum, even though the year to date share price return declined 3.56% and the 1 year total shareholder return declined 1.48%. This compares with a much stronger 46.25% total shareholder return over three years that hints at a longer running rerating story.
Compare China Zheshang Bank’s cross border momentum with a curated group of trade linked financials by scanning the list of solid balance sheet and fundamentals (198 results) that is shaping global capital flows.
China Zheshang Bank now trades at a sizeable discount to both intrinsic estimates and analyst targets after this cross border push. Is that pricing in real risk, or giving you more caution than the recent share move justifies?
Preferred Multiple of 4.7x P/E: Is it justified?
Valuation on China Zheshang Bank currently leans on a low earnings multiple, with the stock at HK$2.44 and sitting on a 4.7x P/E while still trading below both internal fair value estimates and analyst targets. For anyone watching the XTransfer agreement as a potential driver, that gap between earnings pricing and recent share momentum is where the debate really starts.
The P/E ratio compares the share price with annual earnings per share, which gives a quick read on how much investors are willing to pay for each unit of profit. For a bank like China Zheshang Bank, this is a common yardstick because the business model is relatively mature, earnings are a key focus, and balance sheet size alone does not tell you much about return potential.
China Zheshang Bank is described as good value on this measure, both relative to the Hong Kong Banks industry average P/E of 5.2x and an even higher peer average of 9.7x. That kind of discount often suggests the market is assigning a lower confidence level to future profitability or is reacting to factors such as its 6.5% Return on Equity and a recent year where earnings declined 12.7% even though five year earnings growth averaged 2.1% per year and profit quality is assessed as high.
Compared with the wider Hong Kong Banks group, the 4.7x P/E is firmly on the cheaper side rather than in line with the pack. This is a notable relative gap for a lender that still reports HK$12,125.0 in net income on HK$38,636.0 of revenue. That sets up a clear valuation spread that investors will weigh against issues like lower recent net profit margins, described as falling from 35.5% to 31.4%, and an unstable dividend track record.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 4.7x (UNDERVALUED)
Still, pressure on net profit margins and an unstable dividend record could quickly challenge the idea that China Zheshang Bank deserves a higher earnings multiple.
Find out about the key risks to this China Zheshang Bank narrative.
Another View on China Zheshang Bank’s Value
The P/E story paints China Zheshang Bank as cheap, yet the SWS DCF model points to something starker. At HK$2.44, the stock sits below an estimated future cash flow value of HK$6.76, which indicates a larger discount than earnings multiples alone suggest.
If earnings based pricing and a cash flow driven fair value are both this generous, the key question is what might close that gap, and on what timeline.
Look into how the SWS DCF model arrives at its fair value.
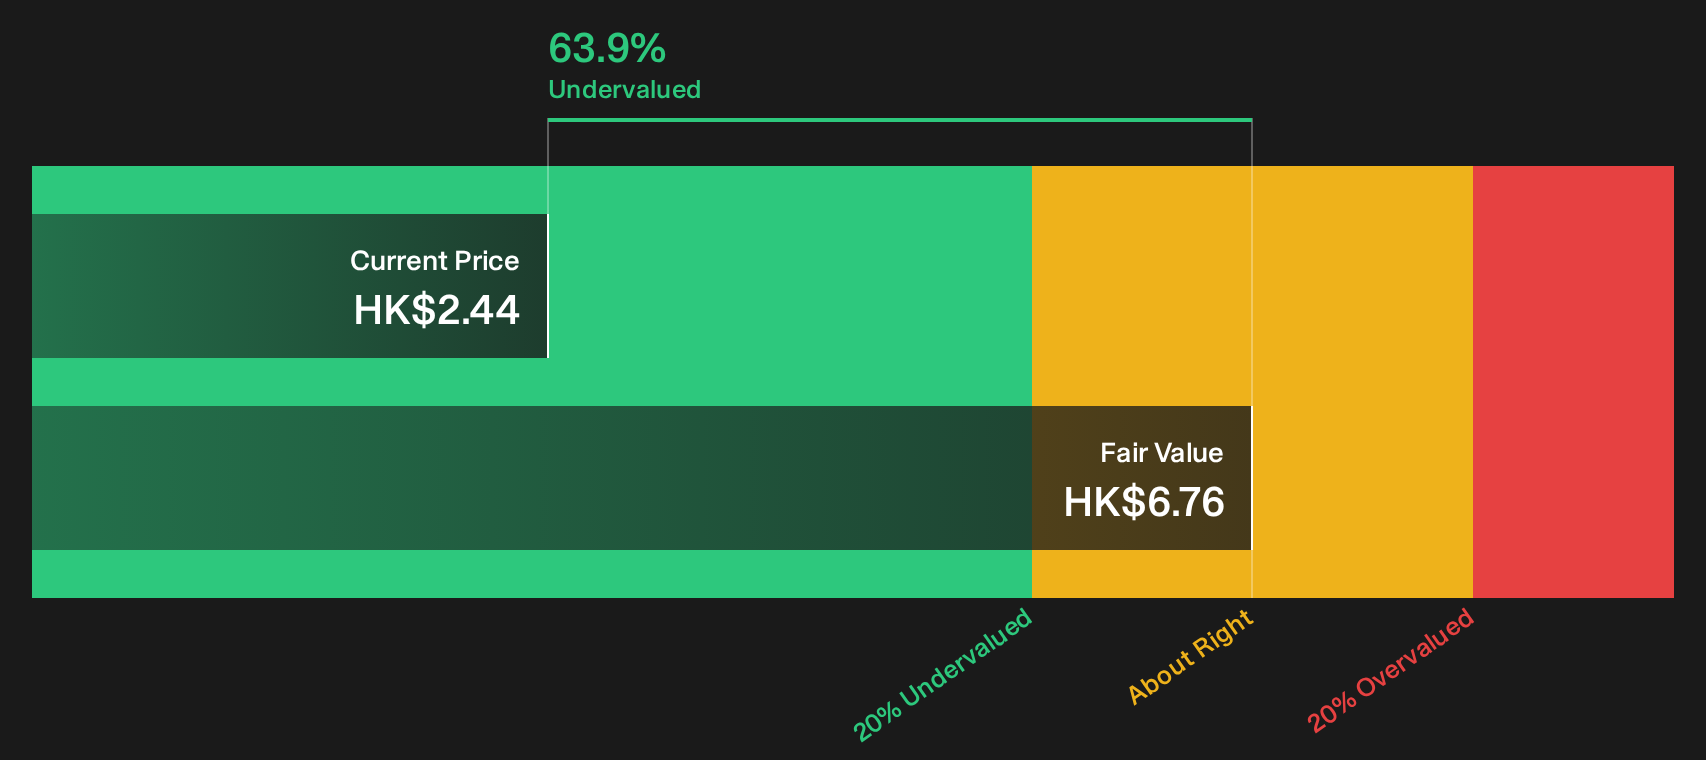
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Zheshang Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether this mix of discount, momentum, and cross border news around China Zheshang Bank justifies the current narrative or not? Move quickly from headline impressions to your own conclusions by weighing both sides of the story through the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond China Zheshang Bank?
If China Zheshang Bank has sharpened your interest in value and risk, it makes sense to widen the net before you commit fresh capital.
- Target potential bargains by scanning the 179 high quality undervalued stocks that pairs solid fundamentals with prices that may not fully reflect them yet.
- Strengthen your income focus by reviewing the 159 dividend fortresses that concentrates on higher yielding payers with robust cash generation.
- Reduce downside surprises by filtering for the 229 resilient stocks with low risk scores that highlights businesses with more resilient risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com