
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CK Asset Holdings (SEHK:1113) Could Be 14% Undervalued After Settling At HK$46
CK Asset Holdings (SEHK:1113) has attracted fresh attention after its recent close at HK$46. The move comes against a backdrop of mixed short term returns and double digit gains over the past year.
Short term momentum for CK Asset Holdings has cooled, with the share price down over the past week and month. However, the 90 day share price return remains in positive territory and a 1 year total shareholder return of 29.92% still point to stronger longer term gains.
Scan beyond CK Asset Holdings and compare its recent run to a curated group of real estate and income plays using our 159 dividend fortresses as a starting universe.
After CK Asset Holdings cooled from its recent run and settled at HK$46, the real puzzle is simple. Does it make sense to commit at this level, or wait for a clearer valuation cushion to open up?
Most Popular Narrative: 14% Undervalued
On the most followed view, CK Asset Holdings screens below an estimated fair value of HK$53.45, compared with the recent HK$46 close. That gap rests heavily on how investors weigh its recurring income mix against pressure in core property markets.
CK Asset's increasing mix of recurring income (81% of revenue and 83% of profit are now recurring), anchored in rental properties, infrastructure, utilities, and pub operations, underpins steady net margins and provides a foundation for stable or rising dividend payouts, reducing volatility in overall earnings.
See why 9 investors see CK Asset Holdings as 14% undervalued.
Result: Fair Value of HK$53.45 (UNDERVALUED)
Still, the narrative around CK Asset Holdings can unravel quickly if Hong Kong office oversupply lingers or if Mainland China property weakness continues to drag on rental and development earnings.
Find out about the key risks to this CK Asset Holdings narrative.
Another View: CK Asset Holdings On Earnings Multiples
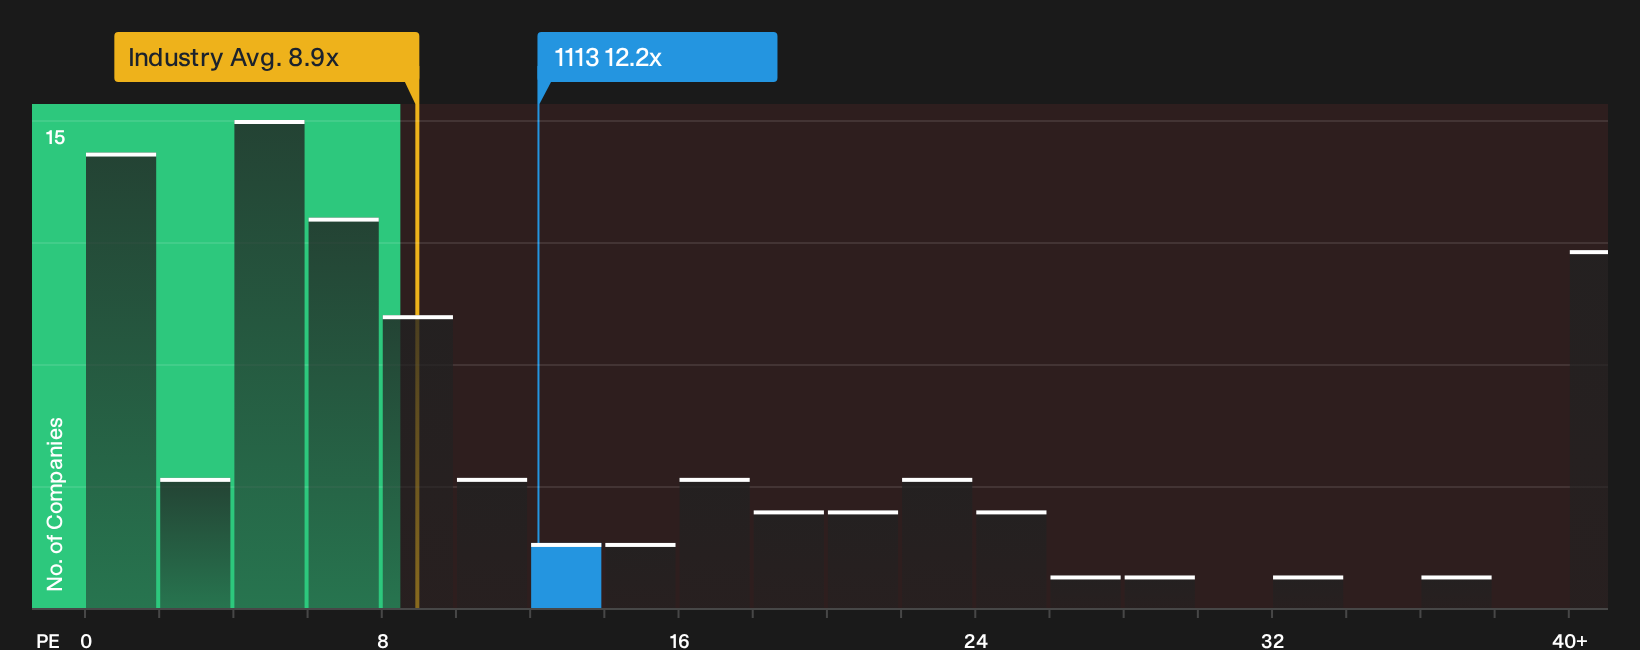
That 14% undervalued story hinges on future cash flows and analyst targets. A different lens looks much closer to earth. On a P/E of 12.2x, CK Asset Holdings trades above the Hong Kong Real Estate sector on 8.9x, yet below peer averages at 14.5x and a fair ratio of 13.5x.
In practical terms, the share trades richer than the broader property group but a touch cheaper than similar stocks and the fair ratio the market could move towards. Does that signal a reasonable margin of safety around HK$46, or a tighter risk cushion than the 14% undervaluation suggests?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CK Asset Holdings so far and it is not clear which side carries more weight. Move quickly, pull up the detailed risk and reward breakdown, and weigh the 2 key rewards and 1 important warning sign.
Looking for more CK Asset Holdings style ideas?
If CK Asset Holdings has your attention, do not stop here. Broader opportunity sits in the wider market, and you risk missing it if you stay focused on one ticker.
- Target quality at a discount by scanning companies that combine solid fundamentals with room for re rating via the 179 high quality undervalued stocks.
- Prioritise resilience and reduce blow up risk by focusing on businesses with sturdier finances using the list of solid balance sheet and fundamentals (198 results).
- Hunt for earlier stage stories with cleaner balance sheets and real potential before the crowd pays attention by checking the 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com