
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Stocks Estimated To Be Up To 50% Below Intrinsic Value
The market has been flat over the last week but is up 12% over the past year, with earnings expected to grow by 17% per annum in the coming years. In this environment, identifying stocks that are trading below their intrinsic value can offer potential opportunities for investors seeking to capitalize on future growth prospects.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valley National Bancorp (VLY) | $13.59 | $27.10 | 49.8% |
| UiPath (PATH) | $13.39 | $25.15 | 46.8% |
| Pegasystems (PEGA) | $35.05 | $69.25 | 49.4% |
| Futu Holdings (FUTU) | $112.01 | $209.63 | 46.6% |
| Civista Bancshares (CIVB) | $27.29 | $53.11 | 48.6% |
| Chagee Holdings (CHA) | $12.02 | $22.61 | 46.8% |
| Capital Bancorp (CBNK) | $35.87 | $66.89 | 46.4% |
| Best Buy (BBY) | $92.85 | $185.63 | 50% |
| Autodesk (ADSK) | $216.95 | $414.02 | 47.6% |
| Addus HomeCare (ADUS) | $117.07 | $226.18 | 48.2% |
Let's take a closer look at a couple of our picks from the screened companies.
UMB Financial (UMBF)
Overview: UMB Financial Corporation is a bank holding company offering banking services and asset servicing both in the United States and internationally, with a market cap of $10.22 billion.
Operations: UMB Financial Corporation's revenue is primarily derived from Commercial Banking at $1.53 billion, followed by Institutional Banking (including Healthcare Services) at $768.79 million, and Personal Banking at $515.17 million.
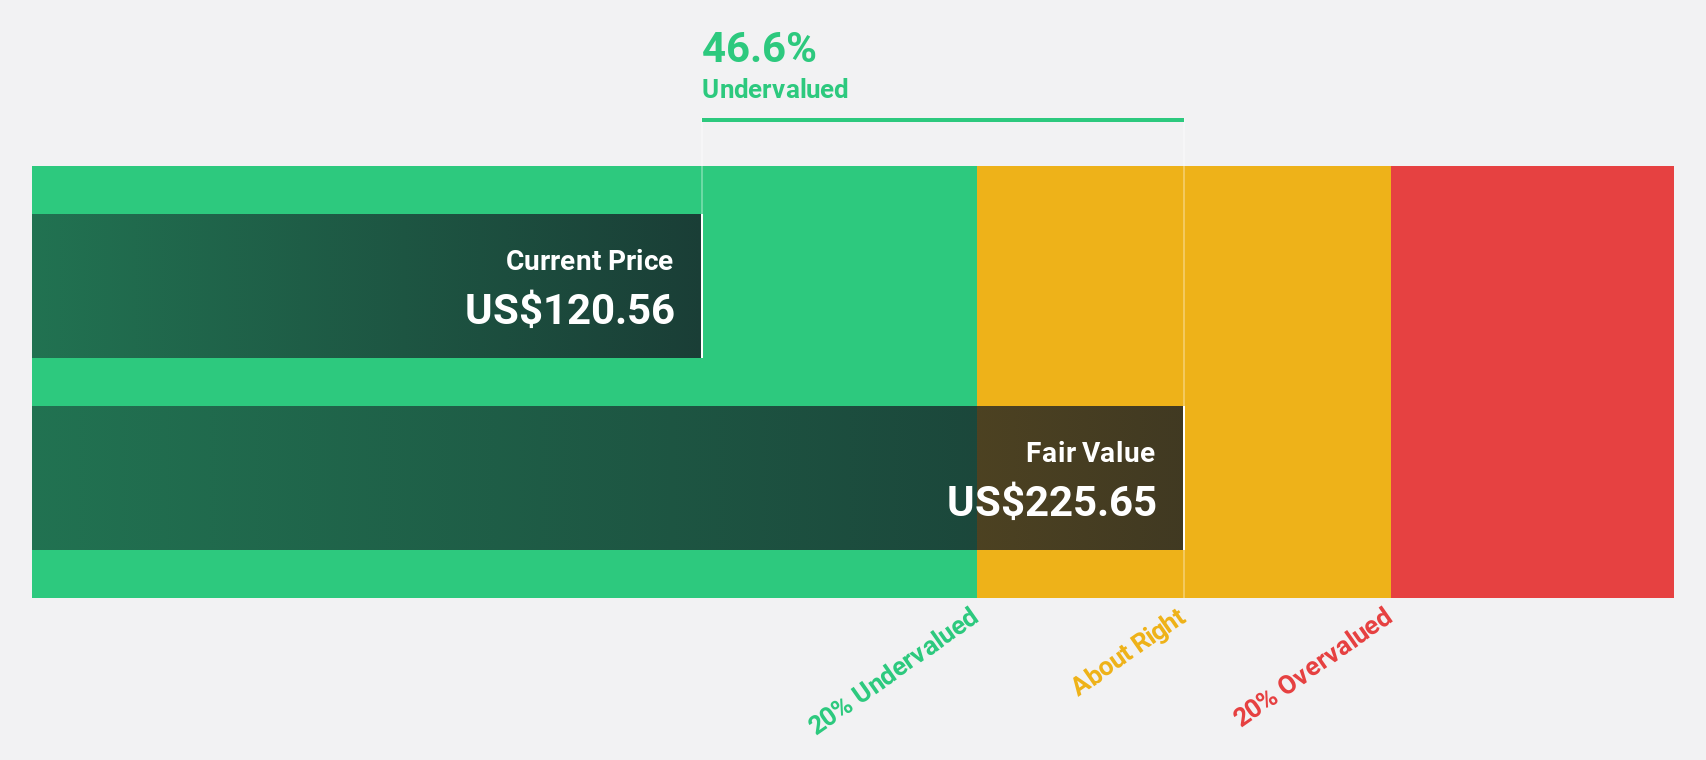
Estimated Discount To Fair Value: 43.3%
UMB Financial's recent earnings report shows strong growth, with net income rising to US$277.57 million in Q2 2026 from US$217.39 million a year ago, while trading at US$134.52, significantly below its estimated cash flow value of US$237.1. Despite insider selling and slower revenue growth forecasts compared to the market, UMB remains attractive due to its substantial undervaluation based on discounted cash flow analysis and reliable dividend yield of 1.49%.
- Our comprehensive growth report raises the possibility that UMB Financial is poised for substantial financial growth.
- Take a closer look at UMB Financial's balance sheet health here in our report.
Best Buy (BBY)
Overview: Best Buy Co., Inc. is a retailer providing technology products and solutions across the United States, Canada, and internationally, with a market cap of approximately $19.47 billion.
Operations: The company's revenue is primarily derived from its Domestic segment, which accounts for $38.77 billion, while the International segment contributes $3.43 billion.
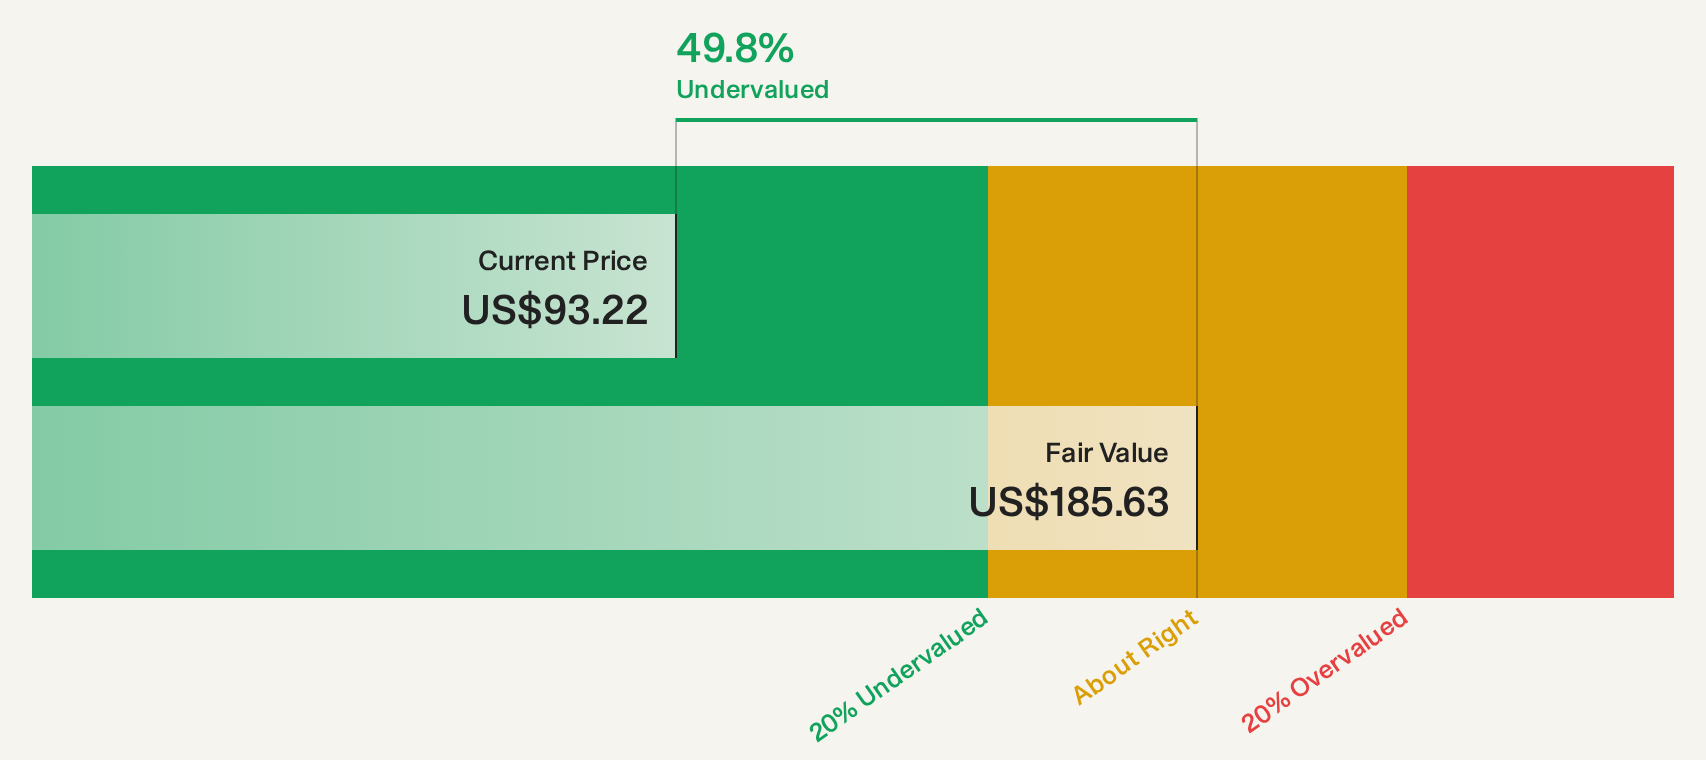
Estimated Discount To Fair Value: 50%
Best Buy's recent earnings report highlights a net income increase to US$315 million for Q2 2026, up from US$186 million the previous year. Trading at US$92.85, it is significantly below its estimated cash flow value of US$185.63, indicating substantial undervaluation based on discounted cash flow analysis. Despite slower revenue growth forecasts and insider selling, Best Buy offers good relative value in its industry and maintains a reliable dividend yield of 4.14%.
- Upon reviewing our latest growth report, Best Buy's projected financial performance appears quite optimistic.
- Dive into the specifics of Best Buy here with our thorough financial health report.
Evercore (EVR)
Overview: Evercore Inc. is an independent investment banking firm operating across the Americas, Europe, the Middle East, Africa, and Asia-Pacific with a market cap of approximately $10.78 billion.
Operations: The company generates revenue primarily from its Investment Banking & Equities segment, which accounts for $4.62 billion, and its Investment Management segment, contributing $92.36 million.
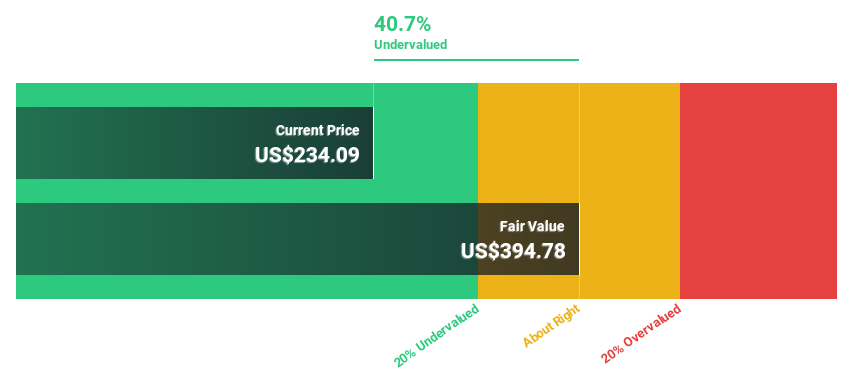
Estimated Discount To Fair Value: 37.8%
Evercore is trading at US$262.6, significantly below its estimated future cash flow value of US$422.48, reflecting substantial undervaluation. Despite modest earnings growth forecasts and slower revenue expansion compared to the market, Evercore's robust return on equity forecast and recent strategic hires in healthcare and industrials sectors bolster its competitive positioning. The company reported strong six-month revenue growth to US$2.4 billion from US$1.54 billion a year ago, demonstrating operational resilience amidst industry challenges.
- Our expertly prepared growth report on Evercore implies its future financial outlook may be stronger than recent results.
- Click here to discover the nuances of Evercore with our detailed financial health report.
Make It Happen
- Investigate our full lineup of 48 Undervalued US Stocks Based On Cash Flows right here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com