
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rocket Stock And Other Mortgage Lenders That Could Gain If Rates Ease
When the U.S. Treasury steps in to buy long‑dated bonds and tries to pin down borrowing costs, the ripple effects reach far beyond Washington. Mortgage rates, housing demand, and the pricing power of lenders can all shift. That creates a window where some interest‑rate‑sensitive stocks may benefit more than others. This article walks through 3 stocks exposed to this news and explains why each could matter for your portfolio decisions.
The three stocks below are just a starting sample, and the full screen surfaced 14 more U.S. housing and mortgage lenders with equally compelling narratives that are not covered here.
Identify and analyze your own shortlist of interest rate sensitive lenders by going straight to the U.S. interest‑rate‑sensitive housing and mortgage lenders screener.
Hovnanian Enterprises (HOV)
Overview: Hovnanian Enterprises is a U.S. homebuilder that designs and sells a wide range of residential communities, closely tied to mortgage-driven housing affordability.
Operations: Hovnanian generates about US$2.8b in U.S. revenue, led by West homebuilding at roughly US$1.3b, Northeast at about US$1.0b, Southeast at about US$360m, plus around US$94m from financial services.
Market Cap: US$666 million
Hovnanian Enterprises operates at the intersection of new home construction and mortgage access. Any shift in long-term Treasury yields can quickly filter through to demand, incentives, and pricing power for its communities.
"High mortgage rates, affordability challenges, and reliance on incentives may constrain demand and pressure both revenues and margins."
The key question is how one unresolved pressure around its funding and rate exposure ultimately affects that already thin profitability base.
That pressure point is exactly where the full narrative for Hovnanian Enterprises shows how funding costs, incentives and demand could be decoupling in ways the headline numbers miss.

UWM Holdings (UWMC)
Overview: UWM Holdings is a U.S. wholesale-focused residential mortgage lender that originates, sells, and services home loans closely tied to long-term mortgage rates.
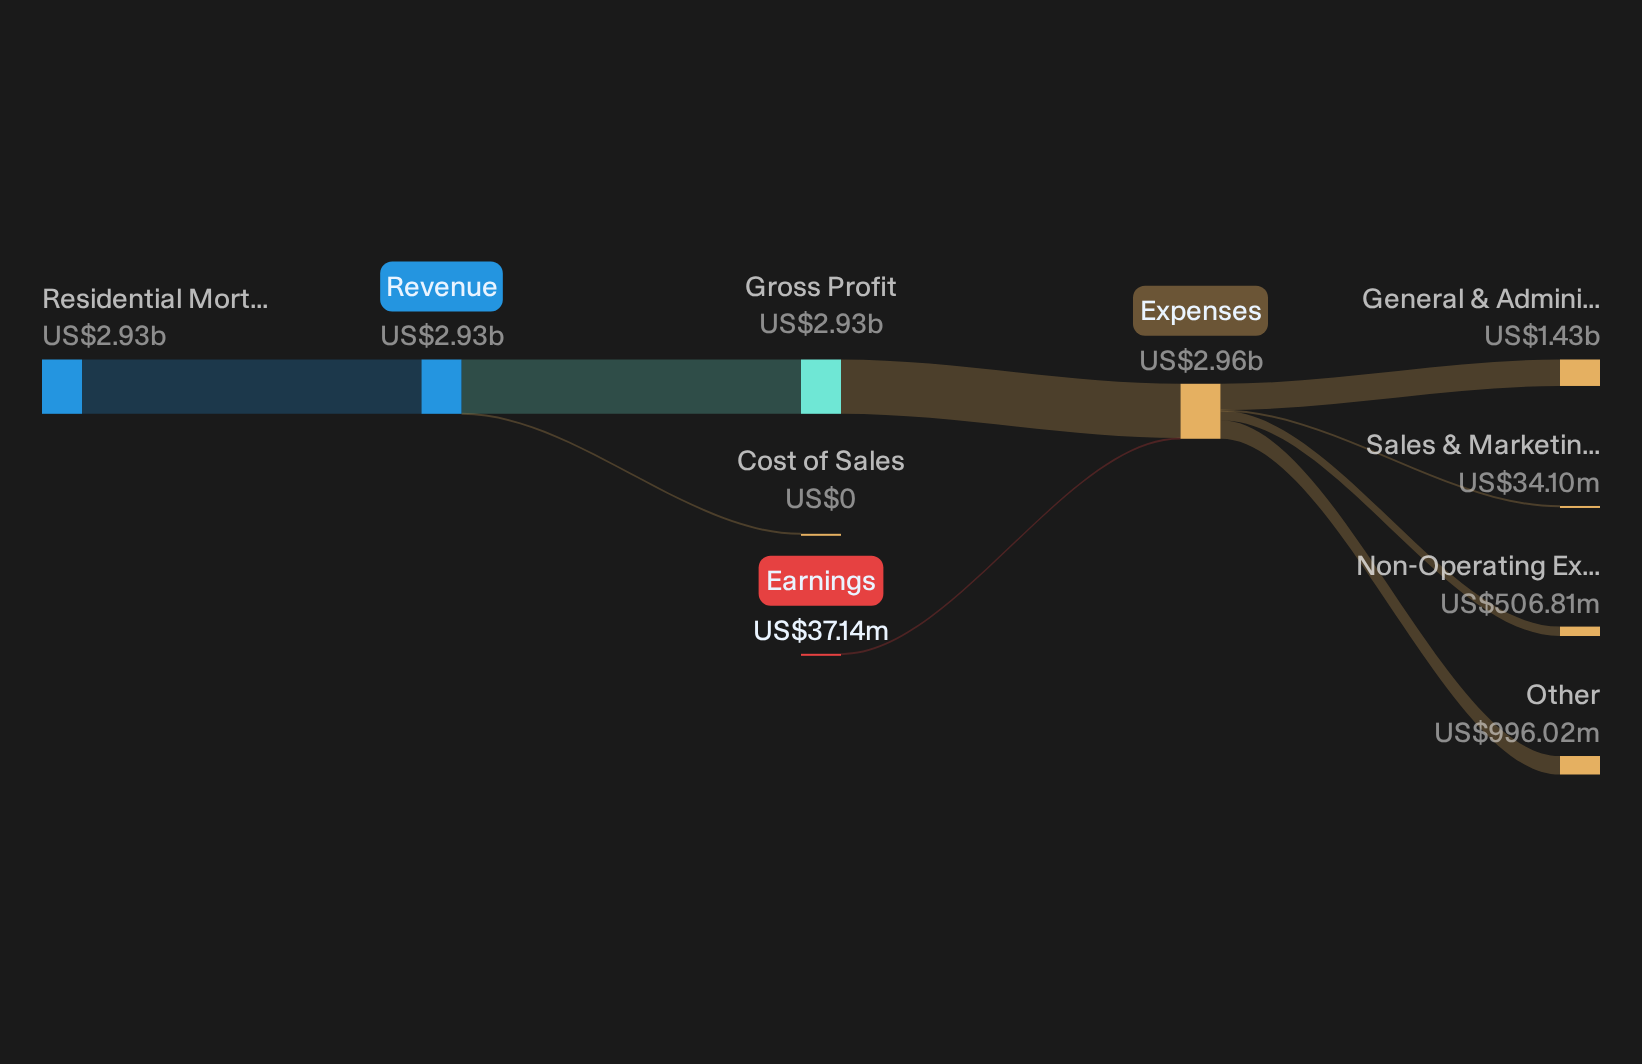
Operations: UWM Holdings generates about US$2.9b in revenue from residential mortgage loans exclusively through its U.S. wholesale channel, fully concentrated domestically.
Market Cap: US$2.0b
UWM Holdings sits right in the slipstream of the screener theme, with every turn in long-term Treasury yields feeding directly into refinancing appetite, purchase volumes, and the economics of its wholesale broker network.
"Continued investment and deployment of advanced AI tools (like BOLT, ChatUWM, LEO, and Mia) are described as materially increasing broker productivity, efficiency, and borrower retention. This is presented as providing UWM with lower unit costs and the ability to handle higher loan volumes without a proportional increase in costs, which the company positions as supportive of its long-term revenue and margin objectives."
What are the implications for those margin objectives if pressures on funding costs and capital buffers ease more slowly than anticipated?
If that funding squeeze is the real swing factor, the full narrative for UWM Holdings shows where UWM Holdings’ AI tools may accelerate advantages while weaker lenders stall.
Rocket Companies (RKT)
Overview: Rocket Companies runs a large U.S. and Canadian digital platform for mortgage origination, servicing, real estate search, and consumer finance tools.
Operations: Rocket Companies records about US$10.2b of revenue, with US$10.2b generated in the United States and US$1.8b classified as other segment activity.
Market Cap: US$34.8b
Rocket Companies sits at the sharp end of this screener theme because its mortgage volumes, refinancing activity, and gain on sale economics all respond quickly when long-term Treasury yields and home loan rates move.
"Rocket's heavy investments in proprietary AI and automation are demonstrably lowering origination and operating costs, increasing capacity and productivity, and creating durable improvements in operational leverage, which directly supports improved margins and earnings scalability."
The real swing factor is what happens if one pressure on its funding costs and capital flexibility shifts just as mortgage demand reaccelerates.
If that inflection point matters to you, read the full narrative for Rocket Companies to see how Rocket Companies’ AI engine could turn a rate shift into accelerating earnings power.

Seeking Fresh Alternatives Before Others?
Market narratives move fast. Stock themes catch momentum, then cool off once the crowd piles in. Scan fresh ideas while they are still under the radar for now and get in early.
- Hunt for resilient cash generators by running the list of solid balance sheet and fundamentals (23 results) that highlights businesses with stronger finances than their peers, before the wider market catches on.
- Target income opportunities by reviewing the 7 dividend fortresses that filters for high-yield payers with sturdier profiles while prices and yields still look appealing.
- Position ahead of the next infrastructure breakout using the 39 power grid technology and infrastructure stocks that spotlights grid and energy technology players before attention and trading volumes start rising.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com