
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Great Indian Dividend Stocks To Own In September 2026
Central banks are lifting interest rates to cool sticky inflation, and that shift is putting income front and center for many Indian investors. Cash in the bank now pays something, yet inflation still chips away at purchasing power. Reliable high yielders can help bridge that gap. This article zeroes in on three Indian dividend stocks offering 3%+ yields with coverage and stability filters already applied.
The stocks covered below are just a small sample, and the full Dividend Powerhouses screen surfaced 44 more companies with similar income potential and different stories that are not included here. To go straight to the source, use the Dividend Powerhouses (3%+ Yield) screener to identify, analyze, and focus on the highest conviction dividend ideas for your portfolio.
Emami (BSE:531162)
Emami is a pure-play personal and healthcare products group, and its cash-generative brands are exactly the kind of engine this dividend screen looks for.
Emami generates about ₹39.1b in revenue from personal and healthcare lines like BoroPlus, Zandu, Navratna and Kesh King, with most sales in India and more abroad, and the stock is valued at roughly ₹160.8b.
"The ongoing migration of Indian consumers from unbranded to branded and premium wellness/personal care products, combined with Emami's deep heritage in Ayurveda and natural offerings, is described by some analysts as a factor that could help the company benefit from growing health and wellness awareness and premiumization. They also highlight this as a potential support for sustained gross margin expansion and higher average realization per unit."
The real test for Emami’s dividend story is how one quiet shift in its product mix ultimately filters through to margins and cash.
To see how that mix shift could reshape Emami’s cash story, read the full narrative for Emami and see where brand strength may be masking bigger shifts ahead.

Bhansali Engineering Polymers (BSE:500052)
Bhansali Engineering Polymers manufactures ABS, SAN and related thermoplastic resins used in autos, appliances and electronics. Its dividend is backed primarily by ₹14,402 million in resin manufacturing revenue rather than trading income, and the stock is valued at about ₹32.1b.
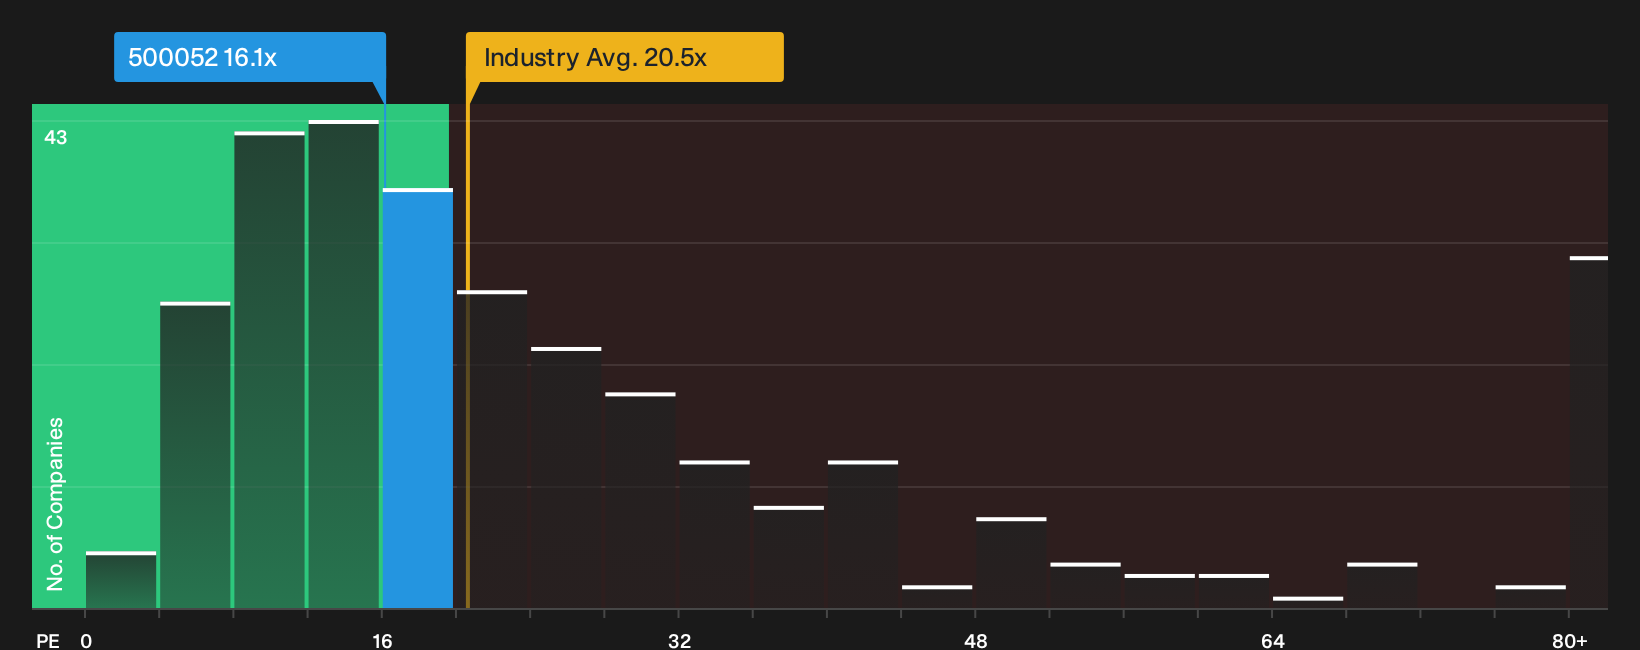
Bhansali Engineering Polymers combines a 3.1% dividend yield with a P/E of 16.1x that sits below the wider Indian market and chemicals sector. Recent quarterly revenue and net income growth plus an affirmed interim payout indicate a dividend closely linked to resin cash flow, depending on how one unseen pressure shapes that income stream.
That hidden pressure point matters for Bhansali Engineering Polymers, and the analysis report for Bhansali Engineering Polymers reveals whether current resin cash flows are masking a very different earnings path ahead.
Gujarat Energy (NSEI:GUJENERGY)
Gujarat Energy runs a large piped natural gas and CNG distribution grid, and that regulated, repeat-use fuel network is what gives its dividend story real weight in this income-focused screen.
"Sustained policy and consumer momentum towards cleaner fuel usage and rapid urban expansion are supporting strong double-digit growth in CNG volumes, with Q1 FY '26 seeing 12% YoY CNG volume increase and the company expecting to outpace even last year's 11% growth due to robust CNG vehicle additions and strategic infrastructure investments; this is likely to drive a multi-year uptick in revenue."
The real hinge for Gujarat Energy’s dividend track record is how one emerging shift in funding and capital intensity ultimately feeds through to free cash.
Gujarat Energy distributes natural gas through its 42,600 km pipeline and 828 CNG outlets, supplying millions of PNG users. It earns most of its ₹273.1b in India revenue from city gas distribution of ₹196.4b and gas trading of ₹194.9b, with a smaller ₹4.8b from power, while the stock is valued at about ₹229.5b.
As that funding shift plays out, read the full narrative for Gujarat Energy for insight into how Gujarat Energy’s gas grid, cash profile and risks could be quietly decoupling from the headline story.

Seeking Alternatives Beyond Dividend Powerhouses
Fresh opportunities move quickly. Some tickers are building breakout momentum while they are still under the radar for now. Before early entry points get caught by the crowd, consider acting before conditions change.
- Target sturdier income ideas by scanning companies in the 159 dividend fortresses while the yields still look compelling and attention has not fully arrived.
- Hunt for resilient balance sheets using the curated list of solid balance sheet and fundamentals (199 results) before these stronger fundamentals attract wider buying interest and shrink the margin of safety.
- Explore potential upside in next-wave materials by reviewing the 36 best rare earth metal stocks before market momentum fully prices in their role in future technologies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com