
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will New CMO Appointment Change Boston Beer’s (SAM) Narrative
- Boston Beer Company appointed Allison Stransky as Chief Marketing Officer in October 2026, tasking her with leading marketing across Samuel Adams, Dogfish Head, Twisted Tea, Sun Cruiser, Truly Hard Seltzer, Angry Orchard, and the wider portfolio.
- Stransky’s background in data-driven consumer work at Samsung and Google gives Boston Beer Company additional firepower to refine digital campaigns and brand positioning across crowded beer and Beyond Beer categories.
- We will now look at how Boston Beer Company's investment narrative could shift as a seasoned, data-led marketer takes over brand leadership.
Scan how Boston Beer Company’s refreshed marketing focus compares with other branded consumer plays by reviewing our hand-picked 16 high quality undiscovered gems that target strong fundamentals and under-the-radar potential.
Boston Beer Company Investment Narrative Recap
To stay invested in Boston Beer Company, you need to be comfortable with a story built around premium alcohol brands, a heavier tilt toward Beyond Beer, and a business that is currently loss making but forecast by analysts to grow earnings quickly. The short term hinge remains whether brands like Twisted Tea, Truly, Sun Cruiser and Samuel Adams can sustain consumer interest in a slower beer category without pushing marketing and promotion costs too far.
The biggest operational risk is still product fatigue and shelf crowding in hard seltzer, RTDs and flavored malt beverages, where failure to keep offerings relevant could pressure both revenue and net margins. Allison Stransky’s arrival as CMO looks important for execution on digital and shopper marketing, but on its own does not alter the fundamental risk that demand for certain categories may soften.
This CMO change ties directly into management’s focus on premium and alternative alcohol segments such as RTD spirits, hard teas, hard seltzers and cider. Boston Beer Company has been leaning into these areas as potential growth drivers while analysts expect revenue to be broadly flat and earnings to recover from current losses, supported by productivity efforts.
Brand health, marketing efficiency and product mix are the real swing factors for that earnings path. Stransky’s experience in data led campaigns and AI driven consumer work at Samsung and Google speaks to the operational push to sharpen targeting, refine messaging around newer products like Sun Cruiser, and try to earn back some margin without overextending on ad spend in a very crowded category set.
What The Analyst Baseline Implies For Boston Beer Company
Boston Beer Company's current analyst storyline assumes revenue stays broadly unchanged over the next few years while profit margins move from a loss making position toward modest profitability. That backdrop keeps most of the weight on what happens to earnings rather than on rapid top line expansion, which is important context as you think about the impact of a new CMO and a heavier focus on Beyond Beer categories.
Analysts in the Simply Wall St report expect earnings to move from a loss of US$70.4 million today to US$107.3 million by 2029. That is a swing of about US$177.7 million, which is a sizeable shift in profitability even if headline sales are described as fairly flat. For you as an investor, the key question is whether stronger margins from efficiency work and a sharper marketing engine can realistically support that kind of earnings turnaround while keeping brand spend at a sustainable level.
The same consensus view points to profit margins rising from 3.7% in the red today to a positive 5.5% in three years. That implies the investment story is less about chasing big new volume pools and more about squeezing better economics out of existing brands and channels. Boston Beer Company is effectively being modeled as a business that can hold its revenue line, then rely on mix, pricing power and cost discipline to rebuild its income statement.
On the revenue side, the analysts referenced in the valuation work up are using a 2029 top line of US$1.9b and earnings of US$107.3 million. Those numbers are being discounted back using a 7.2% to 7.24% rate and paired with a 19.5x P/E on those 2029 earnings. That multiple sits below the cited US beverage industry P/E of 26.1x, which suggests the current consensus is not baking in a premium valuation for Boston Beer Company relative to its wider peer set.
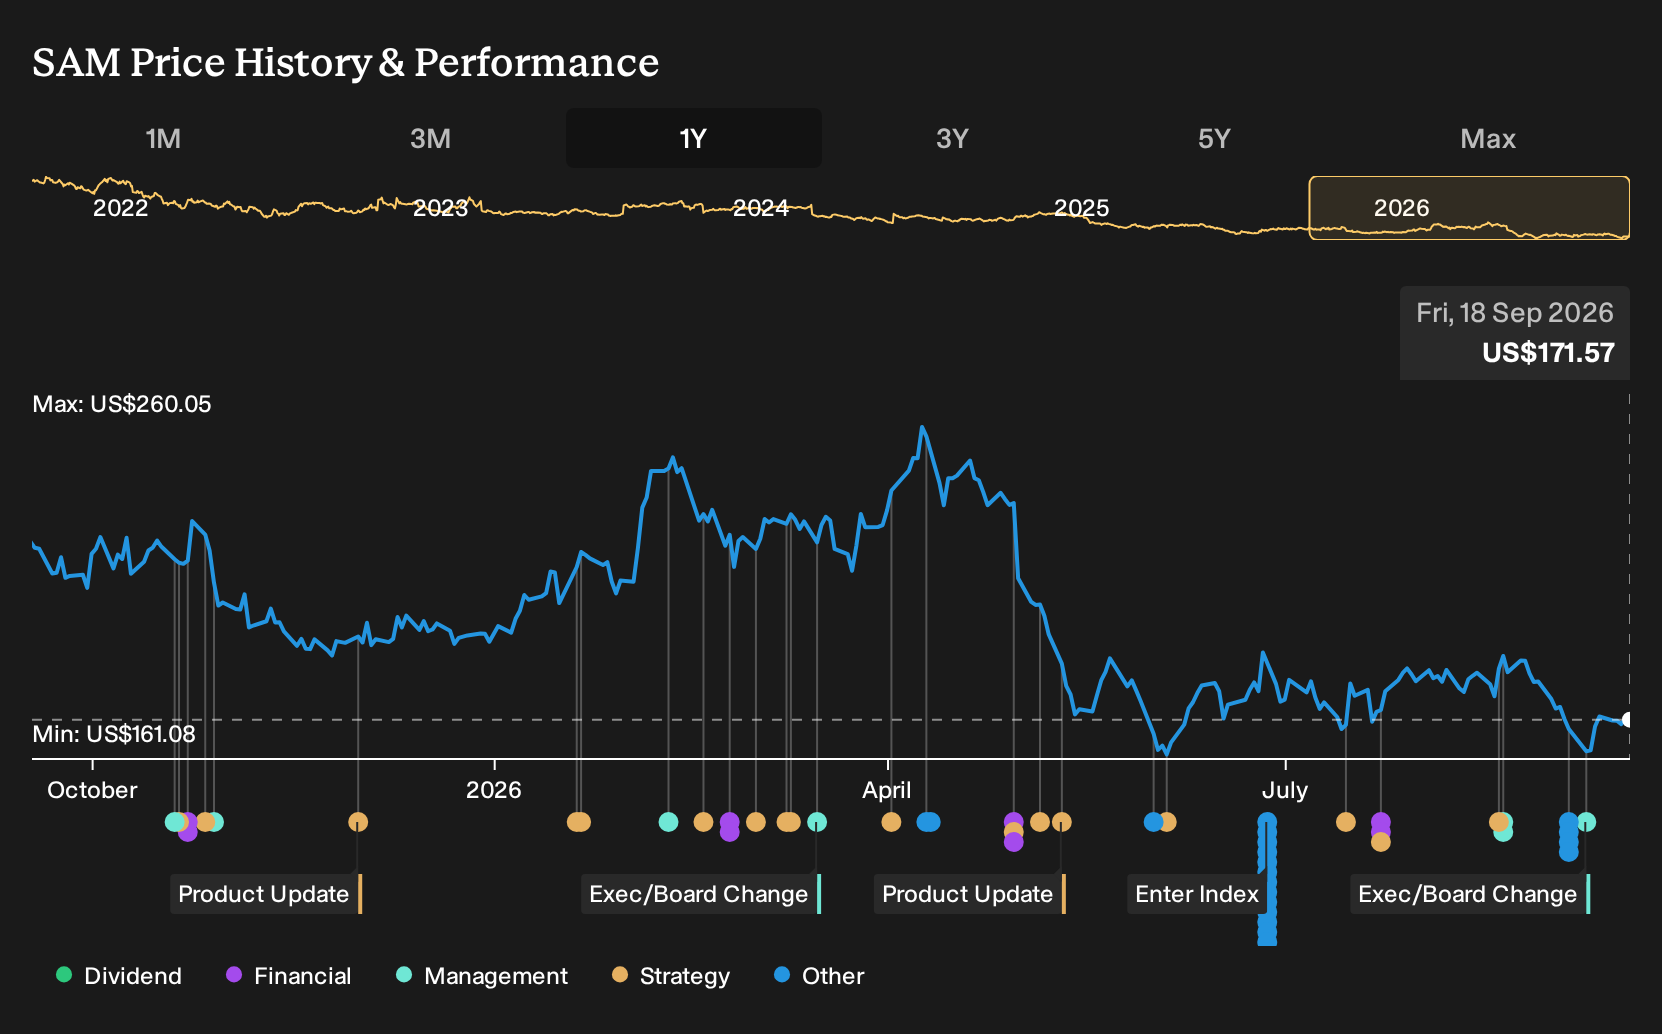
Price targets around this framework cluster at a US$199.85 consensus, with a spread from US$160 on the low end to US$295 at the top. With the shares at US$186.61, that central target sits only 6.6% above the current quote based on the report, which hints that analysts on average see the stock as roughly in line with their assessment of fair value. For you, that tight gap can be a prompt to pressure test your own expectations on Beyond Beer demand, brand strength and margin potential against the assumptions embedded in those numbers.
Boston Beer Company's narrative projects US$1.9b revenue and US$107.3 million earnings by 2029. This reflects analyst expectations of broadly flat yearly revenue and an earnings increase of about US$177.7 million from a current loss of US$70.4 million.
Uncover why Boston Beer Company's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You can read Boston Beer Company very differently. The lowest analysts lean hard into the risk that new marketing firepower cannot offset softer alcohol demand. They were working off flat revenue around US$1.9b and earnings of about US$122.5 million by 2029, and set a US$169 price target before this CMO appointment, so their story could shift from here.
Explore 2 other Boston Beer Company fair value estimates, including one that suggests it could be worth just $199.85.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Boston Beer Company research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Boston Beer Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Beer Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Boston Beer Company?
Once you have a view on Boston Beer Company, it can help to compare that opinion with other businesses that have different risk profiles and balance sheet setups.
- If you want potential upside with tighter risk controls, look at companies screened for 30 resilient stocks with low risk scores that still offer meaningful equity exposure.
- For investors who care most about financial resilience, start with our list of solid balance sheet and fundamentals (23 results) to focus on businesses backed by stronger fundamentals.
- If you are hunting for opportunities that are not widely discussed yet, consider our curated 16 high quality undiscovered gems and see which stocks deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com