
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IES Holdings (IESC) Looks Fully Valued On Mixed Signals Around Its 28.3x P E
IES Holdings (IESC) has drawn fresh attention after its shares last closed at US$322.16, leaving the stock with a year to date total return figure of 58.34%.
Recent trading has been choppy for IES Holdings, with the share price return down 5.94% over the past month and 9.32% over the last quarter, even as the year-to-date share price return sits at 58.34% and the 5-year total shareholder return exceeds 13x. This points to strong longer-term momentum despite a pause in the near-term rally.
Scan how IES Holdings compares with other construction and infrastructure contractors experiencing strong multi-year returns by reviewing the hand picked 39 power grid technology and infrastructure stocks in the same space.
IES Holdings is now trading near US$322 after a steep multi year climb, yet the recent pullback complicates any impulse to rush in. Does the current valuation already bake in that run, or does it still leave room for patience to pay off?
Preferred P/E of 28.3x on IES Holdings: Is it justified?
Valuation on IES Holdings currently leans on a P/E of 28.3x, which sits slightly below both direct peers and the broader US Construction industry, even after the sharp multi year share price climb.
P/E compares the company’s share price to its earnings per share, so it effectively shows how many dollars investors are paying for each dollar of profit. For a contractor that spans communications infrastructure, residential services, commercial projects, and power equipment, this kind of earnings based gauge often matters more than sales based metrics because profitability and capital discipline vary widely across these activities.
IES Holdings shows a combination of fast reported profit expansion and high return on equity, which helps explain why the market is comfortable with a P/E in the high 20s. Earnings are reported to have grown 71.6% over the past year, ahead of the firm’s 5 year average of 46.5% per year, and return on equity is 37.1%, which is described as high relative to a 20% threshold.
Compared to direct peers on P/E, IES Holdings trades below the peer average of 29x and the US Construction industry average of 30.1x. This points to a market price that does not fully mirror its faster historical profit expansion. The estimated fair P/E ratio of 35.4x is also meaningfully higher than the current 28.3x level, which indicates a valuation level the market could move towards if earnings quality and growth assumptions hold up.
Explore the SWS fair ratio for IES Holdings.
Result: Price-to-Earnings of 28.3x (UNDERVALUED).
Still, IES Holdings faces pressure if construction activity cools or if recent revenue and net income growth rates do not support a high 28.3x P/E.
Find out about the key risks to this IES Holdings narrative.
Another View on IES Holdings: Our DCF Model Runs Colder
The P/E story appears supportive for IES Holdings, but the SWS DCF model lands in a different place. On that measure, the stock at $322.16 is trading above an estimated future cash flow value of $265.31, which points to an overvalued outcome instead of a margin of safety.
That gap hints at a practical trade off for you. The market is paying up for earnings strength, while a cash flow lens suggests less cushion if growth, margins, or reinvestment efficiency change from here.
For readers who want to see how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value.
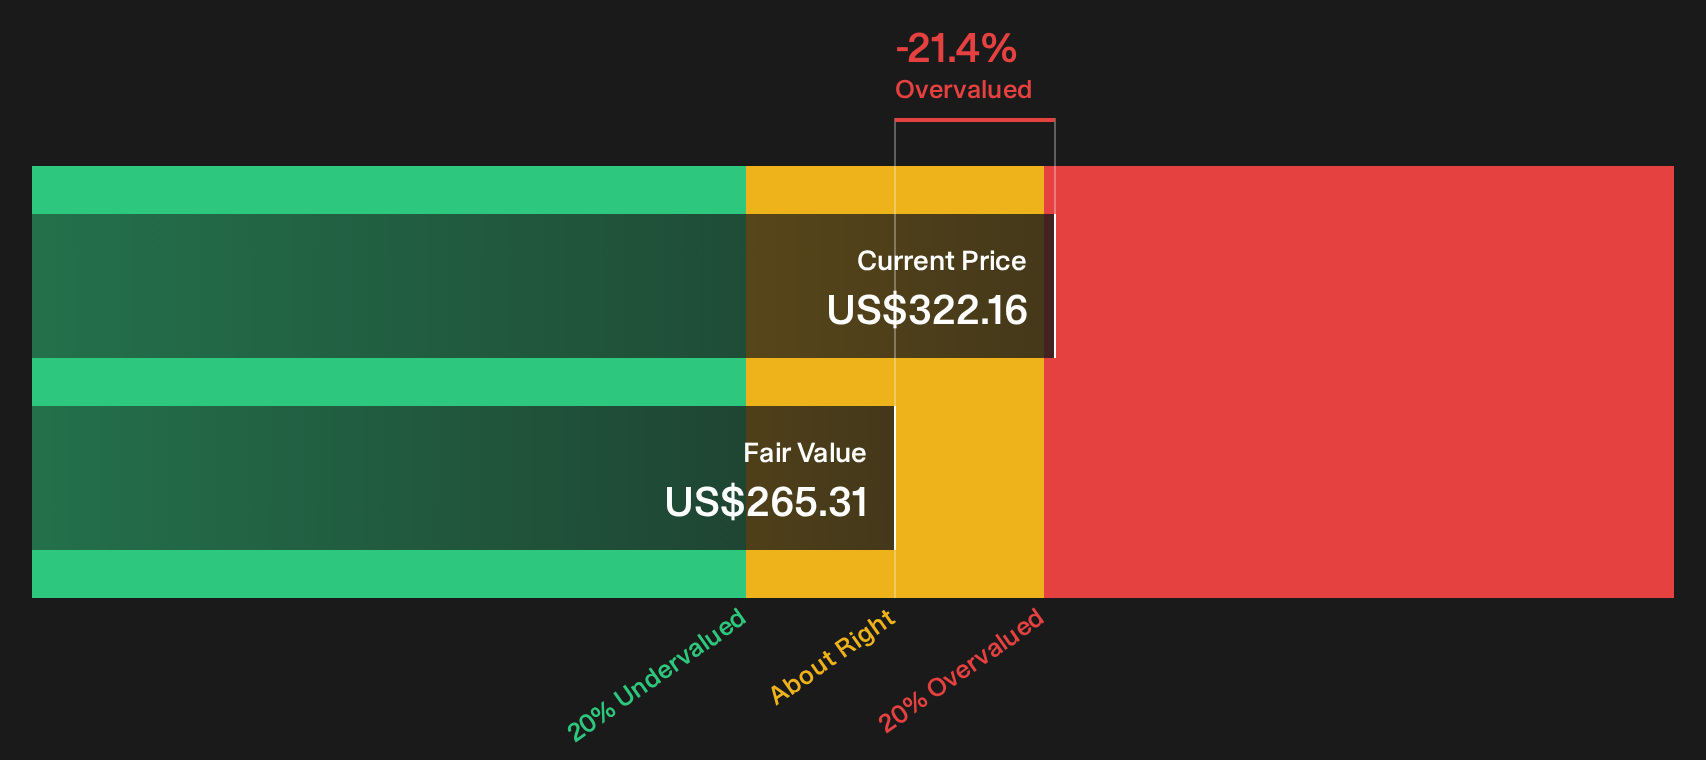
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out IES Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals around IES Holdings point in different directions. This is exactly why it can be useful to move quickly and test the numbers yourself. To see both the potential upsides and the concerns investors are focused on, review the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond IES Holdings?
If IES Holdings has sharpened your focus on quality, do not stop here. Broader opportunities open up once you compare it with other targeted groups of companies.
- Target higher potential upside by scanning a focused group of underpriced quality businesses through the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that feature resilient payouts in the 7 dividend fortresses.
- Dial down risk while staying invested by filtering for robust balance sheets using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com