
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Hyakujushi Bank (TSE:8386) Expensive Following Its Cybersecurity Leadership Shake Up?
Hyakujushi Bank (TSE:8386) has reshaped its leadership after a September 18, 2026 board meeting, creating a Chief Information Security Officer role and assigning Director and Managing Executive Officer Tetsuya Iwase to oversee cybersecurity from October.
Hyakujushi Bank’s leadership reshuffle comes after a strong run in the shares, with a year to date share price return of 86.63% and a very large 5 year total shareholder return of around 9x. Recent 30 and 90 day share price gains suggest momentum is still building as investors reassess growth prospects and cyber risk management.
Scan how Hyakujushi Bank’s cybersecurity-focused shake-up compares with other financial institutions by reviewing hand-picked 21 resilient stocks with low risk scores geared toward resilience and risk control.
Hyakujushi Bank now trades on a very different footing after sharp gains and a visible push on cyber oversight. Are you looking at a sturdier franchise being repriced, or sentiment stretching the valuation?
Preferred P/E of 17.6x for Hyakujushi Bank: Is it justified?
Hyakujushi Bank now carries a P/E of 17.6x against a last close of ¥3,140, which puts the shares on a richer footing than both the Japan banks industry and its closest peers.
The P/E ratio compares the current share price with earnings per share and is a blunt but widely used gauge of how much investors are willing to pay for each unit of profit. For a lender like Hyakujushi Bank, it often reflects how the market weighs recent profit trends and perceived risk in the loan book.
Earnings growth has been strong, with profits up 44.6% over the past year and 13.7% per year over five years, and margins currently at 20.3% compared with 19.2% a year earlier. At the same time, the bank has high quality earnings and an experienced management team, but Return on Equity sits at a relatively low 5.2% and the allowance for bad loans is low at 44%, which can temper how much of a premium some investors are comfortable with.
Compared with the Japan banks industry average P/E of 15.6x and a peer average of 16.5x, Hyakujushi Bank trades at a clear premium. Our DCF work also indicates the ¥3,140 share price is above an estimated future cash flow value of ¥1,698.07. This points to the market paying up relative both to peers and to that SWS DCF model output.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 17.6x (OVERVALUED)
Still, the Hyakujushi Bank story could look different if loan losses rise from today’s low 44% allowance or if return on equity remains near 5.2%.
Find out about the key risks to this Hyakujushi Bank narrative.
Another View on Hyakujushi Bank’s Value
The P/E premium presents Hyakujushi Bank as expensive, yet the SWS DCF model provides a different angle. On that framework, the current ¥3,140 price sits above an estimated future cash flow value of ¥1,698.07, which frames the recent share price move as a richer bet on the story. Does that gap feel like comfort or risk to you?
Look into how the SWS DCF model arrives at its fair value.
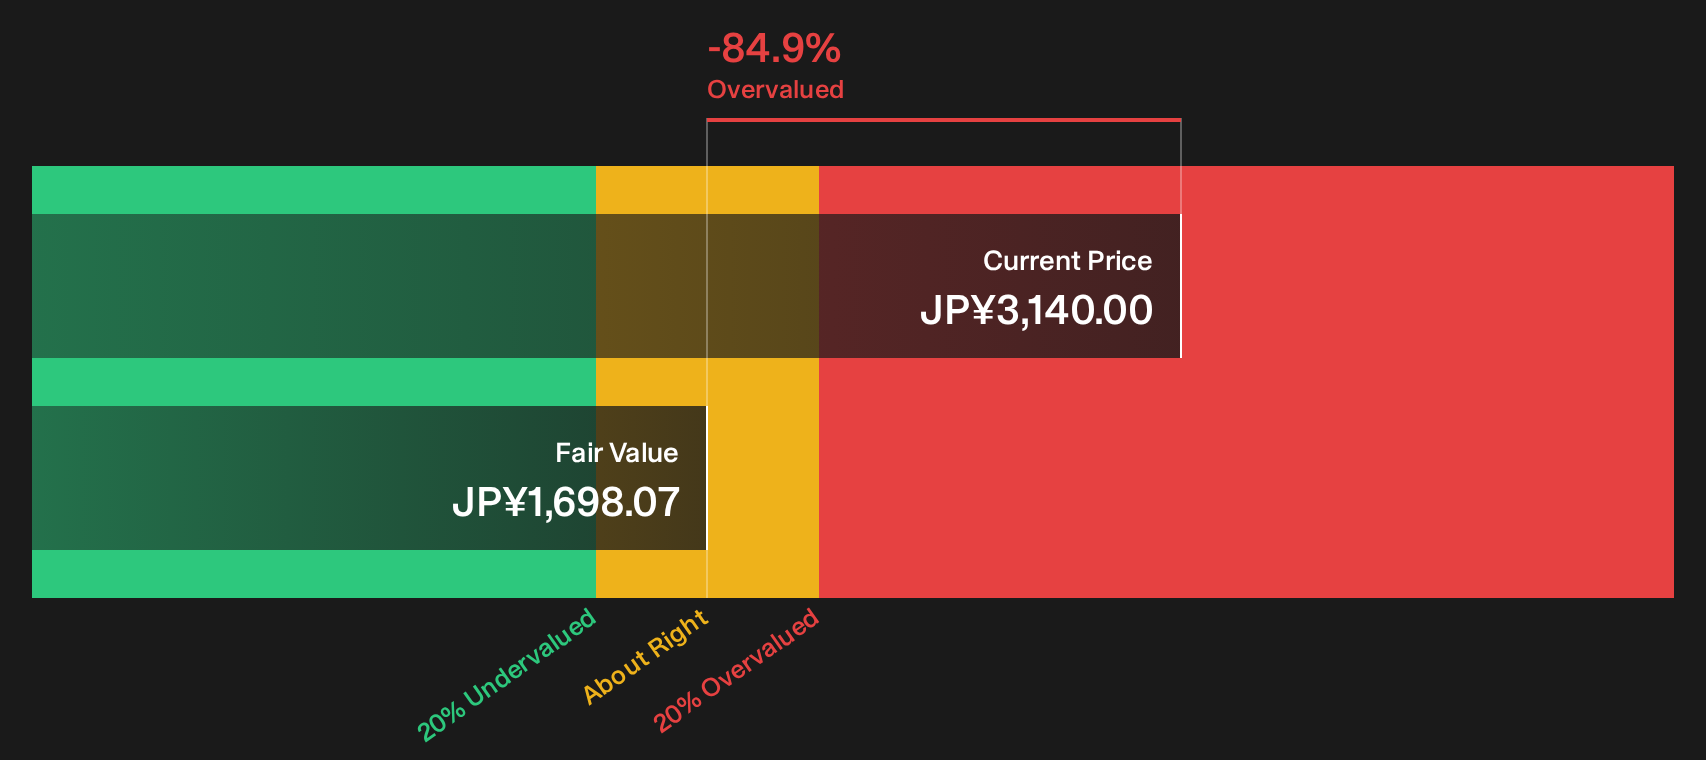
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hyakujushi Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hyakujushi Bank’s valuation and risk profile can feel confusing, so it may help to review the full data yourself and decide where you stand. To weigh both sides of the story in one place, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Hyakujushi Bank?
If Hyakujushi Bank has sharpened your focus on risk, growth and valuation, broaden your watchlist with a few targeted stock ideas before the next move passes you by.
- Target reliable income streams by reviewing 14 dividend fortresses that may appeal if you want yield with a clear, data driven filter.
- Hunt for potential mispricings through the 17 high quality undervalued stocks that highlight companies where fundamentals and current prices appear out of sync.
- Prioritise balance sheet strength using the list of solid balance sheet and fundamentals (21 results) so you are not caught holding fragile businesses when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com