
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did New CEO Appointment Just Shift SEB's (ENXTPA:SK) Investment Narrative?
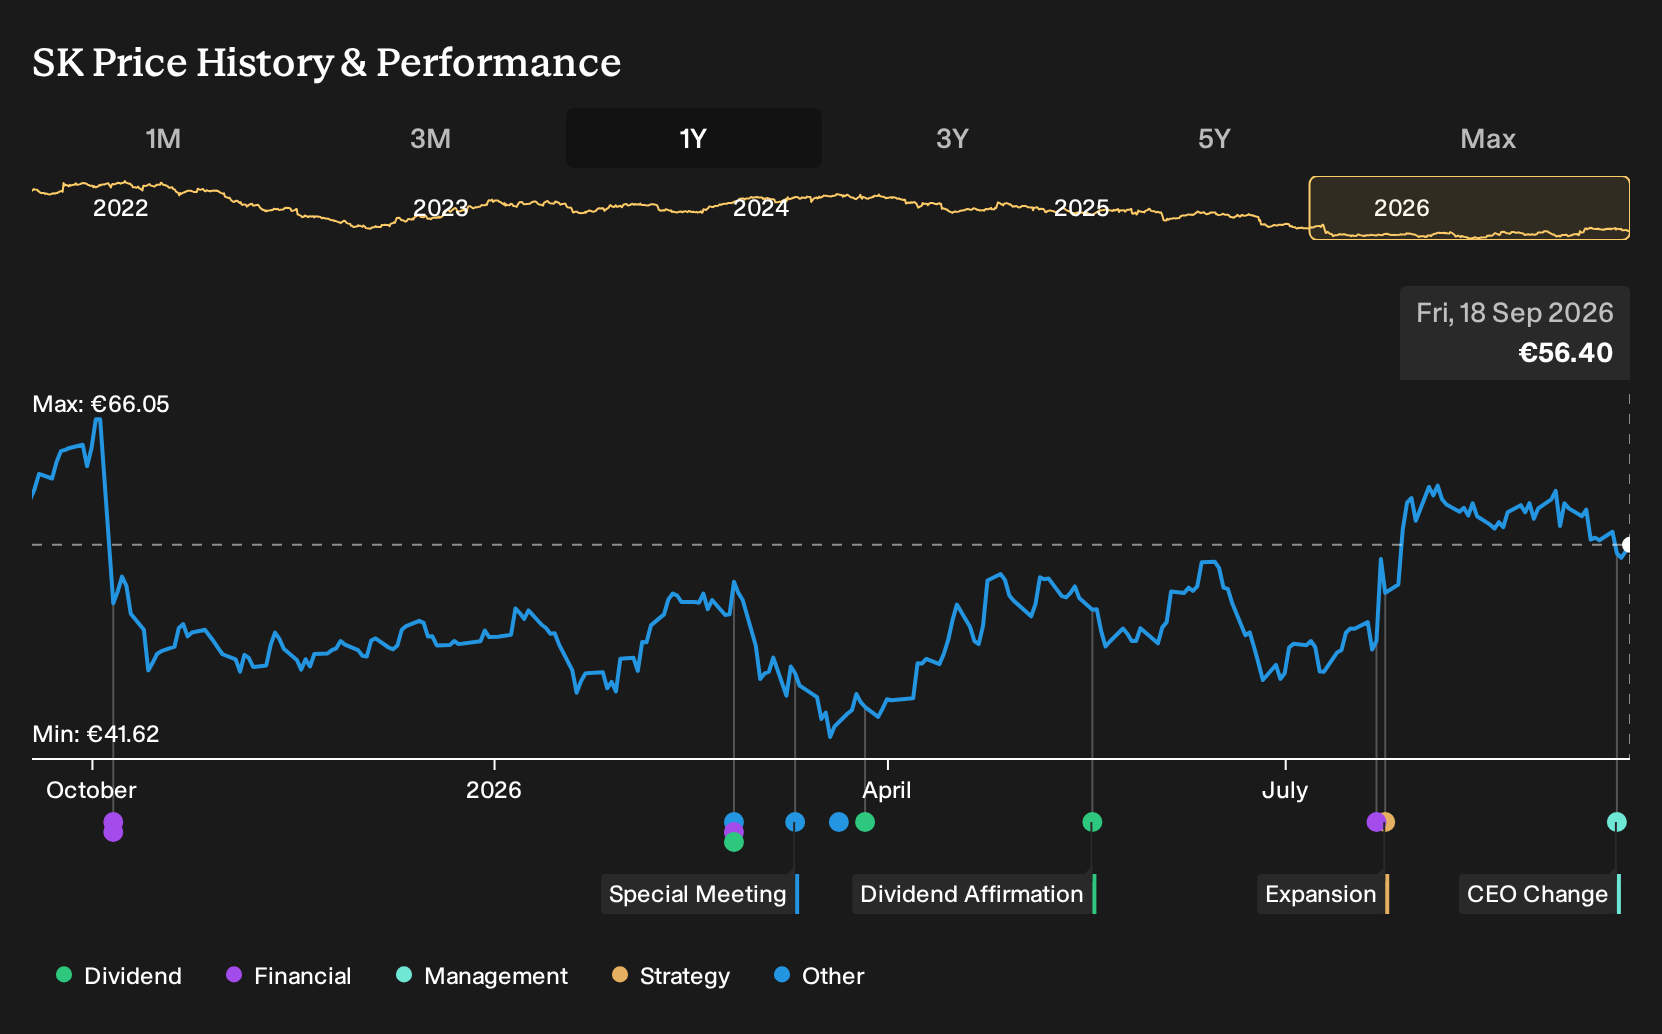
- SEB appointed Loïc Moutault as Chief Executive Officer, effective 1 October 2026, following a unanimous Board decision and the recommendation of the Governance and Remuneration Committee, succeeding outgoing CEO Stanislas de Gramont.
- Moutault brings more than three decades of international leadership from Mars, including roles as Global President of Royal Canin and Mars Petcare, which may influence how SEB tackles global branding, product development, and multicultural team management.
- This appointment could reshape how investors view SEB's leadership, strategy, and execution under Loïc Moutault as the new Chief Executive Officer.
Spot shifts such as the CEO change at SEB early and compare them with other consumer-focused groups using our hand picked screener of 613 high quality undiscovered gems
SEB Investment Narrative Recap
To own SEB, you need to be comfortable with a consumer appliances group that is still working through weak sentiment in Western Europe, softer contributions in parts of EMEA, and tariff uncertainty in North America, while leaning on product launches, Asia exposure and e commerce to do the heavy lifting. The CEO change looks important at a narrative level but does not by itself shift the near term demand picture.
The most immediate swing factor remains how quickly volumes and pricing in key regions translate into cleaner earnings after a period of high inventories and margin pressure. The biggest risk still sits in external shocks like tariffs and currency volatility, which could keep earnings choppy even as SEB adjusts its supply chain and mix.
With no fresh operational announcements tied directly to this leadership change, the most relevant reference point is SEB's existing effort to rebalance its business between Western Europe, China and the broader APAC region. That mix is at the center of both the earnings recovery story and the sensitivity to demand or policy setbacks.
For you as a shareholder, the question is whether Moutault can execute cleanly on product refresh, digital channels and Asia expansion while dealing with high debt, a dividend that is not fully covered and previous one off losses. If execution falters, the risks around tariffs, inventories and working capital become far more visible.
SEB's current analyst story assumes revenue growth of 3.2% a year, taking sales to €9.0b and earnings to €460.7m by 2029, from earnings today of €244.6m. This implies earnings would need to rise by about €216m over that period.
Uncover why SEB's fair value indicates a 30% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on SEB focuses on Professional Coffee risk. The most bearish analysts worry that fixed costs there could cap any earnings recovery, even though they were still penciling in €9.2b of revenue and €509.9m of earnings by 2029 before this CEO news. Those expectations show how sharply opinions can differ. It may be useful to explore a few scenarios for yourself.
Explore 2 other SEB fair value estimates, including one that suggests it could be worth just €73.45!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SEB research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SEB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SEB's overall financial health at a glance.
Looking for more SEB-like investment ideas?
Once you have a view on SEB, it can help to line it up against other listed businesses that share similar qualities or offer very different risk and return profiles.
- If you want to focus on value with quality fundamentals, start with a curated set of 183 high quality undervalued stocks that combine stronger finances with more modest pricing.
- For investors who put capital preservation first, narrow your universe to companies in our 227 resilient stocks with low risk scores and see which businesses line up with your tolerance for volatility.
- If balance sheet strength is your priority, filter for companies on the list of solid balance sheet and fundamentals (199 results) and compare their financial resilience with what you see at SEB.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com