
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SK Hynix (NasdaqGS:SKHY) Gains High NA EUV Attention While Fair Value Stays In Focus
SK hynix (SKHY) moved into focus after ASML highlighted the chipmaker as a key partner for its next generation High NA EUV tools, which are aimed at larger data center processors.
The recent ASML collaboration headlines arrive on top of strong momentum in SK hynix, with the stock posting a 1-day share price return of 2.46%, a 7-day return of 6.76% and a 30-day share price return of 14.74%. The year-to-date share price return of 11.60% signals building interest rather than fading enthusiasm.
Capitalize on the High NA EUV momentum around SK hynix by scanning a hand picked set of AI infrastructure plays through the 88 AI infrastructure stocks.SK hynix now trades at a steep gap to analyst targets and estimated fair value, even after this sharp AI driven run. Is that discount compensation for real risk, or is it an overdone safety margin?
Price-to-Earnings of 8.4x: Is it justified?
On simple earnings terms, SK hynix looks inexpensive. The stock closed at $187.50 while trading on a P/E of 8.4x, against both peer and wider semiconductor averages that are many times higher. This points to a wide valuation gap rather than a marginal discount.
The P/E ratio compares what investors pay today for each dollar of current earnings. For a memory and storage heavyweight like SK hynix, that yardstick is closely watched because earnings can swing sharply through each semiconductor cycle and investors often pay up for businesses where profit growth is expected to hold up.
Here, the combination of a low multiple and very strong fundamentals is striking. Earnings are forecast to grow 26.9% per year, revenue is expected to expand 33.9% annually, recent profit growth has been very large compared with the past five years, and Return on Equity sits at 61.7%, which is described as outstanding. That mix suggests the current P/E embeds a heavy safety buffer rather than aggressive optimism.
The comparison with peers is even more stark. SK hynix trades on 8.4x earnings compared with a 59.1x peer average and a 47x broader US Semiconductor industry average. That is not a small gap; it is a multi turn difference that implies the market is pricing SK hynix far more conservatively than many other chipmakers despite its high forecast growth and very high forecast Return on Equity.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 8.4x (UNDERVALUED)
Still, the SK hynix story can change quickly if High NA EUV adoption disappoints or if memory pricing weakens and compresses those currently strong earnings metrics.
Find out about the key risks to this SK hynix narrative.
Another View: SK hynix Through The SWS DCF Lens
The earlier P/E discussion presents SK hynix as inexpensive on current earnings. A different tool points in the same direction. Our DCF model values the shares at $529.69, while the stock last traded at $187.50. That gap indicates a wide implied discount and raises a simple question for investors: What assumptions need to change for that valuation spread to narrow?
Look into how the SWS DCF model arrives at its fair value.
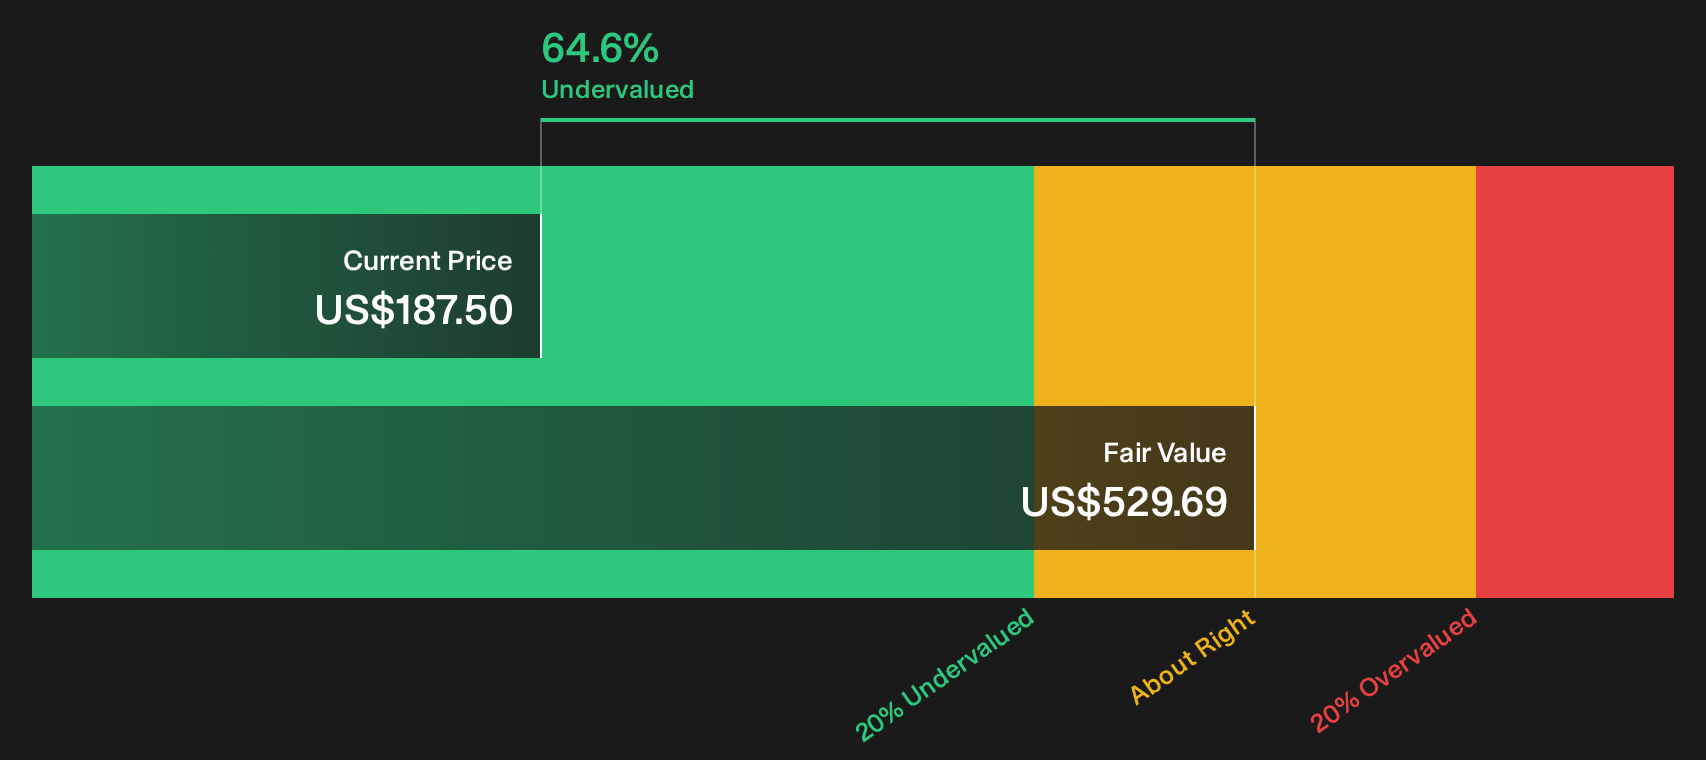
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SK hynix for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With SK hynix presenting both concerns and clear positives, the key question is how you personally weigh that mix of risk and reward. Act while the numbers and narrative are fresh in your mind and use the 3 key rewards and 2 important warning signs
Looking for more SK hynix style investment ideas?
If you want to keep building on the SK hynix groundwork, broaden your watchlist with a few focused stock ideas that match your preferred risk and return profile.
- Target value opportunities by scanning a curated 35 high quality undervalued stocks that balance quality fundamentals with attractive pricing.
- Prioritize resilience by reviewing a 30 resilient stocks with low risk scores that score well on financial strength and business stability.
- Hunt for future standouts by checking a 16 high quality undiscovered gems that combine solid metrics with limited current attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com