
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CSPC Pharmaceutical Group (SEHK:1093) Expands Its Pipeline, Is The Stock Still Undervalued?
CSPC Pharmaceutical Group (SEHK:1093) has been busy. A fresh Phase II trial in type 2 diabetes, new NMPA designations in oncology and multiple trial approvals across neurology and ophthalmology are drawing fresh attention to the shares.
The recent cluster of diabetes, oncology, neurology and ophthalmology updates appears to have coincided with a sharp pickup in interest. CSPC Pharmaceutical Group’s 1-day share price return of 7.56% at HK$9.605 capped a 90-day share price return of 40.42%, while the 3-year total shareholder return of 85.46% points to much stronger gains over a longer holding period than over the past year.
Scan CSPC Pharmaceutical Group’s recent momentum against a curated set of peers with strong pipelines and balance sheets using the 613 high quality undiscovered gems.
Bulls point to CSPC Pharmaceutical Group’s crowded pipeline and a recent 40% 90-day share price jump. Bears focus on softer net income growth and execution risk. Which side do the current valuation numbers appear to favor next?
Price-to-Earnings of 12.6x: Is it justified?
CSPC Pharmaceutical Group trades on a P/E of 12.6x, which corresponds to a share price of HK$9.605 that screens as inexpensive relative to both peers and internal fair value estimates.
The P/E ratio compares the current share price with earnings per share, so it effectively indicates how much investors are paying for each unit of profit. For a pharmaceuticals group like CSPC Pharmaceutical Group, this matters because profit quality, pipeline risk and earnings stability can all influence how much of a premium or discount the market assigns.
On this measure, the stock is described as good value compared to a peer average P/E of 21.5x, as well as the Hong Kong pharmaceuticals industry at 14.1x. The estimated fair P/E of 16.6x is materially higher than the current 12.6x, which suggests the multiple may move closer to that level if the market eventually prices CSPC Pharmaceutical Group’s earnings in line with this fair ratio.
Explore the SWS fair ratio for CSPC Pharmaceutical Group.
Result: Price-to-Earnings of 12.6x (UNDERVALUED)
Still, softer annual net income growth and the risk that CSPC Pharmaceutical Group’s crowded pipeline fails to translate into stronger earnings could challenge the current valuation story.
Find out about the key risks to this CSPC Pharmaceutical Group narrative.
Another View on CSPC Pharmaceutical Group’s Value
The P/E points one way, yet the SWS DCF model points even further. On that approach, CSPC Pharmaceutical Group’s estimated future cash flow value sits at HK$14.14 per share versus the current HK$9.61. That implies the stock trades at a steep discount. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
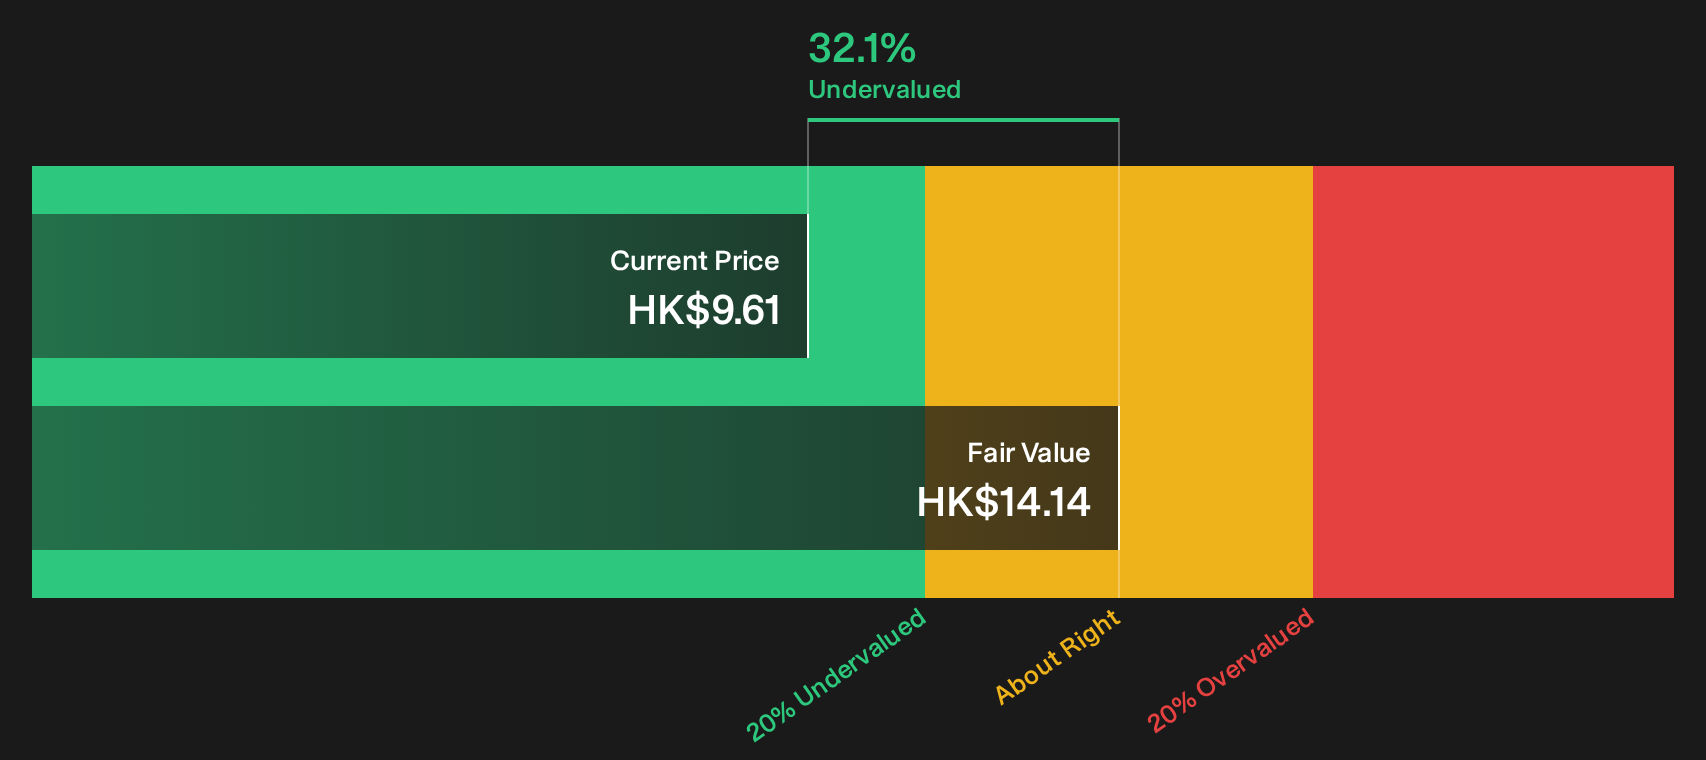
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CSPC Pharmaceutical Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on CSPC Pharmaceutical Group feel messy, that is exactly why the data matters. Act while the information is fresh and weigh both sides by checking the 3 key rewards and 2 important warning signs.
Looking for more CSPC Pharmaceutical Group style ideas?
If CSPC Pharmaceutical Group has your attention, do not stop here. Broaden your watchlist with fresh ideas the market might be overlooking right now.
- Target potential upside by focusing on quality companies trading below estimated value using the 183 high quality undervalued stocks.
- Strengthen your search for stability by filtering for businesses with healthier finances through the list of solid balance sheet and fundamentals (199 results).
- Hunt for lesser known opportunities that still show strong fundamentals with the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com