
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tokyo Ohka Kogyo (TSE:4186) Backs NLM Photonics, Is It Still Below Fair Value?
Tokyo Ohka Kogyo (TSE:4186) is back in focus after fresh debate around its rich P/E ratio, with attention shifting to its backing of NLM Photonics and discounted cash flow estimates that imply undervaluation.
The current ¥8,073 share price comes after a sharp pullback, with the 30 day share price return down 7.16% and the 90 day share price return down 29.28%. Tokyo Ohka Kogyo still shows a 34.44% year to date share price gain and a 67.32% total shareholder return over one year, indicating longer term momentum and recent profit taking as investors reassess the rich P/E debate and the implications of its NLM Photonics backing.
Compare Tokyo Ohka Kogyo's valuation story with a curated group of higher conviction opportunities using the 17 high quality undervalued stocks that share strong fundamentals and potential mispricing.
After a powerful multi year run and a sharp recent pullback, Tokyo Ohka Kogyo now sits at a point where investors have to ask if most of the upside is already in the rear view mirror or if the DCF gap suggests more ahead.
Preferred P/E of 24.1x: Is it justified?
On simple multiples, Tokyo Ohka Kogyo screens as expensive, with a P/E of 24.1x at a last close of ¥8,073, especially when you line that up against both its own fair P/E estimate and the wider Chemicals peer group.
The P/E ratio compares the current share price to earnings per share and gives a quick sense of how much investors are willing to pay for each unit of profit. For a speciality materials producer that leans heavily on semiconductor related demand, this matters because much of the current value hinges on confidence in future earnings rather than the latest reported year alone.
Tokyo Ohka Kogyo is flagged as expensive versus the estimated fair P/E of 20.1x. This suggests the market is attaching a richer earnings multiple than the SWS fair ratio suggests could be justified over time. It is also trading above both the peer average multiple of 18.7x and the broader JP Chemicals industry on 12.9x. This represents a steep premium that reflects strong historic profit growth and margins, yet also sets a high expectations bar that future results must meet.
Explore the SWS fair ratio for Tokyo Ohka Kogyo.Result: Price-to-Earnings of 24.1x (OVERVALUED).
Still, the rich P/E argument can quickly unravel if semiconductor related demand softens, or if Tokyo Ohka Kogyo stumbles on executing its growth projects.
Find out about the key risks to this Tokyo Ohka Kogyo narrative.
Another view on Tokyo Ohka Kogyo’s value
The P/E looks expensive for Tokyo Ohka Kogyo at 24.1x, yet the SWS DCF model points the other way. On that cash flow lens, the estimated value sits at ¥15,830.17 per share, which puts the current ¥8,073 price at a 49% discount and frames the recent pullback in a very different light.
For readers who want to see how this cash flow based view is built line by line, Look into how the SWS DCF model arrives at its fair value.
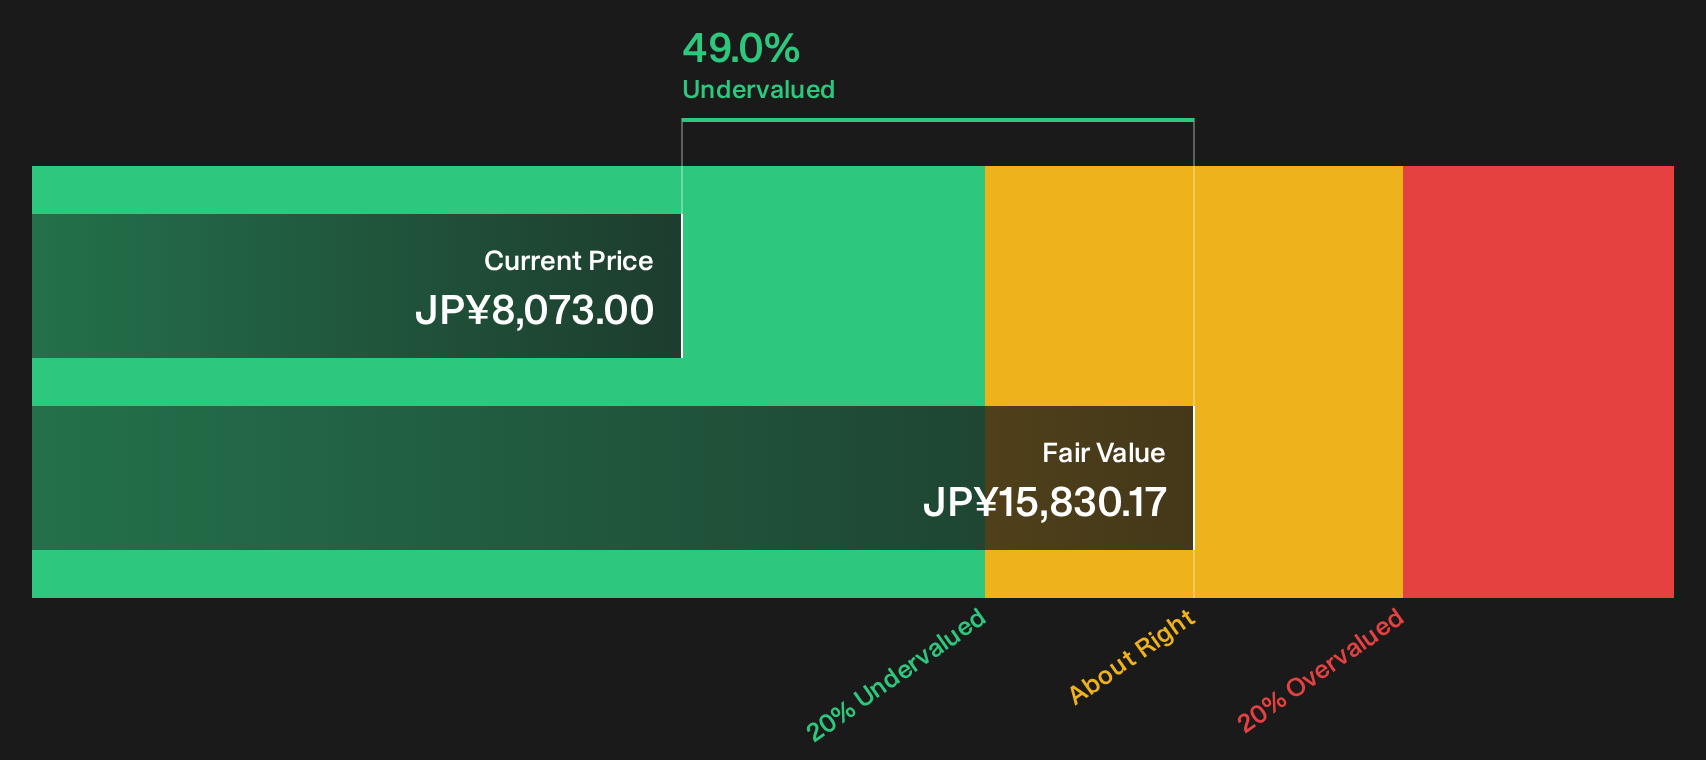
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Ohka Kogyo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Tokyo Ohka Kogyo’s valuation, risks and rewards can feel messy, so review the data quickly and decide where you land. To see both sides in one place, consider the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tokyo Ohka Kogyo?
Do not stop with Tokyo Ohka Kogyo. Use the screener to quickly surface other opportunities that match your style before the next market move passes you by.
- Target potential mispriced quality by running a focused search through the 17 high quality undervalued stocks and see which businesses currently trade below their estimated worth.
- Strengthen your income stream by scanning the 14 dividend fortresses to spot companies with higher yields that still clear key financial health checks.
- Reduce portfolio stress by filtering for sturdier balance sheets using the list of solid balance sheet and fundamentals (21 results) and highlight businesses built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com