
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Synaptics (SYNA) Could Be 29% Undervalued After Nvidia Isaac Sim Integration
Synaptics (SYNA) has integrated its tactile sensing CTS module, powered by the SN6012T controller, into the NVIDIA Isaac Sim framework, connecting its touch hardware to simulated robotic hands and broader Physical AI testing.
Recent trading paints a mixed picture for Synaptics. The share price is up 22.93% year to date and the 1-year total shareholder return is 27.51%. However, the 90-day share price return has declined 30.73%, signalling that positive longer term momentum has faded in the short run as investors reassess both growth potential and risk around new Physical AI initiatives like the Isaac Sim integration.
Scan beyond Synaptics and discover other AI infrastructure plays that are already on the move with our curated 88 AI infrastructure stocks
After a sharp reset from the recent peak, Synaptics now splits opinion. Has the pullback cleared enough froth for more upside, or has most of the easy move already played out before the valuation case even starts?
Most Popular Narrative: 29% Undervalued
On the most followed valuation narrative, Synaptics screens as undervalued, since the fair value estimate of $130.33 sits above the last close of $93.11 while analysts still debate how much of the Physical AI and IoT story is already in the price.
The launch and initial customer traction of native Edge AI processors (Astra family, featuring Google Research collaboration and neural transformer support) targets the growing shift toward on-device processing for AI workloads. This potentially positions Synaptics as a key supplier for next-gen IoT applications and may support both revenue growth and product differentiation. The company's strategy to bundle highly integrated solutions combining wireless connectivity, low-power mixed-signal processing, and embedded AI/software content is intended to increase silicon content per device and capture more revenue per customer design win.
See why 12 investors see Synaptics as 29% undervalued.
Result: Fair Value of $130.33 (UNDERVALUED)
Still, the Synaptics story can break if execution on Core IoT scaling falters or if any misstep around the all stock On Semi deal undermines the bullish edge AI thesis.
Find out about the key risks to this Synaptics narrative.
Another View: Synaptics Through A Cash Flow Lens
The first narrative leans on analyst targets that suggest Synaptics is undervalued. A different tool, the SWS DCF model, paints a cooler picture. On that framework, Synaptics at $93.11 trades above an estimated future cash flow value of $79.60, which screens as overvalued. Which story do you trust more when real cash has to show up?
Look into how the SWS DCF model arrives at its fair value.
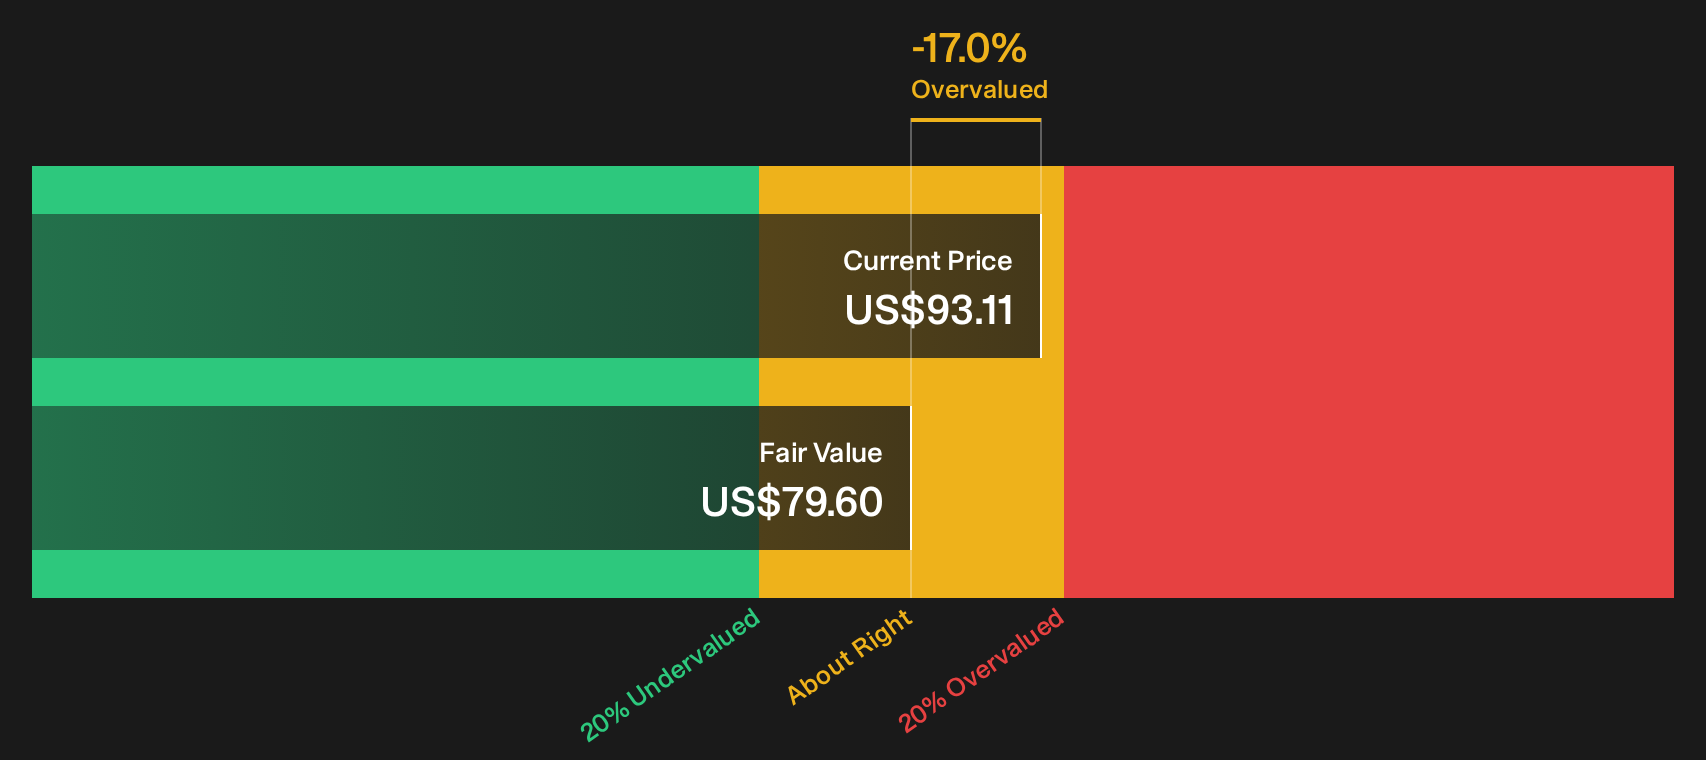
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Synaptics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about what Synaptics really offers after all this Physical AI talk and valuation debate? Act quickly, test the data yourself, and weigh both sides by reviewing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Synaptics?
If Synaptics has sharpened your focus on what you own, use that momentum and line up a few fresh candidates before the next move catches you off guard.
- Target value first and hunt for quality businesses trading below their implied worth with the 35 high quality undervalued stocks.
- Protect your downside and concentrate on resilient companies with stronger financial footing using the 30 resilient stocks with low risk scores.
- Get ahead of the crowd and scan for underfollowed opportunities with solid fundamentals through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com