
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Growth Stocks For September 2026
Rising UK interest rates and calls to expand the national wealth fund are pushing more attention onto homegrown growth champions. Capital is lining up for projects that can support jobs and future tax revenue, which puts financially sound high growth British companies in the spotlight. This article highlights three stocks from our healthy growth screener that analysts currently expect to deliver strong earnings growth over the next few years.
The three examples below are only a starter set from this theme, with the full screen surfacing 29 more healthy high growth candidates that analysts view as having similarly compelling earnings stories. To see the complete group, head straight into the Healthy high growth potential screener to identify, filter and analyze the ideas that best match your own conviction level.
Anglo Asian Mining (AIM:AAZ)
Anglo Asian Mining is a Baku based producer of gold, copper and silver in Azerbaijan, with performance tied directly to output from its Gedabek and Tovuz mines. The miner generated about $123 million from mining operations and has a market value of roughly £422 million.
The company trades on a rich 32x P/E and has a debt heavy balance sheet, so a lot rests on how one financial pressure point evolves.
If you want to see how that pressure point could play out, start with the DCF valuation analysis for Anglo Asian Mining to see what the market might be pricing in.
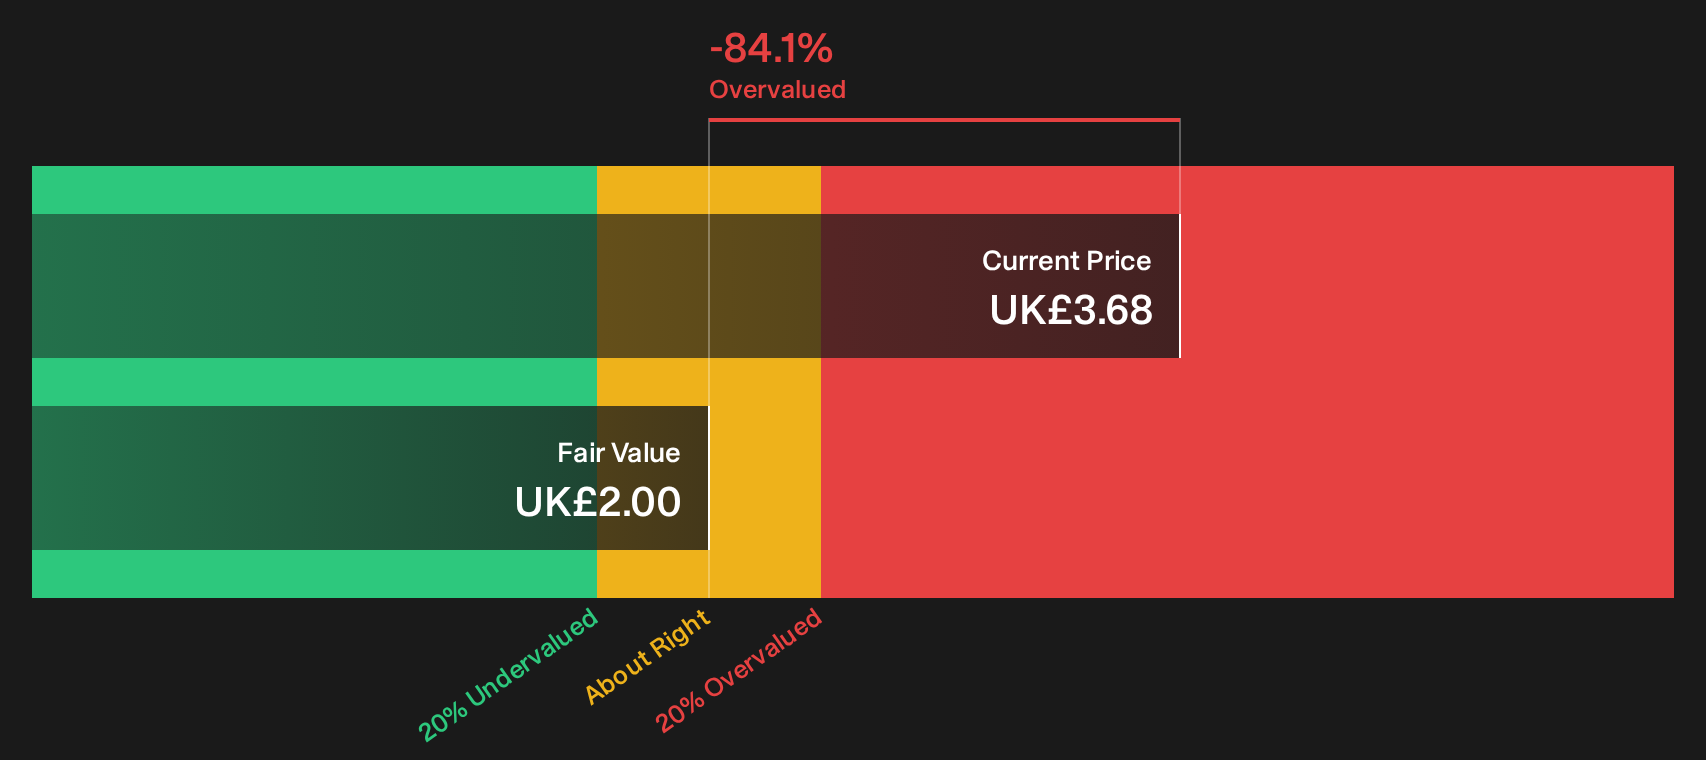
Metals Exploration (AIM:MTL)
Metals Exploration focuses on identifying, acquiring and developing gold and other precious metal projects. Growth expectations are tied closely to its 100% owned Runruno gold project in the Philippines. The business generated about $208 million from precious metals and has a market value of roughly £513 million.
Metals Exploration links cleanly to the Healthy high growth potential theme, with analysts in the provided information expecting earnings to rise about 86.73% per year over the next 3 years on top of 19.6% annual growth over the past 5 years. That trajectory depends heavily on what happens if one project level assumption stops cooperating.
If that project assumption cracks, the analysis report for Metals Exploration shows how Metals Exploration’s growth story could either stall or reaccelerate quickly.

Ceres Power Holdings (LSE:CWR)
Ceres Power Holdings develops solid oxide fuel cell and electrolysis technology that supports the Healthy high growth potential theme through commercial SOFC and SOEC platforms. The group earns contract and licensing income primarily from Asia at about £28 million, with smaller contributions from Europe and North America, and has a market value near £877 million.
Ceres Power Holdings gives this screener something different, with SOFC and SOEC technology that can be licensed into multiple clean energy and power markets rather than built only on its own balance sheet.
"Ceres Power's unique solid oxide technology and licensing business model provide cross-border opportunities, enabling the company to tap into global markets despite trade wars and localized production. The expected commencement of product production by Ceres Power’s partners, such as Doosan’s factory in South Korea, represents a significant step toward generating royalties, which are forecasted to become a substantial part of the company’s revenue stream."
What happens if one key assumption about how quickly those partners ramp output and translate it into cash flow shifts even slightly?
Small changes to that ramp can have an outsized effect on Ceres Power Holdings, so read the full narrative for Ceres Power Holdings to see how both risks and upside could accelerate.

Seeking Alternatives Before The Crowd
Fresh opportunities are flying under the radar for now, and the best entry points often drop away fast. Scan these curated idea lists before momentum breaks and get in early.
- Target resilient cash generators that can shoulder volatility by scanning a curated list of solid balance sheet and fundamentals (11 results) while it still flies under most investors' radar.
- Track the potential of expanding electrification and infrastructure demand by following curated 17 top copper producer stocks before broad market interest catches up.
- Review hand picked 96 robotics and automation stocks while these automation driven opportunities remain under followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com