
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Stocks That Might Be Undervalued By As Much As 46.2%
In the last week, the United States market has remained flat, yet it has experienced a 12% increase over the past year with earnings forecasted to grow by 17% annually. In such an environment, identifying undervalued stocks can be crucial for investors seeking opportunities that may offer potential value relative to their current price.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valley National Bancorp (VLY) | $13.59 | $27.10 | 49.8% |
| UiPath (PATH) | $13.39 | $25.15 | 46.8% |
| Pegasystems (PEGA) | $35.05 | $69.25 | 49.4% |
| Futu Holdings (FUTU) | $112.01 | $209.63 | 46.6% |
| Civista Bancshares (CIVB) | $27.29 | $53.11 | 48.6% |
| Chagee Holdings (CHA) | $12.02 | $22.61 | 46.8% |
| Capital Bancorp (CBNK) | $35.87 | $66.89 | 46.4% |
| Best Buy (BBY) | $92.85 | $185.63 | 50% |
| Autodesk (ADSK) | $216.95 | $414.02 | 47.6% |
| Addus HomeCare (ADUS) | $117.07 | $226.18 | 48.2% |
Let's dive into some prime choices out of the screener.
Amazon.com (AMZN)
Overview: Amazon.com, Inc. operates in the retail sale of consumer products, advertising, and subscription services through both online and physical stores globally, with a market capitalization of approximately $2.74 trillion.
Operations: The company's revenue segments include North America with $453.67 billion, International with $173.61 billion, and Amazon Web Services (AWS) contributing $148.40 billion.
Estimated Discount To Fair Value: 41.5%
Amazon's stock is currently trading at US$253.71, which is 41.5% below its estimated future cash flow value of US$433.85, suggesting it may be undervalued based on cash flows. Recent developments include the launch of an FAO Schwarz storefront on Amazon.com, expanding its retail offerings and potentially boosting revenue streams. However, despite strong past earnings growth, future earnings are forecasted to grow slower than the market average at 6.2% annually.
- Our earnings growth report unveils the potential for significant increases in Amazon.com's future results.
- Click here and access our complete balance sheet health report to understand the dynamics of Amazon.com.

Warrior Met Coal (HCC)
Overview: Warrior Met Coal, Inc. produces and exports non-thermal steelmaking coal for metal manufacturers in Europe, South America, and Asia with a market cap of $4.64 billion.
Operations: The company's revenue primarily comes from its mining segment, which generated $1.65 billion.
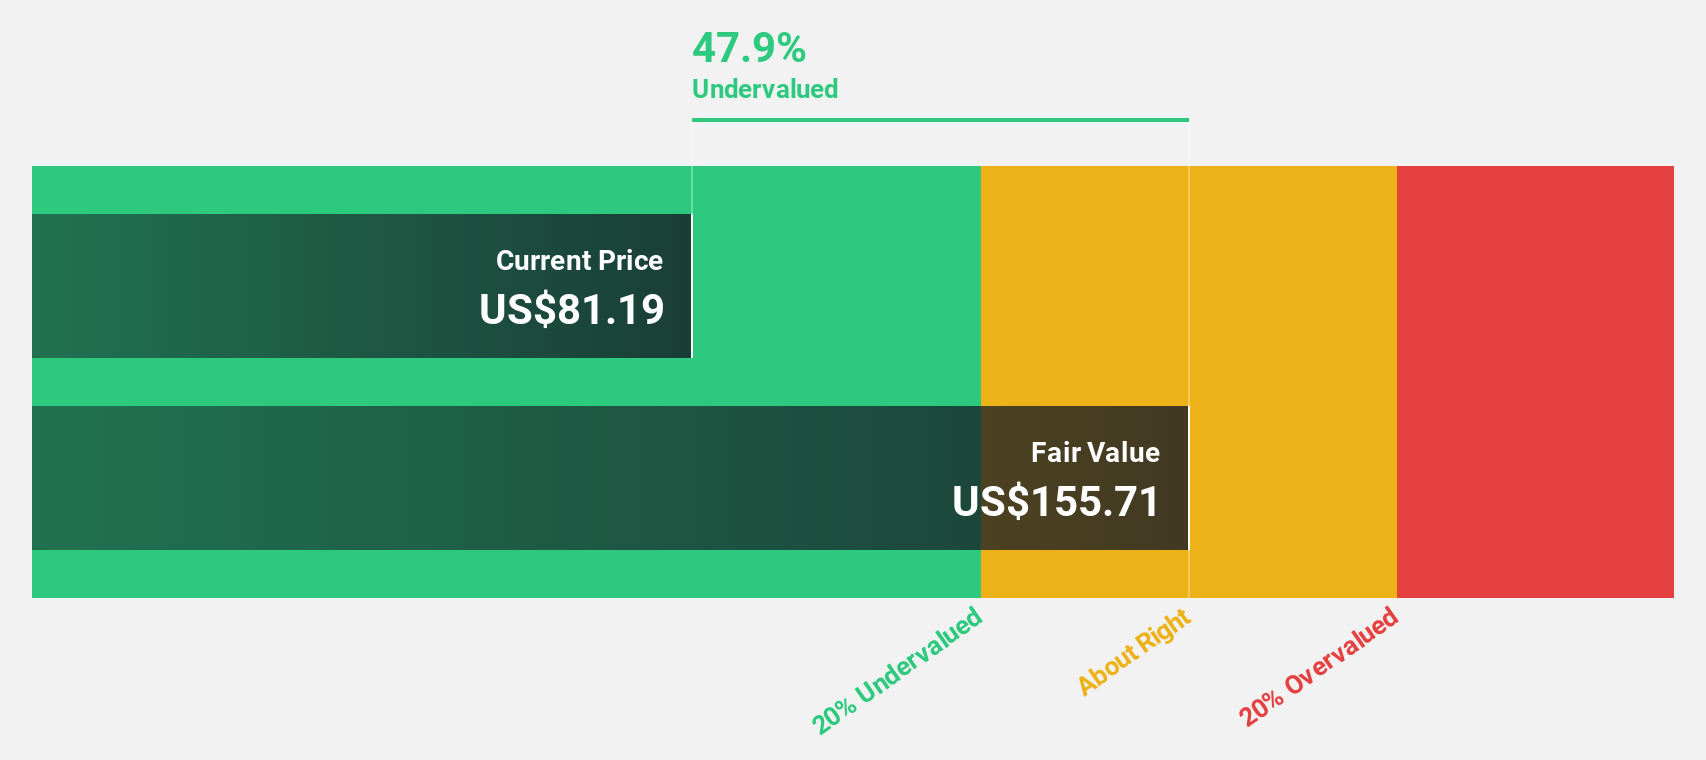
Estimated Discount To Fair Value: 46.2%
Warrior Met Coal is trading at US$87.93, significantly below its estimated future cash flow value of US$163.38, highlighting potential undervaluation based on cash flows. Recent earnings reports show robust growth with revenue reaching US$509.69 million in Q2 2026 compared to US$297.52 million a year ago and net income rising to US$87.43 million from US$5.61 million previously, despite insider selling and slower forecasted revenue growth than the market average.
- According our earnings growth report, there's an indication that Warrior Met Coal might be ready to expand.
- Get an in-depth perspective on Warrior Met Coal's balance sheet by reading our health report here.
PJT Partners (PJT)
Overview: PJT Partners Inc. is an investment bank offering strategic advisory, shareholder advisory, capital markets advisory, and restructuring services to a global clientele including corporations and governments, with a market cap of $6.20 billion.
Operations: The company's revenue is primarily derived from its advisory services, totaling $1.89 billion.
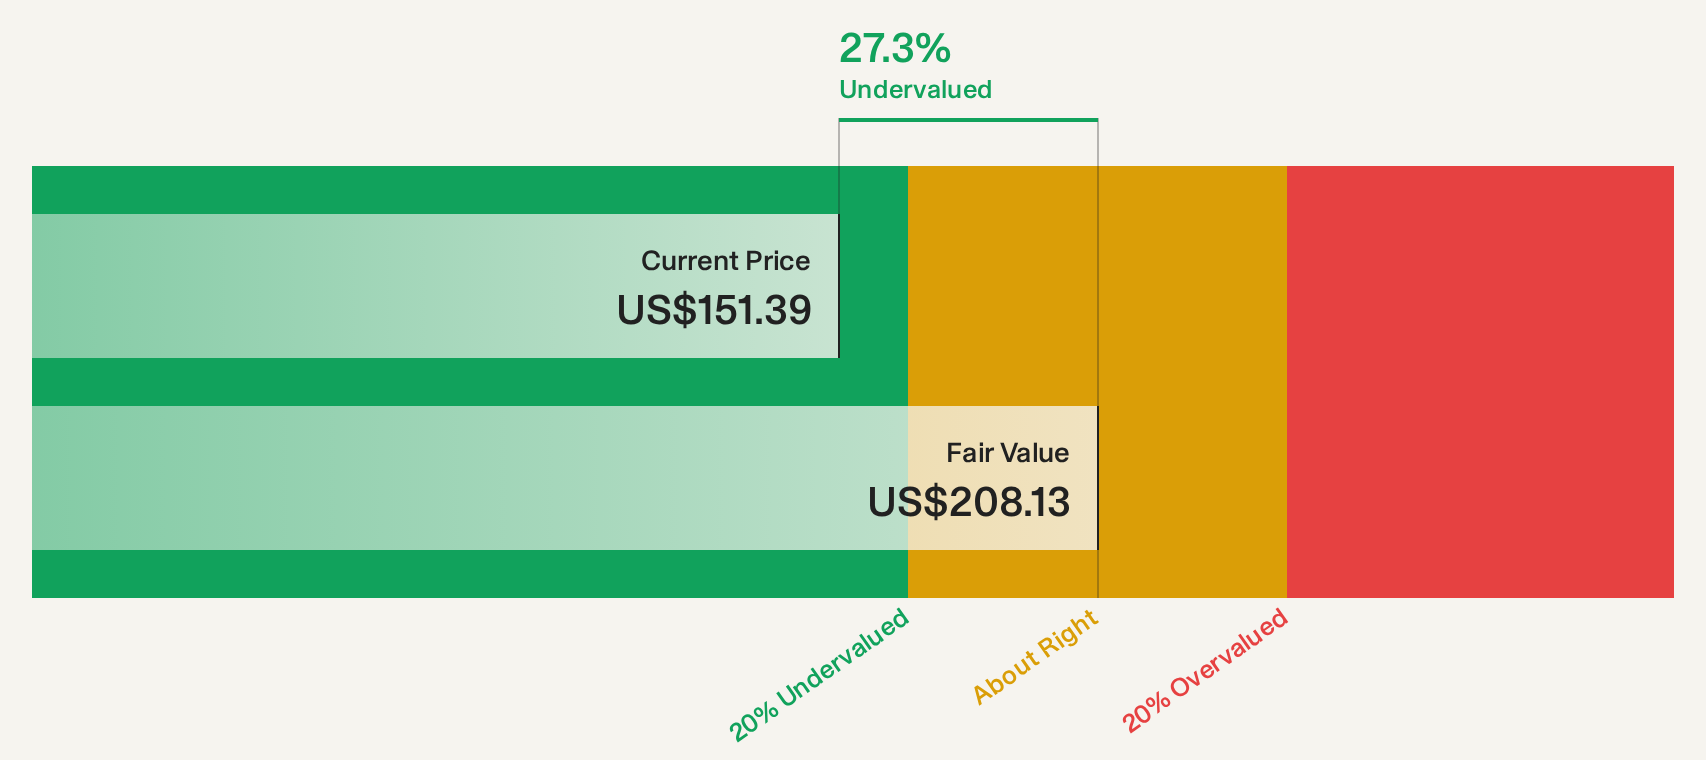
Estimated Discount To Fair Value: 27.2%
PJT Partners is trading at US$151.47, below its estimated future cash flow value of US$208.12, suggesting undervaluation based on cash flows. Despite significant insider selling recently, the company reported strong earnings growth with net income rising to US$45.83 million in Q2 2026 from US$32.9 million a year ago and continued share buybacks totaling over $500 million since 2024, enhancing shareholder value amid moderate revenue growth forecasts.
- In light of our recent growth report, it seems possible that PJT Partners' financial performance will exceed current levels.
- Click to explore a detailed breakdown of our findings in PJT Partners' balance sheet health report.
Seize The Opportunity
- Investigate our full lineup of 48 Undervalued US Stocks Based On Cash Flows right here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com