
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 Australian Founder Led Stocks To Watch In September 2026
Long term interest rates have been climbing as investors react to changing expectations around central bank policy. That move is putting more pressure on highly leveraged businesses and on companies that rely on cheap capital. Founder led Australian stocks can look different in this setting, because leadership often treats the business more like a personal legacy than a short term job. This article highlights three such companies from our screener.
The three founder led stocks below are just a sample from the broader universe, and the full screen surfaced 82 more businesses with equally compelling leadership stories that are not covered in this article. If you want to identify and analyze founder controlled opportunities that fit your own risk profile, go straight to the Founder-Led Companies screener.
Pro Medicus (ASX:PME)
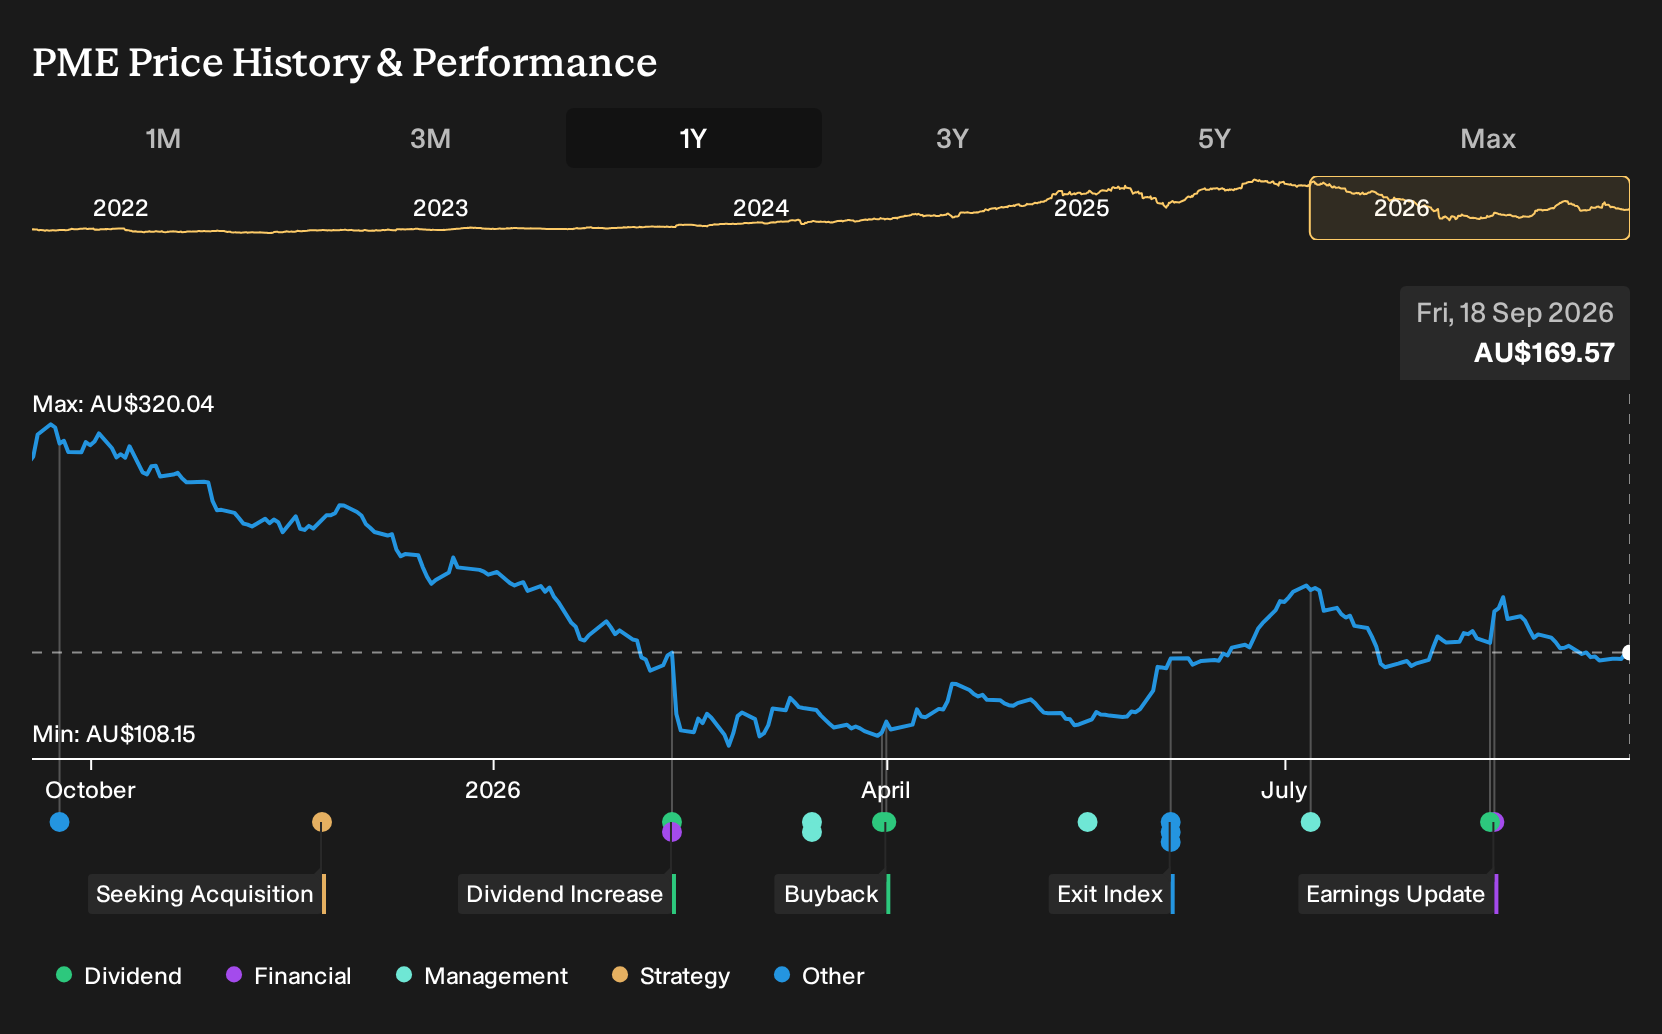
Pro Medicus is a textbook example of the founder-led theme in action, with long-tenured leaders still closely tied to the Visage imaging platform that anchors the whole business and gives radiologists a reason to insist their hospital runs this software.
Pro Medicus generates about A$261.7 million from integrated healthcare software such as Visage 7 and Visage RIS/PACS, making it a focused imaging informatics specialist with a market value near A$17.7b.
"Radiologists at top US hospitals have started demanding it as a condition of employment, and they simply won't join institutions that don't run Visage, the company's flagship imaging platform. Once embedded in a hospital's clinical workflow, the switching costs are enormous. Replacing a PACS system means retraining every radiologist, migrating years of archived images, and disrupting a mission-critical clinical function."
The real tension for Pro Medicus now is how one unseen shift in the economics around those premium contracts could ripple through future earnings power.
That risk sits alongside real upside for a platform this embedded, and the full narrative for Pro Medicus shows how contract structures, pricing power and capital discipline could keep value compounding.
Mesoblast (ASX:MSB)
Mesoblast is a pure-play on founder-led regenerative medicine, built around its mesenchymal lineage cell platform and long-term clinical programs that demand patient, owner-like leadership.
Mesoblast develops allogeneic cellular medicines, generating about $120 million from its allogeneic cellular medicines platform, and carries an A$2.7b market value that reflects investor focus on its founder-shaped cell therapy portfolio.
For a founder-led investor, this is where the story shifts from a big scientific vision to a concrete test of whether that platform can scale into durable commercial cash flows.
"The first and only FDA approved mesenchymal stromal cell product in the U.S., Ryoncil, together with over 1,100 patents and established commercial scale manufacturing, positions Mesoblast to benefit if cell therapies gain wider medical adoption. Expanding Ryoncil from pediatric to adult steroid refractory acute GvHD through an NIH backed pivotal trial with the Bone Marrow Transplant Clinical Trials Network targets a patient pool described as roughly 3x the size of the current pediatric population."
What matters next is how one unseen pressure on long-term pricing and reimbursement shapes the payoff from that founder-built platform.
Those pricing questions are already shaping expectations, and the full narrative for Mesoblast shows how Mesoblast could still turn its platform into accelerating cash generation if adoption broadens.

Harvey Norman Holdings (ASX:HVN)
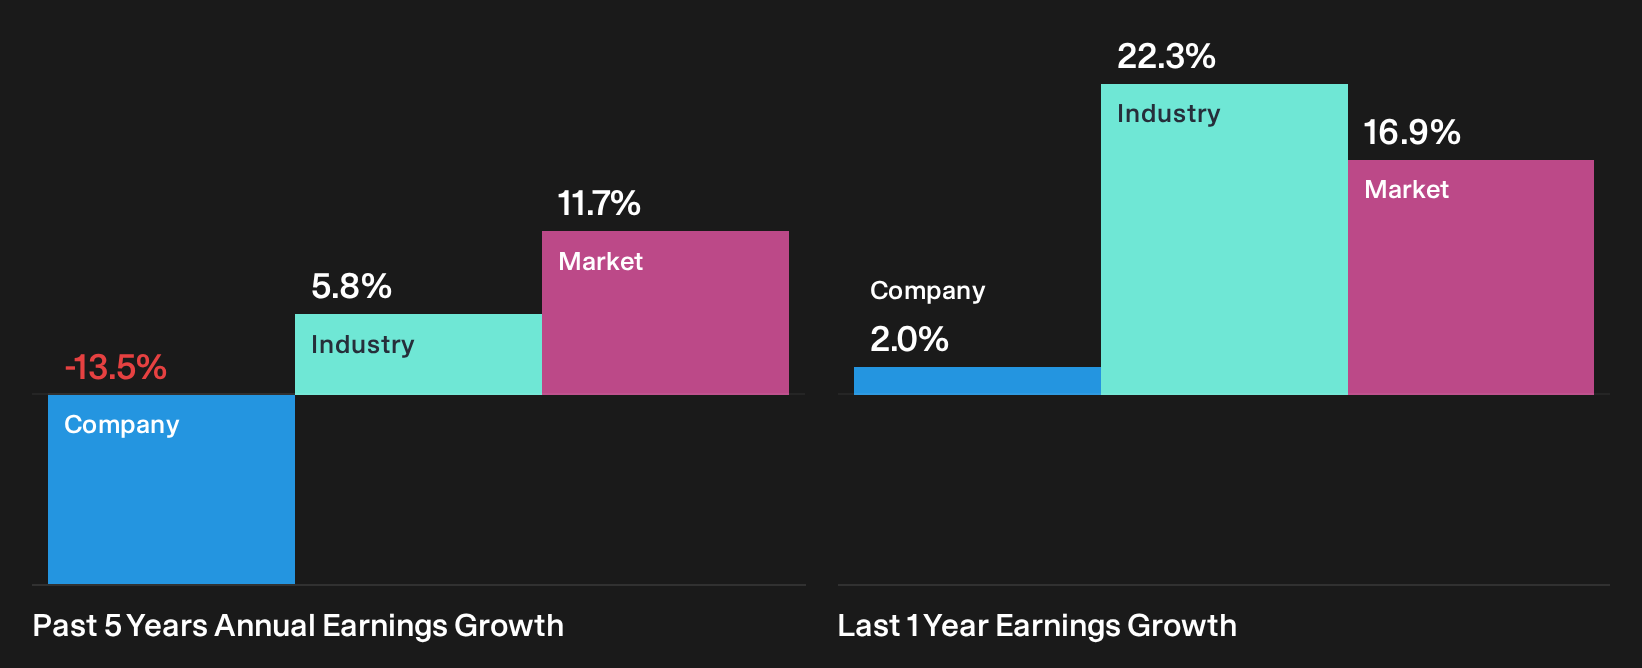
Harvey Norman Holdings brings a founder’s imprint to a broad retail and property platform, with Gerry Harvey’s ongoing control shaping how the business balances big-box stores, franchise income and a substantial property portfolio across Australia and offshore markets.
Harvey Norman Holdings runs furniture, bedding, electronics and computer stores, supported by franchising, property and digital systems. It generated about A$951.9 million from New Zealand, A$776.9 million from Ireland, A$787.2 million from Singapore and Malaysia, and A$231.5 million from non franchised outlets, with smaller contributions from the UK and Slovenia and Croatia. The group carries a market value near A$5.1b.
Founder-led continuity matters here because Harvey Norman ties long-standing family control directly to how it allocates capital between retail expansion, franchises and owned property. That is exactly what many investors want from this screener.
"That blue-chip character was challenged in 2025, when Harvey Norman reported net profit growth of 47% year-on-year, supported by robust Australian sales, international expansion and property revaluations."
One question is what happens if an unseen pressure on that profit mix starts to reshape how much of Harvey Norman’s gains prove repeatable.
That repeatability question is exactly what the full narrative for Harvey Norman Holdings tackles. It highlights where Harvey Norman Holdings’ profit mix could be decoupling from one-off gains and where founder control might accelerate value creation.
Seeking Fresh Alternatives Beyond Today?
Fresh opportunities move fast, and the stocks that look quiet now can be the ones breaking out next. Before momentum is fully caught by the crowd, consider positioning early.
- Spot cash-generating tech stories early by scanning the 38 profitable AI stocks that aren't just burning cash that already pair real revenue with AI exposure while they are still under the radar.
- Target resilient payers that can help steady a portfolio with the curated 4 dividend fortresses before yields change and investor attention potentially increases.
- Review the hand-picked 39 power grid technology and infrastructure stocks to follow developments in grid upgrade activity while these infrastructure-related names remain less widely discussed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com