
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Updated 2026 Guidance Require Action From Cheesecake Factory Stock Investors?
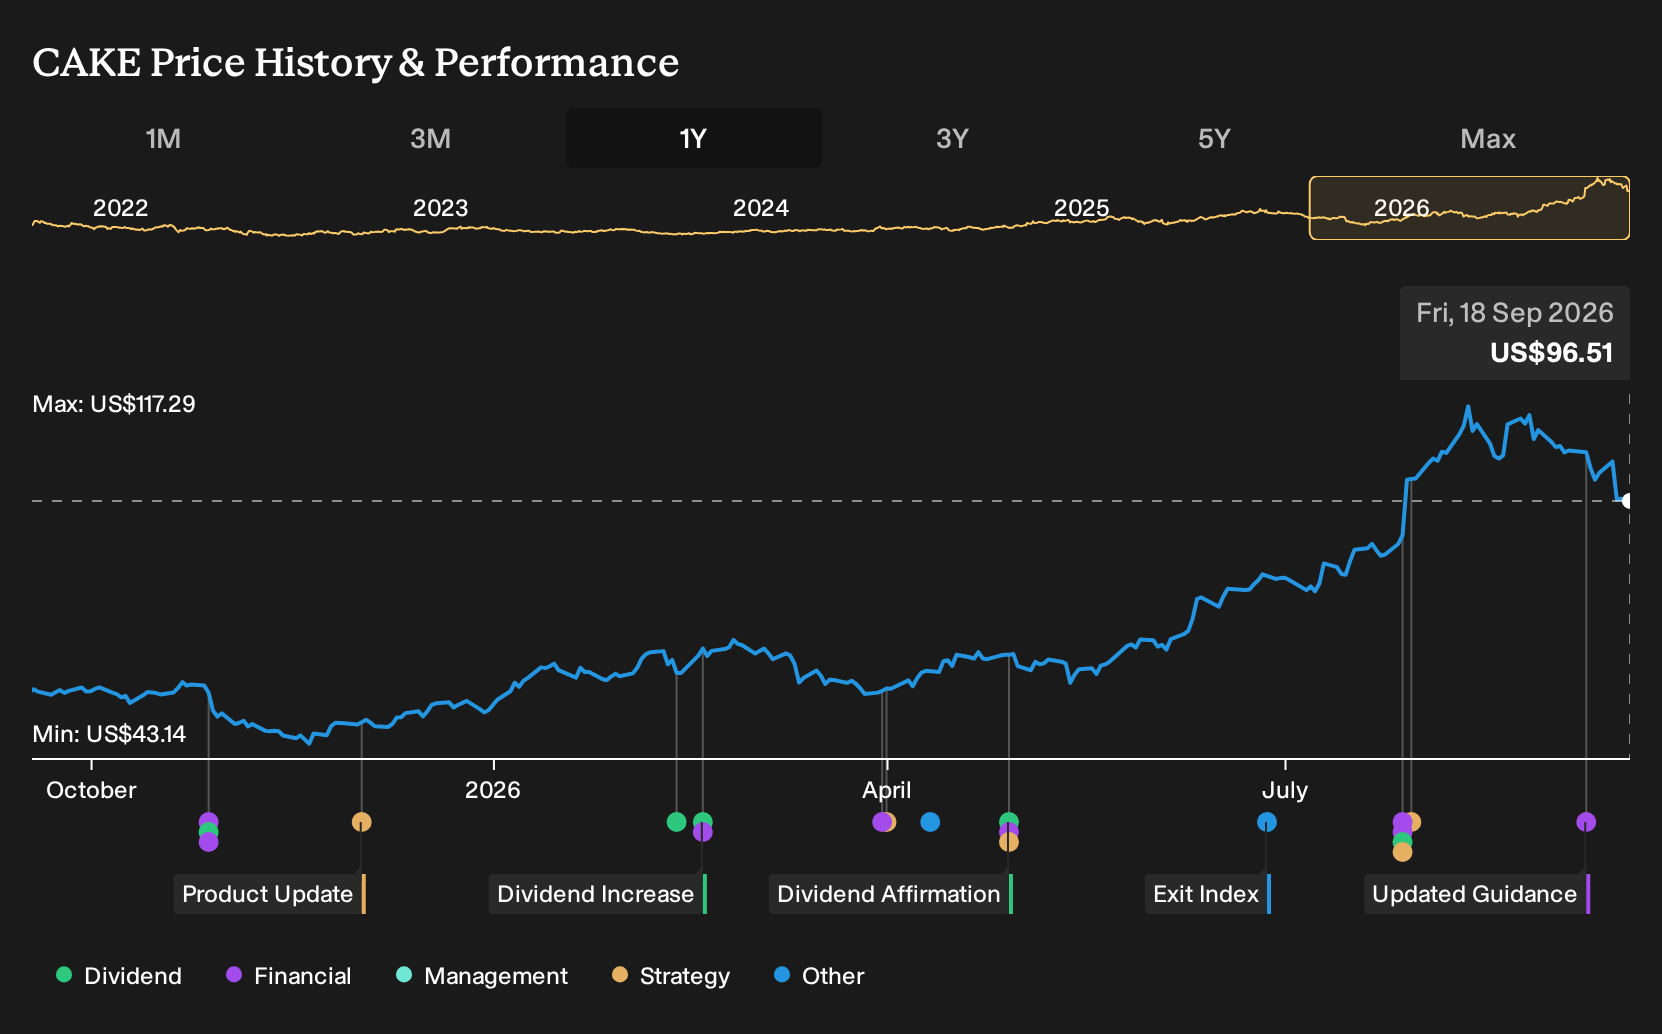
- In September 2026, The Cheesecake Factory updated its 2026 outlook, projecting about US$4b in total revenue and a net income margin near 5.4%.
- The guidance ties earnings expectations directly to profitability and gives investors a clearer view of how Cheesecake Factory aims to turn sales into cash flow.
- We will now explore how Cheesecake Factory's refreshed 2026 revenue and margin targets could reshape the existing investment narrative around the business.
Compare Cheesecake Factory's refreshed profit ambitions with other restaurant and consumer stocks targeting stronger earnings quality by scanning our 35 high quality undervalued stocks.
Cheesecake Factory Investment Narrative Recap
To own Cheesecake Factory, you need to be comfortable that a large, experience-focused dining model can still earn solid restaurant economics while consumer habits tilt toward off premise and digital-first formats. The updated 2026 guide for about US$4b of revenue and a roughly 5.4% net margin puts execution squarely on operating efficiency and mix rather than on sheer traffic gains.
The main short term swing factor is whether management can hold that margin target in the face of labor inflation and high occupancy costs in malls and prime retail sites. Traffic softness and competition from faster, lighter concepts remain the biggest operational risk. The new guidance refines expectations but does not radically change that balance.
Recent commentary around Cheesecake Factory has repeatedly emphasized restaurant level profitability and efficiency improvements, including reaching the highest four wall margin in eight years. The new 5.4% net income margin goal effectively extends that story, since it links corporate profitability to what is happening at the unit level across Cheesecake Factory, North Italia, Flower Child and other Fox concepts.
For investors, this matters because the key catalyst today is margin follow through, not just revenue size. If restaurant level economics stay healthy while the company continues to expand concepts like Flower Child with mature unit margins over 20%, the updated 2026 margin ambition becomes a live test of how scalable that operating playbook really is against pressures from labor, leases and evolving guest preferences.
Cheesecake Factory's current analyst narrative points to about US$4.8b of revenue and US$334.2m of earnings by 2029, based on an assumed 7.6% yearly rise in revenue and an earnings increase of roughly US$155.6m from US$178.6m today.
Uncover why Cheesecake Factory's fair value is essentially in line with its current price.
Exploring Other Perspectives
One alternate view on Cheesecake Factory leans hard into cost risk. The most cautious analysts were working off roughly US$4.7b of 2029 revenue and about US$322.1m of earnings, and still argued that higher wage and ingredient costs could keep pressure on profitability. Those opinions pre date the new 2026 guidance, so you may see them shift as fresh numbers filter through.
Explore 4 other Cheesecake Factory fair value estimates, including one that suggests as much as 26% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cheesecake Factory research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cheesecake Factory. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cheesecake Factory's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cheesecake Factory?
If the Cheesecake Factory story has you thinking about where else earnings quality and resilient cash generation might show up, using a structured stock screener can help you quickly focus on companies that fit the way you like to invest.
- Prefer to start with value and financial strength together, rather than chasing headlines, by scanning a curated set of 35 high quality undervalued stocks that pair quality fundamentals with discounted prices.
- If income is a priority for your portfolio construction, you can zero in on established payers with a 7 dividend fortresses that concentrates on higher yielding opportunities.
- For a focus on resilience, especially when you care about balance sheet quality and downside risk, filter for companies on our 30 resilient stocks with low risk scores and build a watchlist from there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com