
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Sally Beauty Stock After Yellow Professional Retail Launch
- Yellow Professional announced its first U.S. retail rollout with Sally Beauty Holdings, placing four targeted haircare collections and multiple hero treatments across Sally Beauty stores and SallyBeauty.com at accessible price points.
- The move extends Sally Beauty Holdings' portfolio of professional-grade brands and gives the retailer another exclusive-style offering aimed at specific hair concerns such as color care, damage repair, nourishment and tone correction.
- We will now examine how Sally Beauty Holdings' investment narrative could be affected by this wider professional brand assortment and category reach.
Explore how Sally Beauty Holdings fits into a broader retail and beauty thesis by comparing it with a curated set of 16 high quality undiscovered gems that may be flying under most investors' radar.
Sally Beauty Holdings Investment Narrative Recap
Sally Beauty Holdings appeals to investors who think a focused specialty retailer can keep serving value driven DIY and professional shoppers while holding on to margins through exclusive brands and cost discipline. The key near term swing factor is whether softer care categories and trade down behavior stabilize. The Yellow Professional rollout helps expand assortment, although on its own it does not transform that demand picture.
The biggest operational risk remains a heavy store footprint paired with modest e commerce penetration, especially as larger beauty retailers and online players compete for the same customers. This new brand launch fits management’s push into higher margin, professional grade offerings, yet it does not fully offset the structural pressures from debt levels, store rationalization and slower category growth.
Among recent developments, the Yellow Professional nationwide launch at Sally Beauty stores and online is most relevant here. It directly ties into management’s focus on professional quality, exclusive style offerings that can support gross margin and basket size. The assortment targets color care, repair, nourishment and tone correction, which are areas where customers often trade up in efficacy even when budgets are tight.
For catalysts, investors may watch how this partnership interacts with Sally Beauty’s digital initiatives and store refresh efforts. If the brand draws incremental traffic to SallyBeauty.com or supports higher tickets in refreshed stores, it could reinforce the existing thesis around value priced, professional formulas and justify continued investment in similar brand partnerships, while still leaving macro sensitivity and competitive intensity as key watchpoints.
Sally Beauty Holdings' current analyst narrative points to revenue of US$3.9b and earnings of US$260.8m by 2029, based on expected yearly top line growth of 1.7%. That profile assumes current earnings of US$183.9m. This would require an earnings increase of about US$76.9m to reach the 2029 consensus level.
Uncover why Sally Beauty Holdings' fair value indicates a 4% potential upside to its current price that may not last much longer.
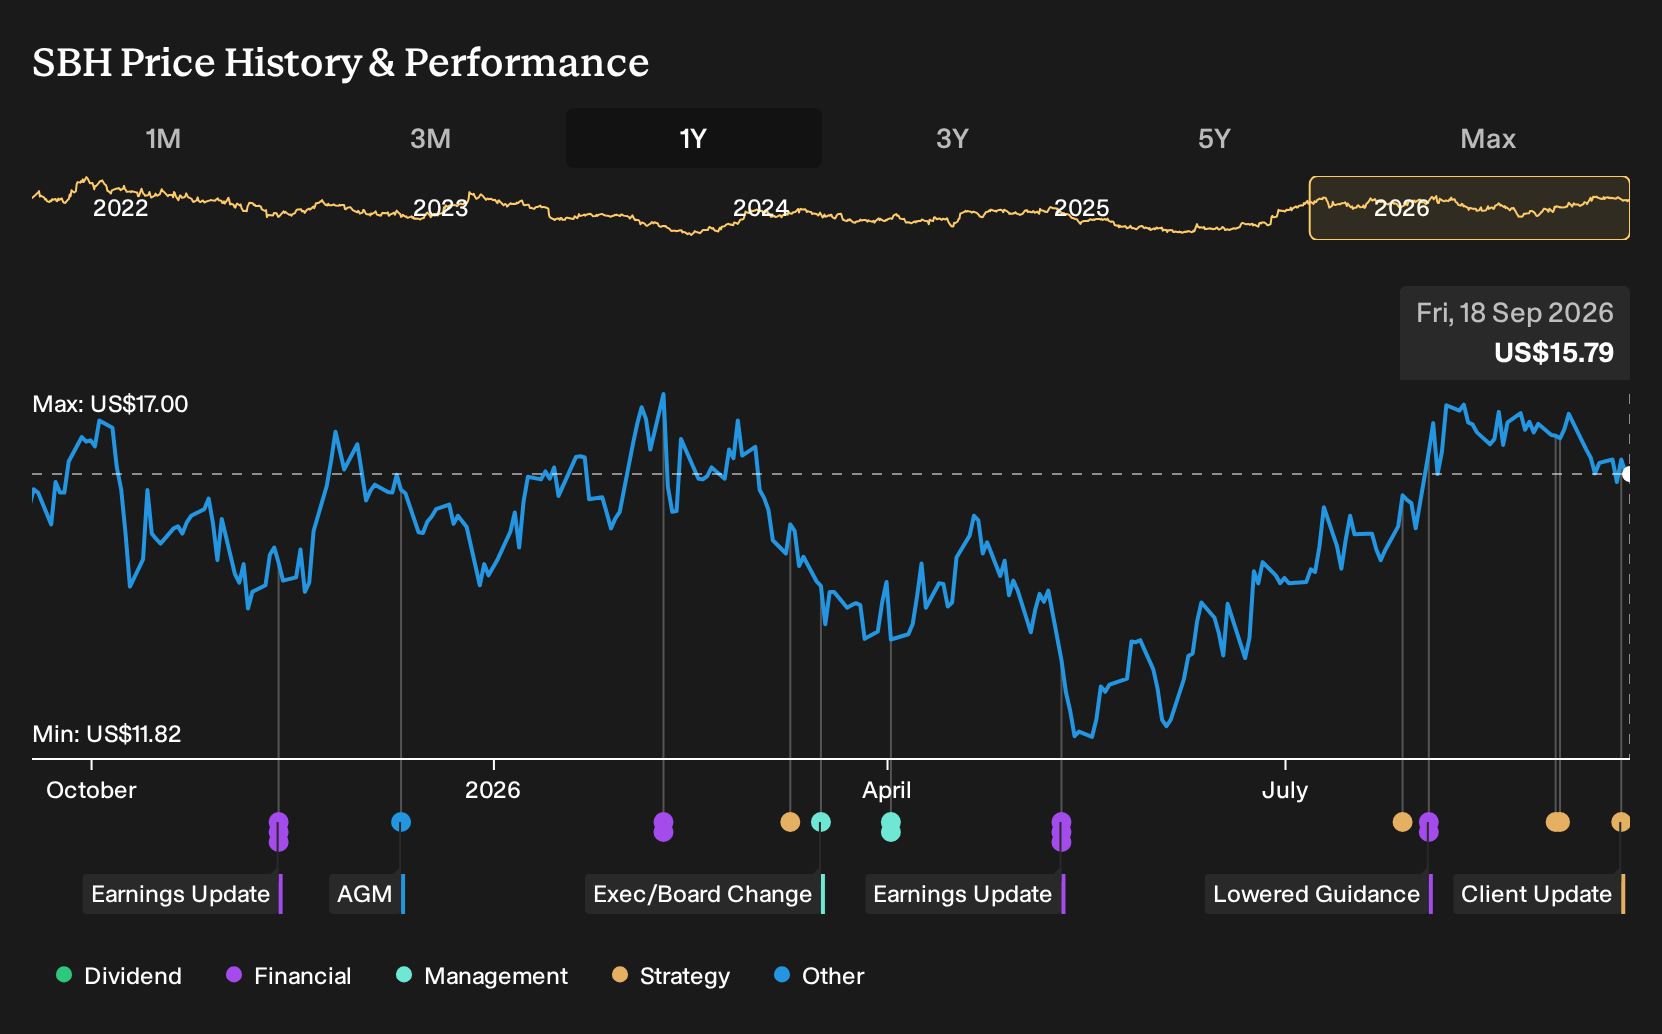
Exploring Other Perspectives
One alternate view focuses less on store refreshes and more on Sally Beauty Holdings’ digital push. The most optimistic analysts already had models with revenue at about US$3.9b and earnings near US$260.7m by 2029 before this Yellow Professional deal. You can compare those upbeat forecasts with your own assumptions and see how this launch might shift them.
Explore 2 other Sally Beauty Holdings fair value estimates, including one that indicates the potential for up to 339% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sally Beauty Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sally Beauty Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sally Beauty Holdings' overall financial health at a glance.
Looking for more Sally Beauty Holdings sized ideas?
If you want to stress test your view on Sally Beauty Holdings, it helps to line it up against other businesses with different risk, quality and income profiles. The Simply Wall St Screener gives you a straightforward way to do that by filtering for financial traits that matter to you.
- For investors who care most about value and quality together, compare Sally Beauty Holdings with a curated set of 35 high quality undervalued stocks that pair stronger fundamentals with discounted prices.
- If capital preservation is higher on your list, balance your Sally Beauty Holdings thesis by checking a 30 resilient stocks with low risk scores that screens for sturdier balance sheets and more resilient risk scores.
- Income focused readers can round out a position in Sally Beauty Holdings by reviewing a 7 dividend fortresses that concentrates on higher yielding companies with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com