
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Amazon (AMZN) Stock May Still Have Upside Following AI Infrastructure Deals
Amazon.com has delivered a 93.3% share price gain over the past three years, and with the stock last closing at US$253.71, the question for investors is how firmly that move is rooted in the cash the business can generate.
- A 93.3% return over three years puts a lot of expectation into Amazon.com stock, which raises the stakes on whether its future cash flows can support that kind of re-rating.
- Heavy commitments to AI data centers, satellite internet and wage increases, including the recent £4.25b bond issue to fund AI infrastructure and multi billion generator and chip partnerships, may support revenue growth but also pull forward large capital and operating outlays that feed directly into cash flow forecasts.
- Prefer to judge Amazon.com on earnings? See what Amazon.com's 20.2x P/E says about the price.
For investors, the debate is whether Amazon.com's current share price is adequately supported by its projected cash flows when assessed against the Discounted Cash Flow (DCF) view of intrinsic value.
If you are weighing whether Amazon.com's cash flows justify its recent re-rating, it can help to benchmark that question against a broader set of 88 AI infrastructure stocks.
Is Amazon.com a Bargain on Cash Flow?
The Discounted Cash Flow model values Amazon.com by projecting the cash it could return to shareholders and then discounting those streams back to today. On this view, the latest twelve month free cash flow sits at about $32.6b, and the forecasts assume that this figure grows from here rather than shrinking or staying flat.
Those projections build in a swing from a forecast free cash flow shortfall in 2027 to sizeable positive cash generation by the end of the decade. This lines up with Amazon.com leaning hard into AI data centers, satellite broadband and higher wage bills today. The recent £4.25b sterling bond deal to fund AI infrastructure helps explain why the Discounted Cash Flow output still puts Amazon.com's estimated intrinsic value substantially above the current share price of US$253.71. Find out what Amazon.com could be worth using our Discounted Cash Flow (DCF) estimate.
The Amazon.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Amazon.com pick up where the valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or materially less than it is today. Rather than focusing on a single headline multiple or one model output, each narrative lays out the assumptions behind its view of fair value so you can compare those expectations with the numbers Amazon.com actually reports over time on the Community page.
Community views on Amazon.com sit on opposite sides of the valuation fence, with one group focused on AI upside and another anchored in stricter cash flow maths.
Bull case: 44% undervalued
"Amazon is sacrificing short-term margins to secure long-duration dominance in AI infrastructure, advertising, and automated commerce..."
Discover why this Narrative puts Amazon.com at 44% undervalued.
Bear case: 51% overvalued
"As you can see from the above Amazon seems to be overvalued given that its current price of 198.22 dollars is above P90..."
Explore why this Narrative puts Amazon.com at 51% overvalued.
One more Amazon.com check that sits outside the cash flow debate
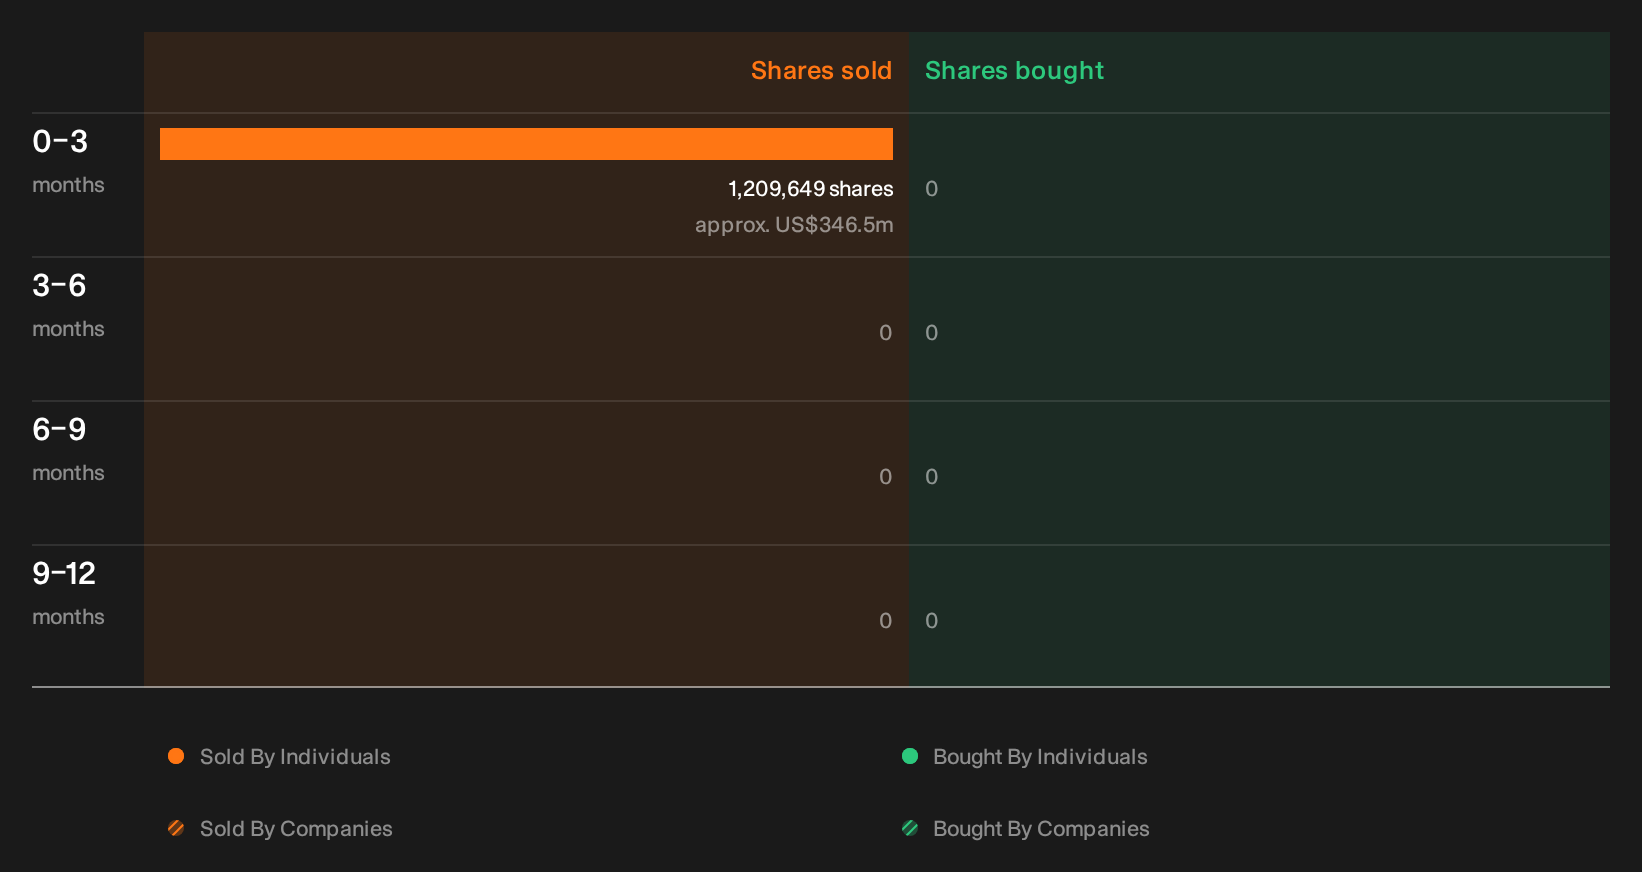
Price, cash generation and narratives all matter for Amazon.com, but our checks also picked up recent share sales by people inside the business, and the who, how much and potential meaning are still for you to unpack. See the recent insider selling flagged for Amazon.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com