
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Terreno Realty (TRNO) Fairly Valued As Lease Renewals Extend Income Visibility?
Terreno Realty (TRNO) recently secured early lease renewals on three Sunnyvale buildings with a molecular diagnostic testing tenant, extending 172,000 square feet of occupancy commitments through March 2035.
Terreno Realty’s share price has risen 11.4% year to date to US$65.75, with the 1-year total shareholder return of 15.65% and 3-year total shareholder return of 25.32% pointing to momentum that investors may now be reassessing in light of these longer lease commitments.
Scan other industrial REITs with long-term tenant visibility by running the same filter used to surface Terreno Realty through our curated 30 resilient stocks with low risk scores list.
For Terreno Realty, that recent climb could signal that investors are rewarding a business with clearer cash flow visibility, or it could simply reflect changing sentiment toward industrial REITs. Which story does the current valuation tell?
Price-to-Earnings of 18.5x: Is it justified?
Terreno Realty trades on a P/E of 18.5x, and the SWS DCF model estimates fair value at $66.63 versus the last close of $65.75, which points to a slight discount rather than an obvious premium.
The P/E ratio compares what investors pay today for each dollar of current earnings, so it can reflect expectations about the durability of those earnings. For an industrial REIT like Terreno Realty, that often ties back to contracted rent, lease terms, and how much future income might be affected by items that are not part of everyday operations.
In Terreno Realty’s case, recent financials include a large one off gain of $210.9m, and earnings are forecast to decline by an average of 12.8% per year for the next 3 years while revenue is projected to grow 10.4% per year. That mix suggests the current earnings base may be flattered by non recurring items, while the market values the stock below an estimated fair P/E of 26.1x, implying the ratio could move higher if earnings normalize closer to underlying cash flows.
Against the wider Global Industrial REITs group, Terreno Realty’s 18.5x P/E screens as expensive versus the 15.5x industry average, yet it looks inexpensive compared to a 37.3x peer average and the 26.1x fair P/E estimate that regression analysis implies the market could eventually lean toward.
Explore the SWS fair ratio for Terreno Realty.
Result: Price-to-earnings of 18.5x (ABOUT RIGHT)
Still, Terreno Realty faces risks if tenant demand in its six coastal markets weakens, or if the one-off gain distorts how investors read current earnings power.
Find out about the key risks to this Terreno Realty narrative.
Another View on Terreno Realty’s Value
A second lens on Terreno Realty comes from the SWS DCF model, which puts fair value at $66.63 compared with the recent $65.75 share price. That implies a small discount rather than a clear bargain or bubble. Is this a narrow margin of safety or just noise around fair value?
Look into how the SWS DCF model arrives at its fair value.
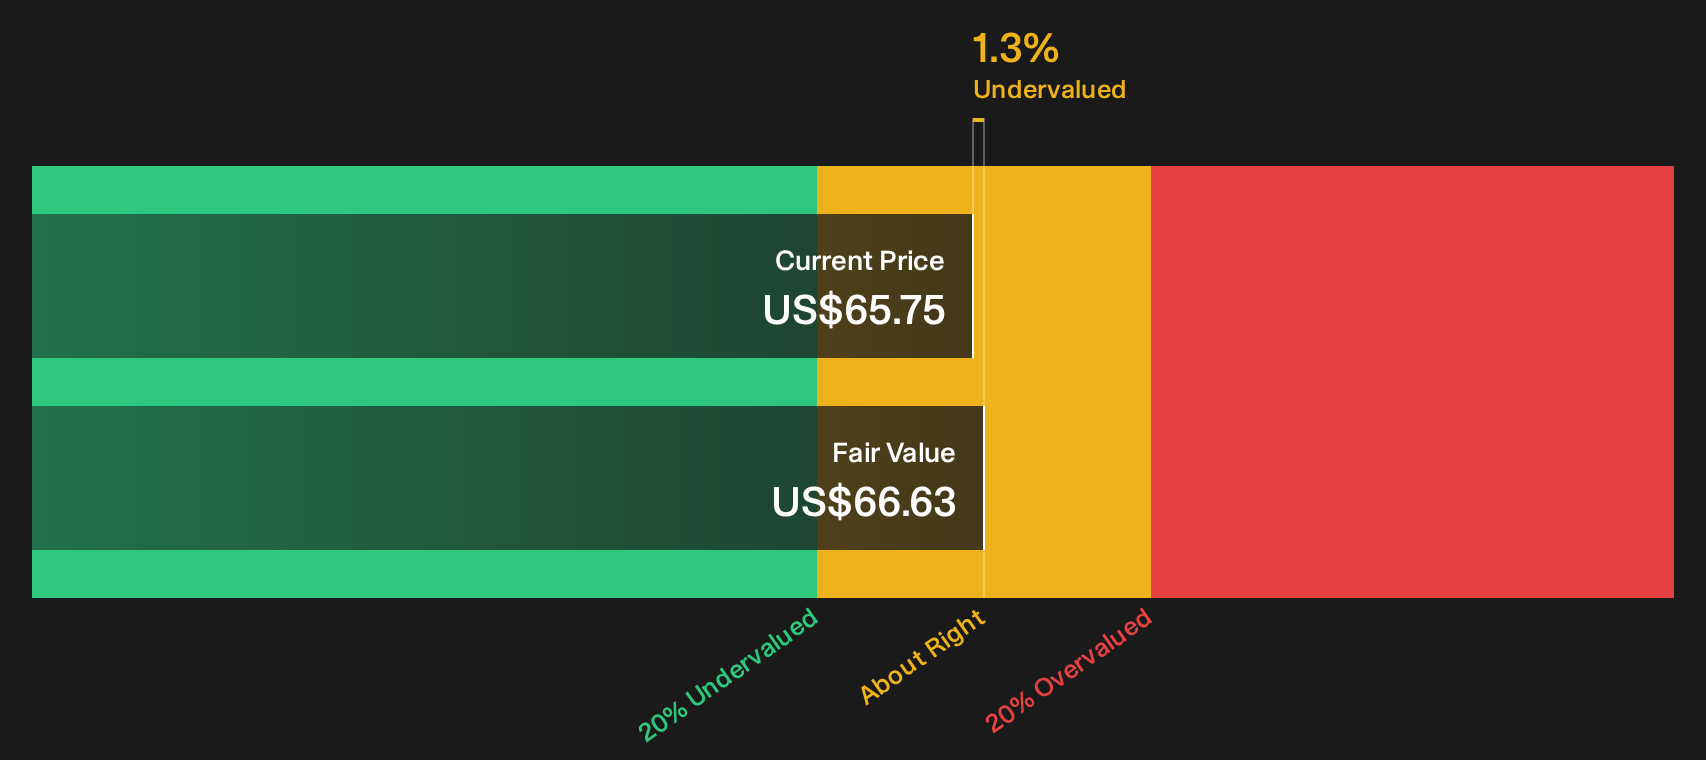
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Terreno Realty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the numbers, or a clear signal forming around Terreno Realty? Act while the data is fresh and weigh both sides of the story by checking the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Terreno Realty?
Once you have formed a view on Terreno Realty, do not stop there. Use fresh screens to spot other opportunities before the crowd notices them.
- Target long term wealth builders by scanning for quality companies trading below what fundamentals suggest through the 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on resilient payers screened through the 7 dividend fortresses.
- Prioritise financial resilience by filtering for companies with strong balance sheets using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com