
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
September 2026's Global Growth Stocks With Insider Confidence
In September 2026, global markets have been navigating a complex landscape marked by rising interest rates and geopolitical tensions, with growth stocks notably outperforming their value counterparts despite these challenges. As investors seek opportunities in this environment, companies with high insider ownership often attract attention due to the perceived alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Zhejiang Taotao Vehicles (SZSE:301345) | 27.9% | 30.6% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 126% |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Meitu (SEHK:1357) | 22.9% | 30.7% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| CD Projekt Red (WSE:CDR) | 35.2% | 47.9% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's explore several standout options from the results in the screener.
EO Technics (KOSDAQ:A039030)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: EO Technics Co., Ltd. manufactures and supplies laser processing equipment globally, with a market cap of ₩5.59 trillion.
Operations: The Semiconductor Machine Division generated revenue of ₩444.72 billion.
Insider Ownership: 30.2%
EO Technics demonstrates strong growth potential with earnings forecasted to increase 22.33% annually, outpacing the KR market's revenue growth but slightly lagging in profit growth. Recent earnings surged by 157.5%, highlighting robust performance. However, its share price has been highly volatile over the past three months, and future Return on Equity is expected to be relatively low at 19.3%. No substantial insider trading activity was reported recently.
- Unlock comprehensive insights into our analysis of EO Technics stock in this growth report.
- Upon reviewing our latest valuation report, EO Technics' share price might be too optimistic.

InnoScience (Suzhou) Technology Holding (SEHK:2577)
Simply Wall St Growth Rating: ★★★★★☆
Overview: InnoScience (Suzhou) Technology Holding Co., Ltd. operates in the technology sector and has a market cap of approximately HK$40.37 billion.
Operations: The company generates revenue primarily through the sales of GaN Power Semiconductor Products, amounting to CN¥1.49 billion.
Insider Ownership: 12.5%
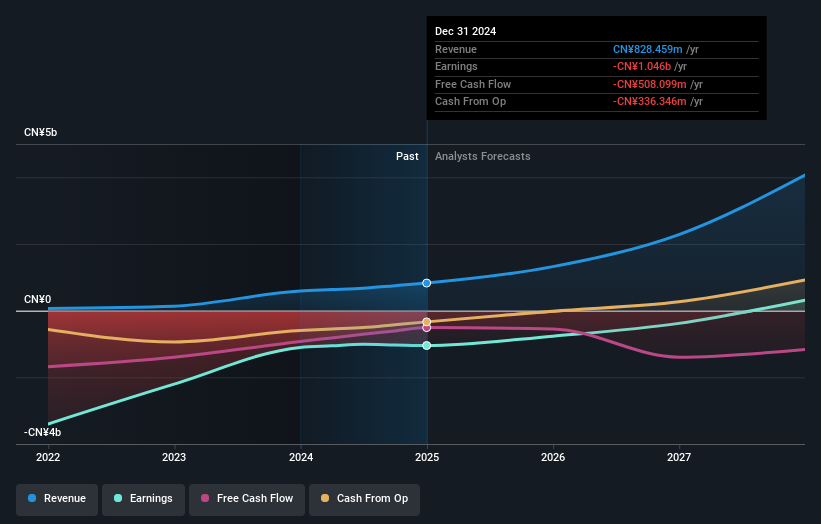
InnoScience (Suzhou) Technology Holding shows promising growth potential, with revenue expected to grow 36.7% annually, surpassing market averages. The company reported a reduction in net loss from CNY 428.67 million to CNY 309.08 million for the recent half-year period, reflecting improved financial performance. Despite low forecasted Return on Equity of 13.3%, it is anticipated to become profitable within three years, supported by high insider ownership and no substantial recent insider trading activity.
- Delve into the full analysis future growth report here for a deeper understanding of InnoScience (Suzhou) Technology Holding.
- Insights from our recent valuation report point to the potential overvaluation of InnoScience (Suzhou) Technology Holding shares in the market.
Kaori Heat Treatment (TWSE:8996)
Simply Wall St Growth Rating: ★★★★★★
Overview: Kaori Heat Treatment Co., Ltd. specializes in the research, development, manufacture, and sale of heat exchangers and thermal energy products across Taiwan, Asia, the United States, Europe, and other international markets with a market cap of NT$126.95 billion.
Operations: Kaori Heat Treatment's revenue is primarily derived from its Plate Heat Exchanger segment, which generated NT$1.88 billion, and its Fuel, Electricity and Thermal Energy segment, contributing NT$7.93 billion.
Insider Ownership: 10.3%
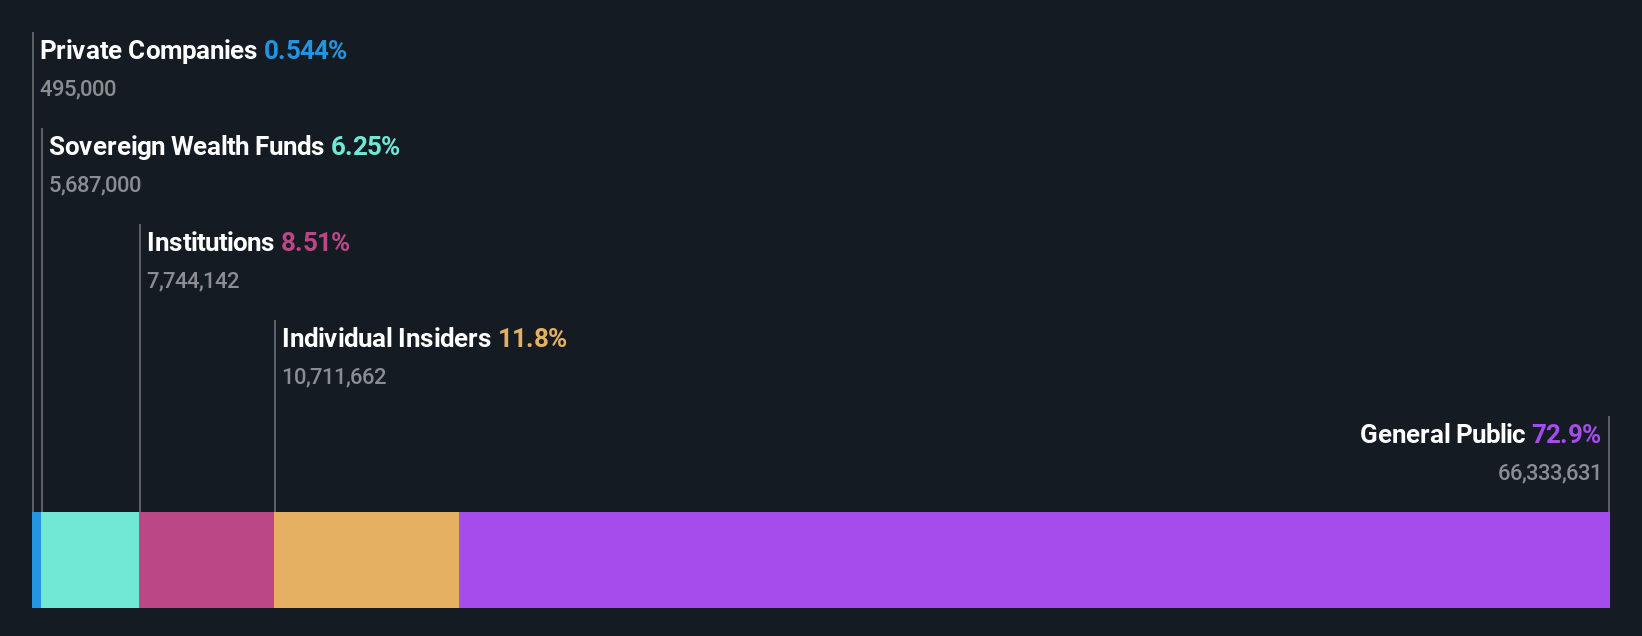
Kaori Heat Treatment demonstrates strong growth potential, with earnings projected to grow significantly at 60.6% annually, surpassing the TW market average. Recent financial results show substantial revenue and net income increases, with six-month sales reaching TWD 5.73 billion and net income at TWD 806.5 million. Despite high share price volatility recently, the company's forecasted Return on Equity is very high at 59.5%, indicating robust future profitability prospects without notable insider trading activity recently.
- Take a closer look at Kaori Heat Treatment's potential here in our earnings growth report.
- The analysis detailed in our Kaori Heat Treatment valuation report hints at an inflated share price compared to its estimated value.
Summing It All Up
- Embark on your investment journey to our 724 Fast Growing Global Companies With High Insider Ownership selection here.
- Ready To Venture Into Other Investment Styles? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com