
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Australian Quality Stocks With ROE Over 28%
The Federal Reserve’s latest rate hike has pushed borrowing costs higher and reminded investors that easy money is no longer a given. In that kind of world, strong balance sheets and high return on equity in Australian companies can matter far more than speculative stories. This article walks through three stocks from a quality screener designed to spotlight robust finances and solid track records.
The three examples below are just a starting sample, and the full screen surfaced 9 more businesses with equally strong balance sheets and returns that are not covered here but may deserve a spot on your watchlist. To see the full field and quickly identify which ones best fit your own criteria, head straight into the Solid Balance Sheet and Fundamentals screener.
Pro Medicus (ASX:PME)
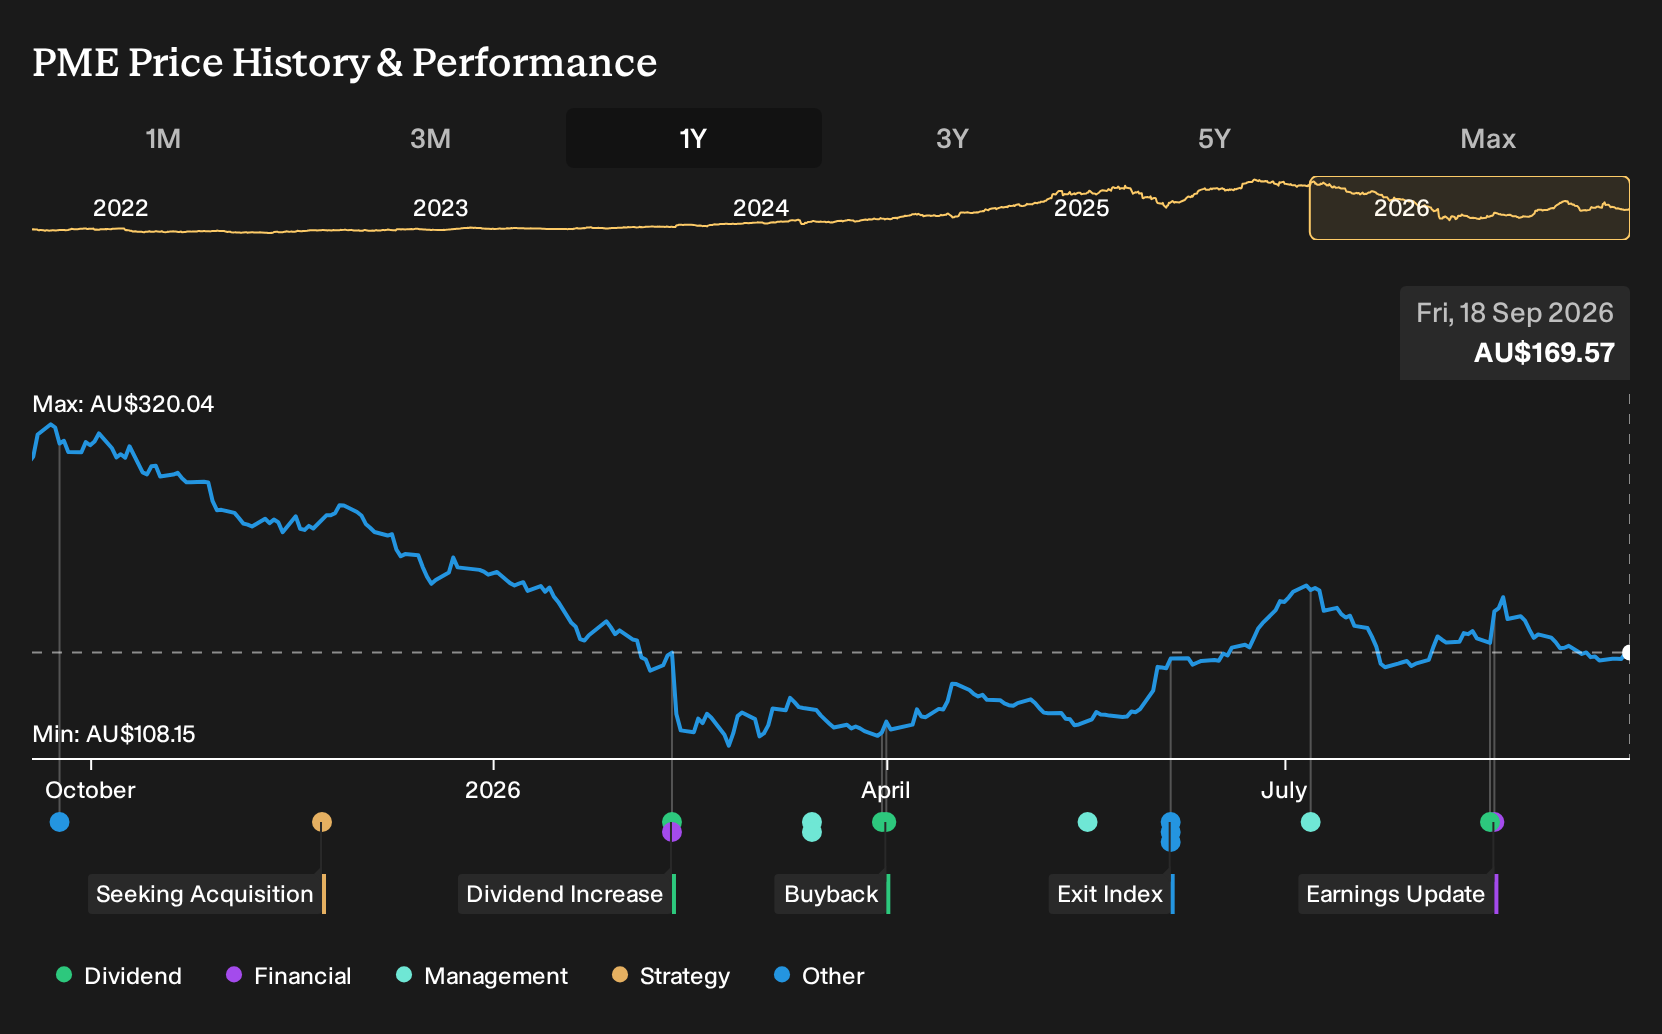
Pro Medicus fits directly into the Solid Balance Sheet and Fundamentals theme because its Visage imaging software is embedded in hospital workflows and earns recurring fees, which supports high returns on equity and a sizeable A$17.7b market valuation.
Pro Medicus generates revenue primarily from producing integrated software applications for the health care industry, with about A$261.7 million linked to that segment, supported by hospitals and imaging groups across Australia, Europe, and North America.
For a screener built around quality and staying power, Pro Medicus is a textbook example of how a mission critical platform can underpin resilient profits and capital strength without relying on financial engineering.
"Pro Medicus has had a 100% customer renewal rate since 2009. Not one hospital has ever left."
What matters from here is how one less visible pressure on its economics develops over the next few years.
That pressure point is exactly what sits at the heart of the full narrative for Pro Medicus, where you see how Pro Medicus could keep compounding or stall.
Resolute Mining (ASX:RSG)
Resolute Mining is a Perth based gold producer with operations across West Africa that leans on disciplined mine development to support the Solid Balance Sheet and Fundamentals theme. Most of its income comes from Syama in Mali at about US$696.2 million and Mako in Senegal at roughly US$306.6 million, backing an equity value near A$2.9b.
For this screener, Resolute Mining matters because its core West African projects tie tangible gold output directly to returns on equity and balance-sheet strength rather than one off exploration stories.
"The Doropo, ABC, and La Debo projects in Côte d'Ivoire, alongside the Syama Sulphide Conversion Project and life extension at Mako (through Bantaco and Tomboronkoto), are expected to significantly increase production volumes to over 500,000 ounces by 2028, driving sustained top-line growth and greater economies of scale that can enhance profitability."
What could really move the dial is how one less visible swing factor ultimately feeds through to cash costs and margins over the next few years.
If that swing factor is what you care about, read the full narrative for Resolute Mining to see how Resolute Mining’s cost base and cash generation could really accelerate.

Codan (ASX:CDA)
Codan is a communications and metal detection specialist where the mission critical DTC and Zetron radio systems tie it most directly to the Solid Balance Sheet and Fundamentals theme, with A$506 million from Communications and A$362 million from Metal Detection supporting an A$9.1b market value.
Codan matters here because its Communications arm is focused on long term, high margin contracts with governments and corporates. This is the kind of earnings quality this screener looks for, even as the wider business remains exposed to more cyclical metal detection demand.
"Rising global regulatory pressure and compliance costs surrounding supply chain transparency and electronic waste are likely to increase Codan's operational expenses over the long term, potentially eroding net margins and raising ongoing cost of doing business."
What really counts is how one unresolved cost pressure interacts with expectations for high margins and premium returns over the next few years.
That unresolved pressure is exactly why it is worth reading the full narrative for Codan to see whether rising costs are masking Codan’s next leg of earnings power.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first, not loudest. While others react to headlines, you can spot potential breakout momentum that is currently under the radar. Consider acting early rather than waiting.
- Look for early leadership in smaller high potential businesses by scanning the curated 16 elite penny stocks with strong financials before momentum traders start focusing on the same stories.
- Follow structural demand for secure transaction rails and digital assets by tracking the hand picked 18 cryptocurrency and blockchain stocks while prices and expectations are still resetting.
- Assess potential uranium supply bottlenecks by reviewing the focused 19 nuclear energy infrastructure stocks before more capital targets the same infrastructure opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com