
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Twist Bioscience Stock Gains Lilly AI Drug Discovery Partnership Exposure
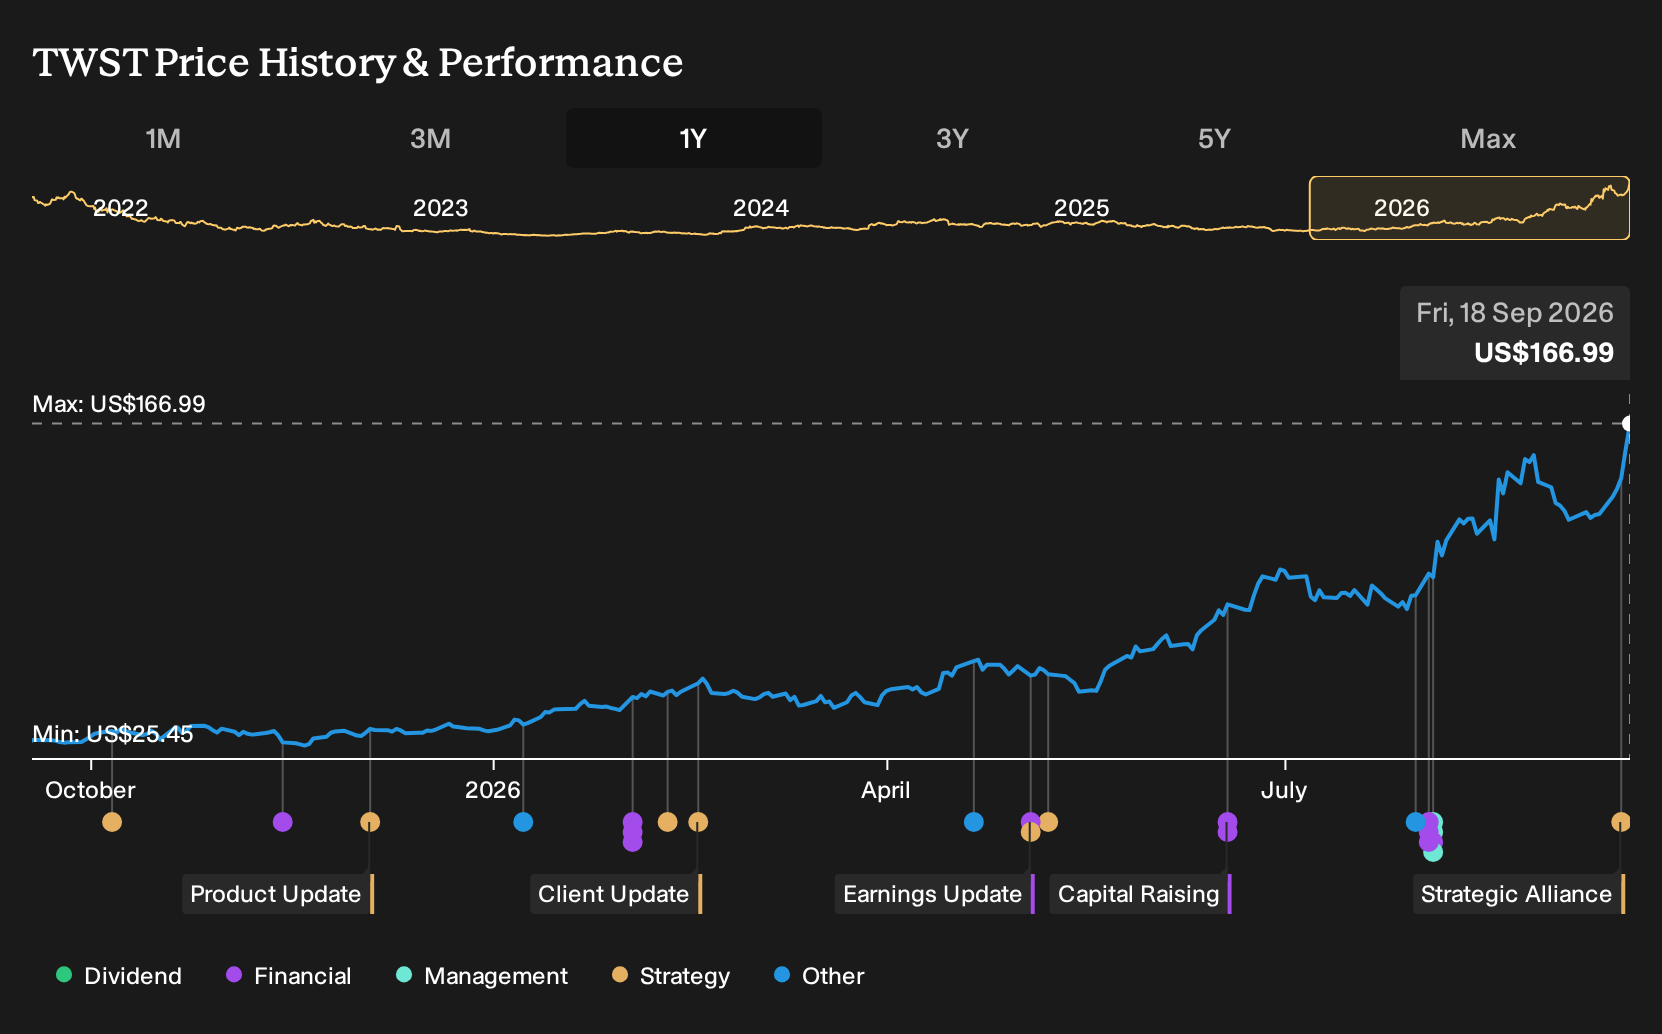
- Twist Bioscience announced an agreement in September 2026 to provide antibody characterization data services to Lilly TuneLab, integrating preferred Twist protocols into Eli Lilly's AI and machine learning drug discovery platform to generate high quality wet lab data.
- The arrangement connects Twist Bioscience directly to Lilly TuneLab's AI driven antibody developability models, which could deepen relationships with pharma and biotech customers that rely on faster antibody candidate selection and consistent experimental workflows.
- This section reviews how Twist Bioscience's role in supplying antibody data to Lilly TuneLab could influence how some investors think about the company.
Scan beyond Twist Bioscience and this Lilly TuneLab agreement by lining up other AI driven drug discovery players through our hand picked 37 healthcare AI stocks.
Twist Bioscience Investment Narrative Recap
To own Twist Bioscience, you need to believe its synthetic DNA and antibody tools can scale into a much larger role across pharma, biotech and diagnostics while the company works through ongoing losses. The Lilly TuneLab agreement fits that vision by tying Twist into AI driven antibody workflows. However, the near term focus still looks like gross margin execution and cost discipline rather than headline partnerships.
The biggest short term swing factor remains whether management can narrow the expected adjusted EBITDA loss of around $45 million to $47 million in fiscal 2025 and move closer to the internal breakeven goal. Persistent losses, a concentrated NGS customer base and a volatile share price keep funding risk and potential dilution very real for existing holders.
The Lilly TuneLab collaboration is the clearest recent announcement linked to AI driven drug discovery. It plugs Twist Bioscience protocols directly into Lilly’s AbLab and related models, which ties operational demand for antibody characterization services to a large pharma ecosystem. That supports the idea that pharma and biotech customers may increasingly lean on Twist for standardized, high quality data.
For catalysts, the more TuneLab users route projects through preferred Twist workstreams, the more evidence investors get on recurring demand and capacity utilization. That said, the partnership sits against a backdrop of an unprofitable business, a P/S of 24.3x versus lower peer averages, and expectations that Twist remains loss making for at least three years. As a result, execution on costs and contract stability still sets the tone.
Twist Bioscience's current earnings are a loss of US$136.7 million, while consensus expectations point to earnings of US$127.9 million and revenue of US$753.3 million by 2029. That outcome implies revenue growth of 20.4% per year and an earnings swing of about US$264.6 million from today to the 2029 forecast.
Uncover why Twist Bioscience's fair value indicates a 37% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Twist Bioscience’s margin potential rather than today’s losses. Before this Lilly TuneLab news, the bullish camp was already modeling about US$715.3 million of revenue and US$128.5 million of earnings by 2029. You can read that as a far more upbeat script that may evolve as this alliance plays out.
Explore 3 other Twist Bioscience fair value estimates, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Twist Bioscience research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Twist Bioscience. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Twist Bioscience's overall financial health at a glance.
Looking For More Ideas Beyond Twist Bioscience?
If the Twist Bioscience story has sharpened your thinking about risk, return and time horizon, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
- For investors who want quality at a discount, filter for companies with strong fundamentals trading below intrinsic value using our 35 high quality undervalued stocks.
- If capital preservation and smoother rides matter most to you, focus on businesses with resilient earnings and balance sheets through the 30 resilient stocks with low risk scores.
- When the goal is to uncover tomorrow’s potential leaders early, broaden the search with the 16 high quality undiscovered gems that combine solid metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com