
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rightmove plc (LON:RMV) Passed Our Checks, And It's About To Pay A UK£0.0417 Dividend
Regular readers will know that we love our dividends at Simply Wall St, which is why it's exciting to see Rightmove plc (LON:RMV) is about to trade ex-dividend in the next two days. The ex-dividend date is commonly two business days before the record date, which is the cut-off date for shareholders to be present on the company's books to be eligible for a dividend payment. The ex-dividend date is important as the process of settlement involves at least two full business days. So if you miss that date, you would not show up on the company's books on the record date. In other words, investors can purchase Rightmove's shares before the 24th of September in order to be eligible for the dividend, which will be paid on the 23rd of October.
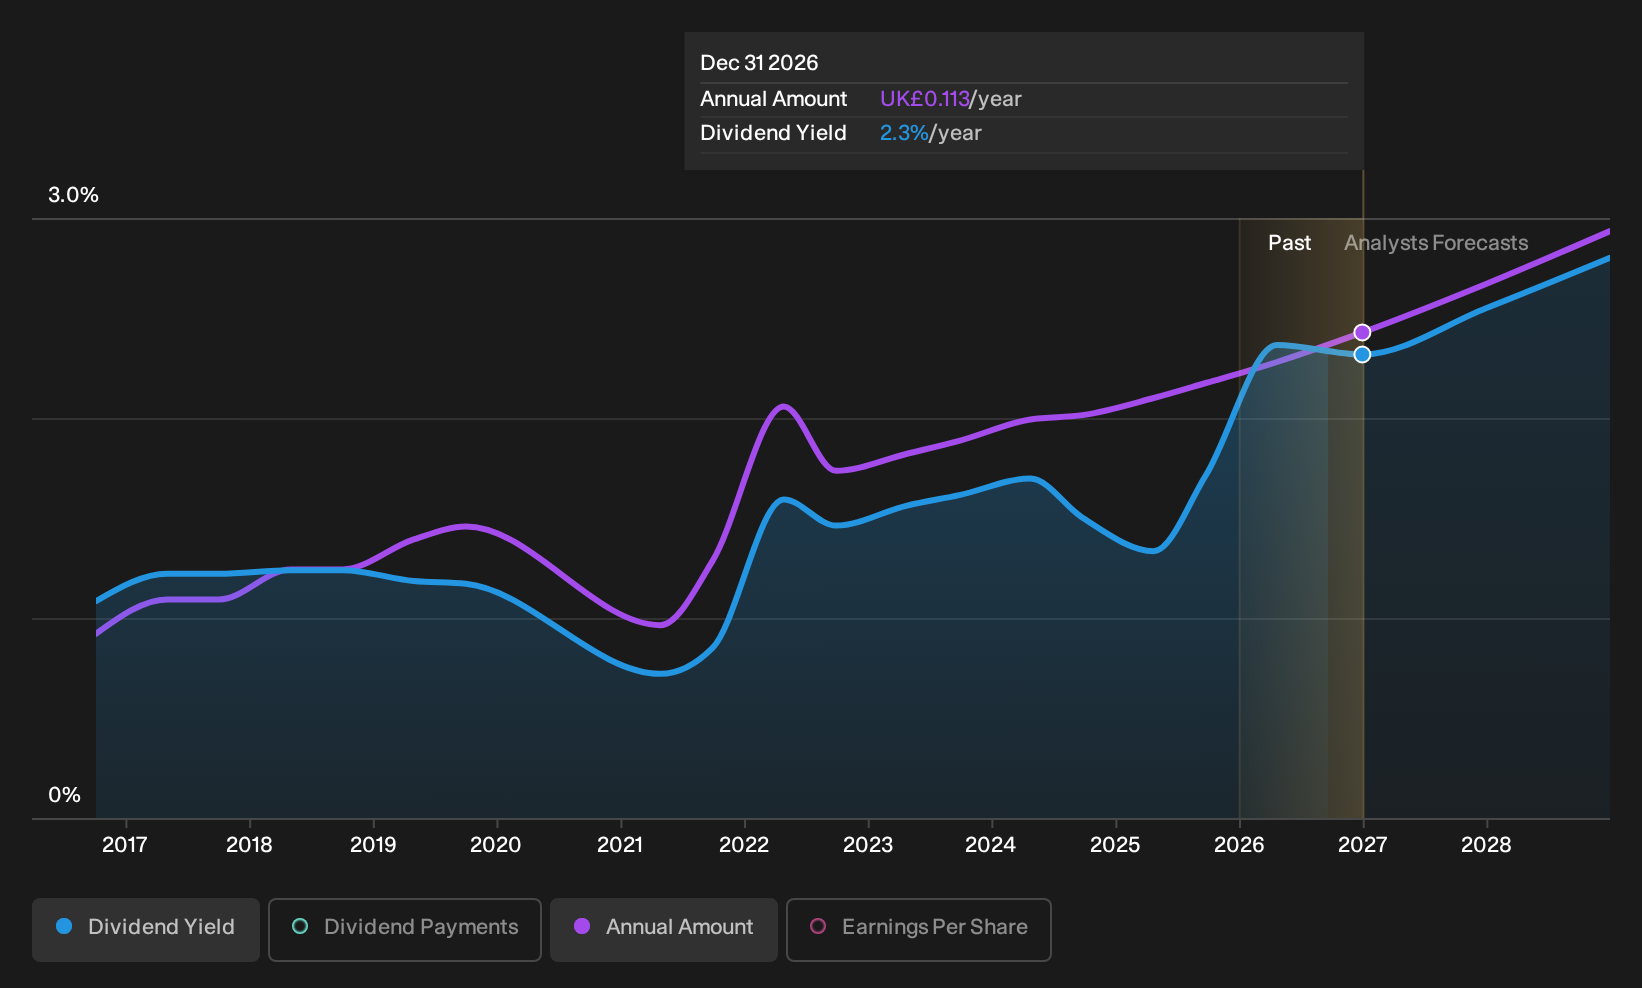
The company's next dividend payment will be UK£0.0417 per share, on the back of last year when the company paid a total of UK£0.11 to shareholders. Calculating the last year's worth of payments shows that Rightmove has a trailing yield of 2.2% on the current share price of UK£4.889. Dividends are an important source of income to many shareholders, but the health of the business is crucial to maintaining those dividends. That's why we should always check whether the dividend payments appear sustainable, and if the company is growing.
Dividends are typically paid from company earnings. If a company pays more in dividends than it earned in profit, then the dividend could be unsustainable. Rightmove paid out a comfortable 37% of its profit last year. Yet cash flows are even more important than profits for assessing a dividend, so we need to see if the company generated enough cash to pay its distribution. Fortunately, it paid out only 36% of its free cash flow in the past year.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
See our latest analysis for Rightmove
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Companies with consistently growing earnings per share generally make the best dividend stocks, as they usually find it easier to grow dividends per share. If earnings fall far enough, the company could be forced to cut its dividend. Fortunately for readers, Rightmove's earnings per share have been growing at 19% a year for the past five years. The company has managed to grow earnings at a rapid rate, while reinvesting most of the profits within the business. Fast-growing businesses that are reinvesting heavily are enticing from a dividend perspective, especially since they can often increase the payout ratio later.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. Rightmove has delivered 9.5% dividend growth per year on average over the past 10 years. We're glad to see dividends rising alongside earnings over a number of years, which may be a sign the company intends to share the growth with shareholders.
The Bottom Line
Is Rightmove worth buying for its dividend? It's great that Rightmove is growing earnings per share while simultaneously paying out a low percentage of both its earnings and cash flow. It's disappointing to see the dividend has been cut at least once in the past, but as things stand now, the low payout ratio suggests a conservative approach to dividends, which we like. Rightmove looks solid on this analysis overall, and we'd definitely consider investigating it more closely.
In light of that, while Rightmove has an appealing dividend, it's worth knowing the risks involved with this stock. To help with this, we've discovered 1 warning sign for Rightmove that you should be aware of before investing in their shares.
If you're in the market for strong dividend payers, we recommend checking our selection of top dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.